

‘Really different’: SGX RegCo’s Tan Boon Gin looks to exorcise S-chip ghosts
The regulator’s chief is confident that the ‘second’ coming of Chinese listings will not lead to a repeat of corporate governance scandals
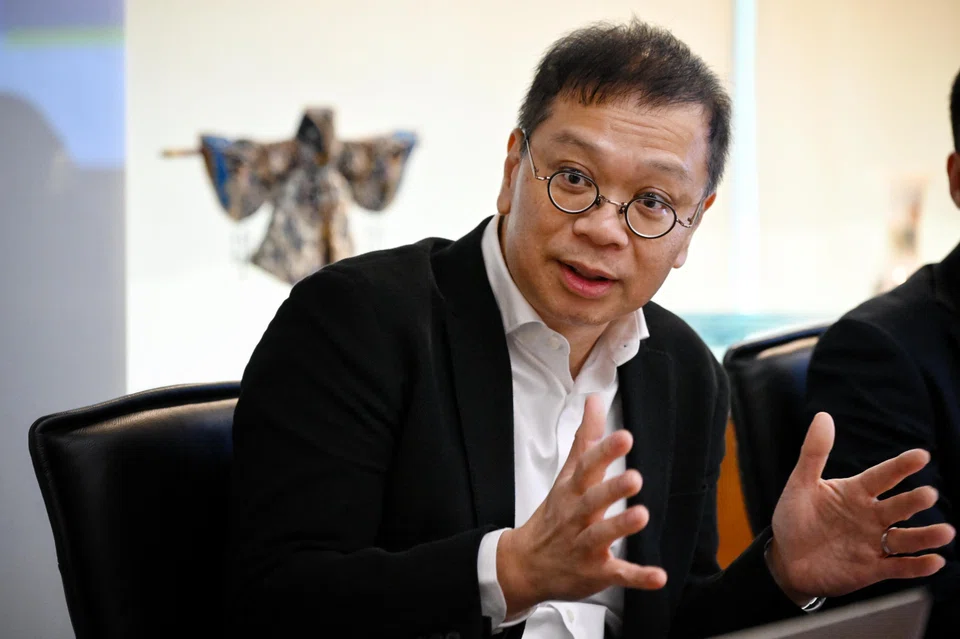
[SINGAPORE] The mention of “S-chips” – China-based businesses, often incorporated in offshore jurisdictions, that were listed on the Singapore Exchange (SGX) – is usually shorthand for corporate governance nightmares.
Between the late 2000s and early 2010s, a series of scandals involving these companies – think “missing” cash piles, phantom factories and the sudden disappearances of chief executive officers – left retail investors holding the bag.
But Tan Boon Gin, CEO of SGX Regulation (SGX RegCo), is looking to fundamentally rewrite that script.
To dispel the longstanding distrust surrounding Chinese listings, SGX RegCo is betting that a combination of national-level diplomacy and high-threshold “market discipline” will ensure the next wave of Chinese companies is a far cry from their scandal-ridden predecessors.
At the heart of this effort is a new framework that emerged from the Singapore-China Joint Council for Bilateral Cooperation – the two countries’ highest platform for collaboration.
Coming out of the joint council’s meeting last December were significant new initiatives between the Monetary Authority of Singapore (MAS) and the China Securities Regulatory Commission (CSRC) to support Chinese companies’ secondary listings on SGX.
And Tan is confident that this “second coming” will not result in a repeat of the S-chip scandals.
For one, the focus has shifted decisively. The primary listings of the past often featured small-cap minnows from obscure provinces in China; now, the attention has moved towards secondary listings of established A-share giants trading on the Shanghai and Shenzhen bourses.
“What’s really different between now and then is that you now have an added level of scrutiny from the national regulator in China, the CSRC,” Tan told The Business Times in an exclusive interview.
By targeting secondary listings, SGX RegCo is effectively leveraging the massive oversight of the CSRC. Because these companies are primarily listed in Shanghai or Shenzhen, the CSRC – and the onshore exchanges – remains the primary regulator, creating a “huge alignment of interest” with Singapore.
In the new regulatory era, a financial discrepancy in Shenton Way is no longer just a local reporting issue – it is a direct affront to Beijing’s own market integrity.
”If we were to spot anything wrong here in Singapore, they would definitely want to know and they would definitely want to check,” Tan said.
To make certain that only the highest-quality firms make the cut, SGX RegCo has instituted certain regulatory guard rails.
First, the framework targets large-cap companies, which typically have a market valuation exceeding S$1 billion. In addition, issuers must raise at least S$200 million – or 10 per cent of their market cap, whichever is lower – upon listing in Singapore.
This fundraising requirement is a deliberate bit of market Darwinism. “We want market discipline to kick in,” Tan explained. “If the market is not sufficiently comfortable with this company, the market will not clear that bill.”
In other words, a listing is no longer a regulatory checkbox – it is a commercial endorsement. If institutional “smart money” won’t put up S$200 million, the company doesn’t get onto the board.
“Singapore-washing”
The regulator is also tackling the “Singapore-washing” critique – the idea that Chinese firms seek an SGX ticker simply to buy a veneer of international credibility without changing their opaque ways.
“If you look at the framework, there are two principal safeguards,” Tan noted. “CSRC has to clear (these companies) on the suitability to list here. Then, they have to justify to the market why they want to list here. And the market will look at the explanation and decide.”
He added: “Hence, we have the S$200 million fundraise requirement. We want the market to scrutinise these companies and then gear up.”
He also pointed to other significant structural changes. For instance, China is now a signatory to the International Organization of Securities Commissions multilateral memorandum of understanding.
This facilitates real-time cross-border information sharing that didn’t exist during the S-chip scandals a decade ago.
The push for Chinese secondary listings is part of a broader revitalisation of the Singapore market, spearheaded by MAS’ equities market review group. Recent moves include injecting public funds to seed growth.
For an exchange often criticised for being a “zombie market” – apart from the banks, blue-chips and real estate investment trusts – the return of Chinese capital would be a significant win.
For Tan, the immediate goal is fundamental: proving that the ghosts of the S-chip era have finally been laid to rest by a system that values quality and market conviction over raw listing numbers.
TRENDING NOW

VietJet hit with global asset freeze in FitzWalter dispute
FCT, NLB to turn Causeway Point’s former cinema space into reading hub in mall revamp
Family offices ‘kept captive’ by relationship managers turn to independent advisers, direct deals
Olivia Lum, ex-CFO not giving evidence in their Hyflux trial

