

Regulate liquidity, not just capital, to better stabilise financial systems
The global banking turmoil in 2023 shows that capital alone is not sufficient for a bank to operate, says BWC chair
REGULATORS should improve liquidity management at banks to create a more stable financial system, as capital requirements may not be enough to do the job.
“(When) you raise the capital requirements on banks, you make banks less competitive and push activity out into the non-bank financial sector, where regulators don’t have a lot of visibility,” said William Dudley, chair of the Bretton Woods Committee (BWC), on Friday (Sep 13). US-based BWC was set up to advocate for global economic and financial cooperation.
“The goal shouldn’t be about making banks bulletproof; the goal should be making the financial system as stable as possible,” he added.
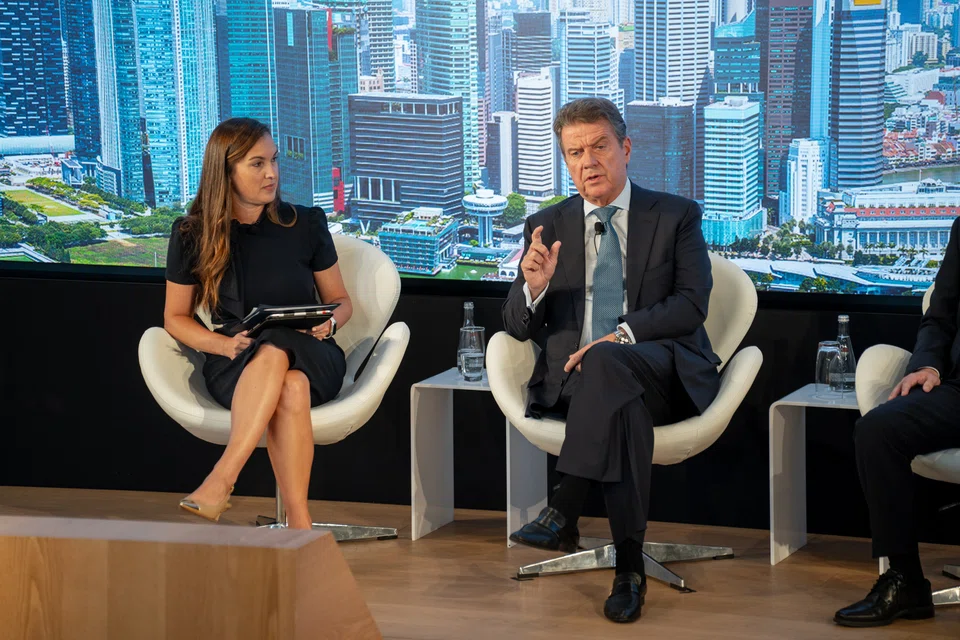
Dudley, who is also former president and CEO of the Federal Reserve Bank of New York, was speaking on a panel of bankers and financial regulators about re-examining the regulatory landscape at BWC’s Future of Finance Forum 2024.
Also on the panel were Colm Kelleher, chairman of UBS Group, and Chia Der Jiun, managing director of the Monetary Authority of Singapore. The panel was moderated by BWC executive director Emily Slater, and hosted by UBS in Singapore on Friday.
While capital is a necessary condition for a bank to operate, it may not be sufficient, as proven by the global banking turmoil in 2023, Dudley said. Deposits now run faster, whether due to social media or concentration risks.
A solution would be to bolster the function of the central bank as a lender of last resort, he added.
For example, Kelleher noted a proposal from the Group of 30 (G-30) to require banks to hold collateral at the Fed’s discount window for liquidity needs. The G-30 comprises economists, bankers and other financial leaders, and is chaired by Dudley.
Dudley said: “If people pledged sufficient collateral to the Fed to backstop all their runnable liabilities and uninsured deposits, those uninsured depositors wouldn’t have a reason to run in the first place.”
Meanwhile, Chia said regulators needed to watch the intersection of liquidity risks and risks to capital.
Regulators should do wide stress-testing constantly, and look into business models and culture and conduct in individual organisations, he said.
As activity picks up among non-bank financial institutions (NBFIs), Kelleher noted that global regulators are starting to understand the growing problem of the lack of visibility.
He noted that financial intermediaries now account for 50 per cent of world financial assets, from 38 per cent in 2007, and regulators do not understand what the risk around it is.
“I’m not saying to regulate (NBFIs), but know what the risks are, and that’s what the regulators should be focused on,” he said.
He added that while the non-bank sector still brings huge benefits, it presents a difference in risk management that regulators need to be aware of.
“The banking system permits liquidity, protects depositors, and gives a return within a well-regulated regime. The non-bank system gives risk at a price that people should know what they’re paying for,” he said.
Chia noted that the migration from banks to non-banks has been happening for a while, with private credit being the latest trend.
The Singapore regulator is still trying to understand the full implications. While this migration has not been “highly precipitous”, Chia said the global regulatory and central bank community should continue to study the space “quite carefully”.
Addressing UBS’ takeover of Credit Suisse in March 2023, Kelleher said that a resolutions framework by the Swiss regulator would have worked.
However, it would have resulted in contingent damages, and the market would rather have solutions than contamination, he said.
Dudley said a resolutions framework is necessary as a pullback.
“There’s not always going to be a healthy bank there to merge with the not-healthy bank, because it might not be a problem that’s just idiosyncratic to one institution,” he pointed out.
But he also said that regulators need to recognise that a resolution regime cannot cure all ills, especially if a bank is poorly managed, has an unsustainable business plan, or if people have lost confidence.






