

Singapore office Reits expected to stay resilient despite headwinds for global office landlords
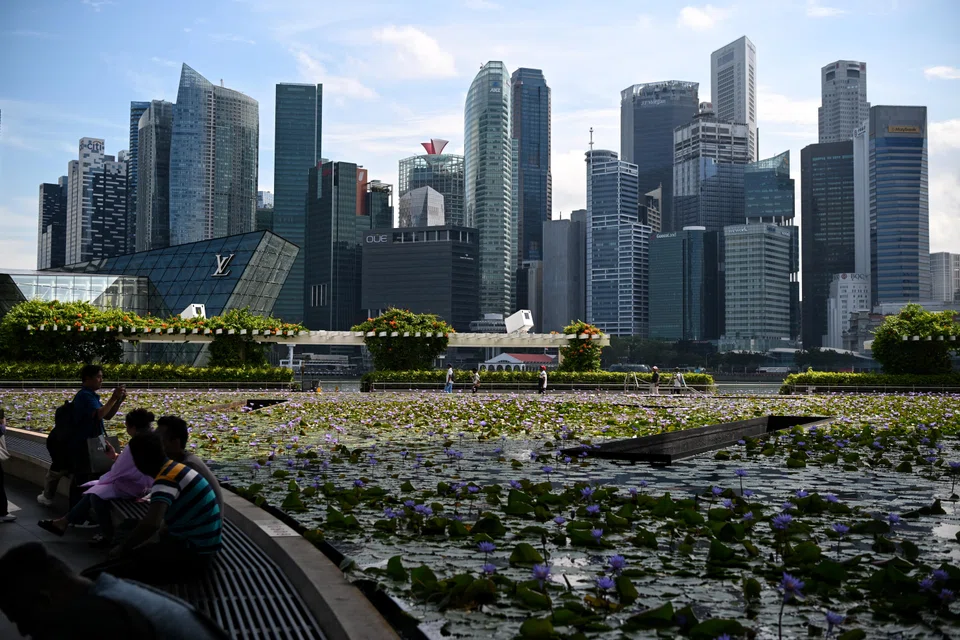
DESPITE signs of cooling in Singapore’s Central Business District (CBD) office rents, real estate investment trust (Reit) analysts believe local office landlords will remain more resilient than those with overseas assets.
In the second quarter of 2023, gross effective rent for CBD Grade A office climbed 0.2 per cent quarter on quarter to an average of S$11.33 per square foot per month, according to property consultancy JLL.
This was a slowdown from the 1.2 per cent and 1.1 per cent quarter-on-quarter growth in Q4 2022 and Q1 2023, respectively, JLL said in a recent report.
JLL Singapore’s head of research and consultancy Tay Huey Ying believes rents may go into “correction mode” in the second half of 2023, given that near-term demand will likely fall short of supply.
Similarly, CBRE Research noted that the total amount of shadow space – excess space with an existing lease obligation that a tenant would like to give up midterm by finding a replacement for the landlord – in the office sector remains “quite high”.
Tricia Song, CBRE head of research, Singapore and South-east Asia, said that certain groups of office occupiers such as tech or cryptocurrency players continue to face challenging business conditions.
“A number of such firms may consider giving up office space, potentially contributing to more shadow space in the second half of the year,” she said.
Singapore-listed Reits (S-Reits) with exposure to office assets here, such as Suntec Reit , OUE Commercial Reit and Keppel Reit , have delivered a muted performance over the past 12 months.
As at Jul 7, the counters have fallen 16 per cent to 21 per cent over the past year. In comparison, the iEdge S-Reit index has declined around 13.4 per cent over the same period.
But local office landlords have still fared better than S-Reits with assets overseas – including Manulife US Reit , Prime US Reit and Elite Commercial Reit – which rank among the worst performers in the sector.
Over the past year, such counters have fallen between 52.8 per cent and 70.6 per cent.
Carmen Lee, head of OCBC investment research, noted that markets such as the US and Hong Kong have seen commercial real estate prices on a downtrend amid hybrid working trends, and companies vacating some of their spaces.
“Those are actually quite worrying factors globally,” she said, adding that there has not been a very significant impact yet in Singapore, largely because supply is not excessive.
“If the environment continues to be very soft, then obviously the propensity for you to actually raise rental income is actually going to be somewhat more limited.”
While there are some headwinds in the sector, analysts still believe that S-Reits with Singapore office exposure would hold up better than their counterparts with offshore assets.
Maybank analyst Krishna Guha noted that Singapore’s overall commercial sector asset values have been relatively stable due to safe haven appeal, as well as assumption of rental growth offsetting higher discount rates.
“Office sector enjoys limited supply even though there are pockets of demand weakness,” he said. “We expect asset values to be relatively more resilient than the offshore office sector.”
Phillip Securities research analyst Liu Miaomiao noted that there is still demand from smaller players in financial services or tech sectors to support local office demand, and physical occupancy rates remain healthy.
“With the slower economic activities and downsizing of big companies, we expect the rental reversion to be flattish,” she said.
She observed that there will be risk of overvaluation for office properties as interest rates are likely to remain higher for longer, with hybrid work arrangements more favoured by professionals.
However, investors’ main concerns would likely remain with US office Reits given the oversupply in the market and downsizing of tenants.
“With high possibility of another interest rate hike in July, valuation of US office Reits could further deteriorate,” she said.
RHB analyst Vijay Natarajan noted that the Asia-Pacific office market – particularly Singapore – remains more resilient as the return to office has reached levels of 70 per cent to 80 per cent.
Supply has also been “manageable”, while demand is also supported by tenants displaced from redevelopment of older buildings and “flight-to-quality” trends.
“Overall, we expect high-quality office buildings which are well located with amenities to emerge stronger post crisis and maintain their value,” he said.
He added that there is a small risk of cap rate expansion, but he does not expect valuation declines to be significant, coming in at less than 5 per cent.
However, he expects valuation declines for US and Europe office buildings of up to 15 per cent, due to sharp interest-rate hikes and hybrid working trends.
“This will largely vary depending on individual submarket demand-supply dynamics and underlying hybrid working trends,” he said.
Natarajan added that US office Reits remain the most vulnerable from a potential shift in valuation.
“But overall, we believe a lot of these negative expectations are largely priced in at current share price levels.”
TRENDING NOW

Genting Singapore trails MBS, but helps anchor Malaysian parent group’s finances

Siti Hasmah, wife of Malaysia’s ex-PM Mahathir, dies aged 100

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Why US midterm elections could power the next stock market rally

