

Softer earnings expected for S-reits in first half, with funding cost among headwinds
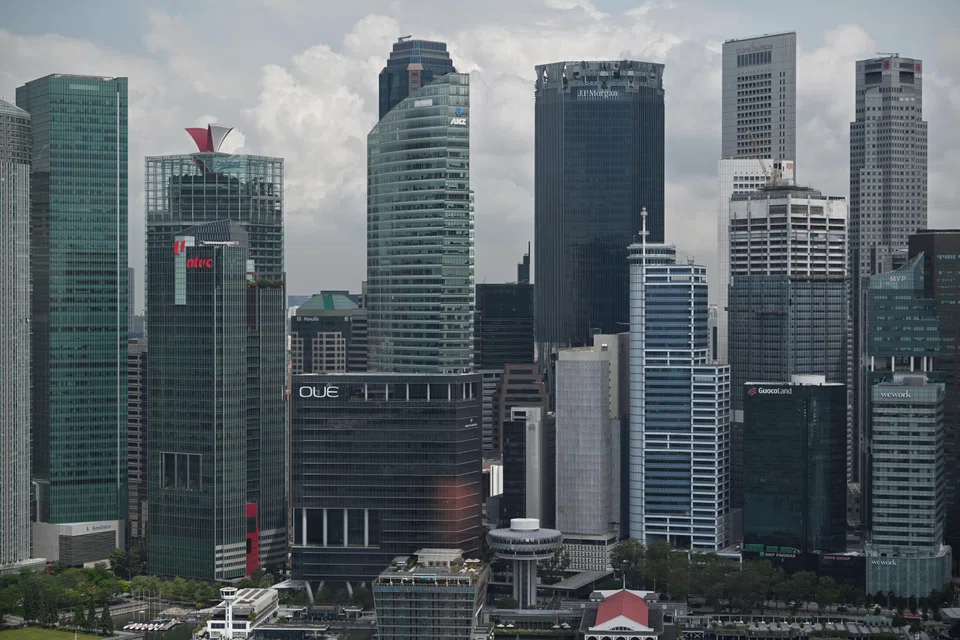
ANALYSTS are expecting muted results from Singapore-listed real estate investment trusts (S-Reits) for the first half of 2023. High interest rates and a strong Singapore dollar are among the potential drags on their performance.
Key metrics to watch include property valuations as well as how individual Reits are coping with interest cost pressures and refinancing.
“Overall, we expect a soft earnings report for H1 2023 for the majority of the S-Reits, with the exception of a few in the industrial, healthcare and office/retail sector,” said RHB analyst Vijay Natarajan, who expects many Reits to report lower distributions per unit (DPUs).
Weaker DPUs would likely be due to pressures from rising interest costs outpacing operational gains, he added.
Interest rates globally have risen over the past year as central banks worldwide try to combat elevated inflation.
While the US Federal Reserve last month paused its rate hikes, there are still expectations that rates could go up by another 50 basis points by year-end.
DBS analysts Derek Tan, Rachel Tan, Dale Lai and Geraldine Wong said in a note that an extended period of high rates could result in continued erosion in DPUs until 2024.
“A prolonged period of high interest rates till the end of 2024 would potentially drive portfolio debt costs up by another 30 basis points,” they said, adding that their sensitivity analysis shows up to a 4 per cent decline in DPUs in a scenario of protracted high rates.
Sectors that would be most affected include US offices, China retail and selected office and retail segments, they added.
Maybank analyst Krishna Guha also sees distributions being impacted by funding costs, even though he expects healthy operational metrics for the quarter ended June.
“I expect sequential slowdown in distributions for retail, office and hospitality due to a combination of seasonality, high base effect and normalisation of reopening tailwinds,” he said, adding that valuation and gearing would be the key metrics to watch for, especially valuation of offshore assets.
Reits with offshore assets may also have foreign exchange risks to contend with. Liu Miaomiao, research analyst at Phillip Securities, observed that the stronger Singapore dollar could further add pressure on DPU for Reits with overseas assets.
In such an environment, DBS analysts believe a “conservative stance” is wise, with preference for “resilient” sub-sectors such as industrial or hotel S-Reits that have stronger portfolio cashflows.
Their picks include CapitaLand Ascendas Reit and Mapletree Logistics Trust (MLT). CapitaLand Ascendas Reit will report its first-half results on Jul 31, while MLT will announce its first-quarter results on Jul 25.
Other industrial S-Reits that have announced the date of their financial results include Sabana Reit (Jul 19), Keppel DC Reit (Jul 24), Mapletree Industrial Trust and ESR-Logos Reit (Jul 26), and Digital Core Reit (Jul 27).
The DBS analysts are also expecting suburban retail players to offer better DPU resiliency.
Frasers Centrepoint Trust’s third-quarter business update will be released on Jul 25, while Mapletree PanAsia Commercial Trust will announce its first-quarter results on Jul 31. CapitaLand Integrated Commercial Trust reports its first-half result on Aug 1, while Lendlease Global Commercial Reit will announce its full-year results on Aug 7.
Most analysts also continue to expect the hospitality segment to outperform.
Phillip Securities’ Liu said: “We remain positive on the hospitality sector as there are more influx of Chinese tourists.”
She added that revenue per available room is expected to rise as more Singapore hotels exit government contracts.
RHB’s Natarajan also believes that there would be a better performance on a year-on-year basis from hospitality, as well as selected industrial and healthcare Reits amid “operational resilience” and rent growth.
“Hospitality sector is likely to be the major outlier with a strong DPU growth on the back of pent-up demand and revenge tourism and a low base effect,” he said.
Hospitality S-Reits scheduled to release their results for the first half ended June include CapitaLand Ascott Trust (Jul 27), and CDL Hospitality Trusts and Far East Hospitality Trust (Jul 28).
Expectations for office Reits, however, are less rosy.
The DBS analysts expect most S-Reits to be able to keep earnings above three times interest expense.
The exception would be office and US office S-Reits, which have higher leverage ratios.
“We anticipate that these S-Reits will likely pursue asset sales or selective fundraising to recapitalise their balance sheets,” they said.
Keppel Reit will release its results on Jul 25, while OUE Commercial Trust, Keppel Pacific Oak and Suntec Reit will announce their earnings on Jul 26.
While financial metrics would be the likely drags on performance in the first half, analysts are also keeping an eye out for operational numbers.
Natarajan said that occupancy or weakness in rental growth arising from the slowing economy in Singapore and globally are areas to watch for.
Meanwhile, Liu noted that rising vacancy rates would place pressure on valuations, with valuation risk more elevated for US office players.
She added: “Rental reversion in office and industrial sector may dampen due to the slower economic activities.”
TRENDING NOW
Olivia Lum, ex-CFO not giving evidence in their Hyflux trial
Bank on AI-resilient Singapore property via deep-value listed property groups
Positive pivot or premature? Analysts split on Keppel Reit’s S$610.9 million buy

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

