

SVB collapse puts spotlight on S-Reits’ balance sheets
Jude Chan
THE shocking collapse of Silicon Valley Bank (SVB) ought to be a wake-up call to investors to pay more attention to the balance sheets of listed companies.
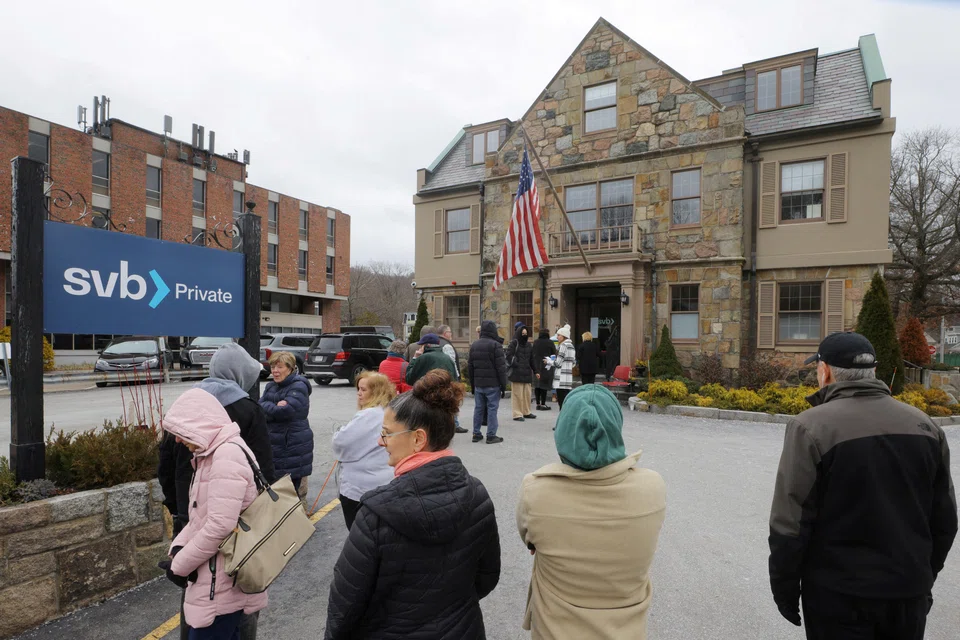
SVB, America’s 16th largest commercial bank, had provided banking services to nearly half of all US venture-backed technology and life-science companies.
But a plan to raise capital and shore up its balance sheet led to a run on the bank. Less than 48 hours following the announcement, it avalanched into the biggest US bank failure since the global financial crisis.
At the heart of SVB’s demise were the interest rate hikes by the United States Federal Reserve, aimed at quelling decades-high inflation rates.
The jump in interest rates dried up the bank deposits of struggling startups amid a venture capital funding drought, as well as an erosion in the value of SVB’s bond portfolio.
The collapse of the California-based lender was sudden and surprising. And the shockwaves were felt as far as Singapore and the rest of Asia, where fears of contagion continue to roil capital markets.
Although markets are now anticipating a slower pace of hikes from central banks seeking to contain a potential contagion, there is widespread anticipation of tougher credit conditions.
This could be troublesome for real estate investment trusts (Reits) – one of the favoured asset classes among investors in Singapore.
Singapore-listed Reits (S-Reits), already wrangling higher financing costs, face a tough year ahead due to increases in aggregate leverage. This metric, also known as the gearing ratio, weighs a Reit’s total debt against its total assets.
The aggregate leverage levels of more than half – 22 out of 40 – of the actively traded S-Reits had risen as of end-2022, compared with the last reported data.
For many of these S-Reits, the higher aggregate leverage was due to a decline in portfolio asset value following the conclusion of year-end property revaluations.
For example, the aggregate leverage of Manulife US Reit jumped to 48.8 per cent from 42.5 per cent previously, mainly due to a 10.9 per cent drop in its portfolio valuation.
In contrast, only 15 of the 40 S-Reits reported a decline in gearing ratios; another two were unchanged.
Another S-Reit, Dasin Retail Trust , has not reported its financial results for the latest financial period. The trustee-manager asked to be allowed to announce its FY2022 results by end-April 2023.
S-Reits are required to maintain aggregate leverage at under 50 per cent if the minimum adjusted interest coverage ratio is at 2.5 times.
If the interest coverage ratio falls below 2.5 times, the maximum allowable aggregate leverage is at 45 per cent.
Besides Manulife US Reit, another S-Reit that has seen its aggregate leverage rise beyond 45 per cent is Elite Commercial Reit.
The UK-focused Reit reported a gearing ratio of 45.8 per cent as at end-December, up from 41.9 per cent as at end-June.
Elite Commercial Reit’s portfolio valuation fell 6.8 per cent year on year to £466.2 million (S$763.6 million) as at Dec 31, 2022. This was also 9.9 per cent lower than its mid-year valuation as at end June.
Meanwhile, Lippo Malls Indonesia Retail Trust (LMIRT), whose gearing ratio is at 44.6 per cent, has nearly hit the limit as its interest coverage ratio stood at just 2.3 times.
The Reit manager attributed the increase in aggregate leverage, from 43.7 per cent previously, to the depreciation of the Indonesian rupiah against the Singapore dollar.
Fitch Ratings last week downgraded LMIRT’s issuer default rating – for the second time in three weeks – to “CCC”, as it continues to worry over refinancing risks.
According to data compiled by the Singapore Exchange, the average gearing ratio of the 40 S-Reits and property trusts currently stands at 37.7 per cent.
A higher gearing ratio could cripple growth, diminishing a Reit’s capacity to take on more debt for future acquisitions. It could also lead to credit concerns, especially during economic downturns.
As credit conditions get tough, investors should take a closer look at Reits with lower gearing ratios. After all, the higher debt headroom could mean a bigger war chest for accretive acquisitions.
Currently, three S-Reits have aggregate leverages below 30 per cent: Sasseur Reit (27.6 per cent), Frasers Logistics & Commercial Trust (27.9 per cent) and Paragon Reit (29.8 per cent).
If the Reit managers play their cards right, this could provide an invaluable advantage amid uncertain times.
SVB has reminded us that even big companies can fold almost overnight. Did someone say distressed sales?






