RHB maintains 'buy' on DBS, says dividend payout not impacted by MAS supervisory action
DBS shares rise 0.3% but lag behind UOB's 2.3% and OCBC's 1.3% gain
Singapore
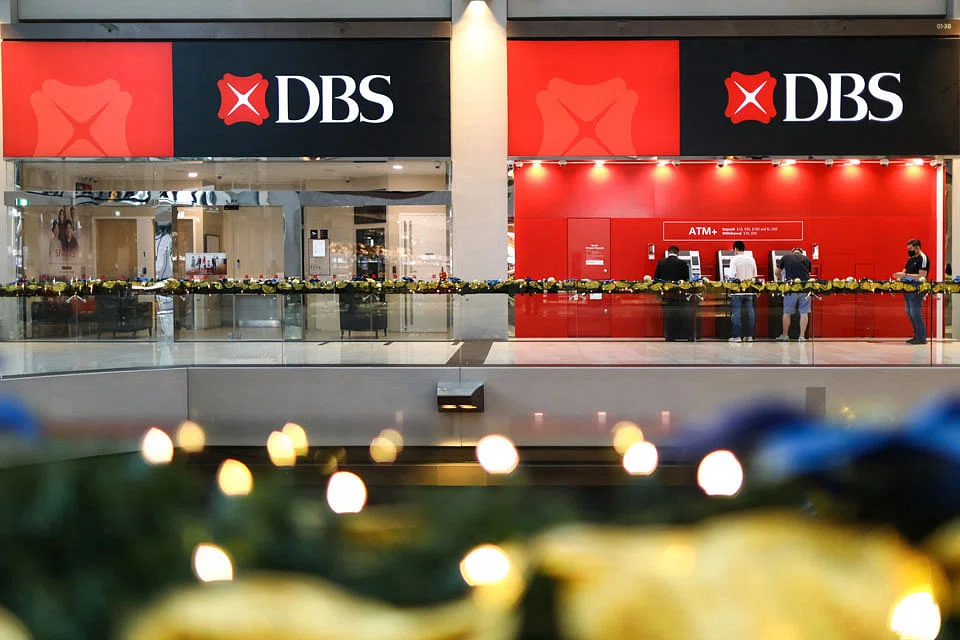
RHB on Tuesday (Feb 8) maintained a "buy" call on DBS with a target price of S$40.40, after the bank was directed by the Monetary Authority of Singapore (MAS) to set aside an additional S$930 million in regulatory capital following the prolonged disruption of its digital banking services last November.
MAS had announced on Monday that it has imposed an additional capital requirement on DBS by requiring the bank to apply a multiplier of 1.5 times to its risk-weighted assets for operational risk.
RHB said DBS' dividend policy will not be affected by the penalty, even though the additional capital requirement of S$930 million will have an impact of 40 basis points (BPS) on the bank's capital ratios.
This is because DBS' pro-forma common equity tier 1 (CET-1) of 13.4 per cent remains at the upper end of its target CET-1 range, inclusive of the capital impact from its acquisition of Citibank's Taiwan consumer banking operations, the brokerage said. The CET-1 ratio refers to the bank's core equity capital against risk-weighted assets.
DBS' management has also reiterated that the bank's dividend policy will remain intact.
The brokerage has estimated a dividend yield of about 4 per cent.
DBS shares ended Tuesday up 10 cents or 0.3 per cent at S$36.58, outpaced by rivals UOB and OCBC, which gained 2.3 per cent and 1.3 per cent, respectively.
Meanwhile, MAS has also directed DBS to appoint an independent expert to conduct a comprehensive review of November's 2-day tech disruption, including the bank's recovery actions. The bank has attributed the disruption to an issue with its access control servers and said that it was not a cyber attack.
The additional capital requirement will be reviewed when MAS is satisfied that DBS has addressed and rectified all identified shortcomings.