

S-Reit picks to ride on ‘structural growth trends’ in H2
Jude Chan
HEADING into the second half of 2022, investors should focus on real estate investment trusts (Reits) that can deliver sustainable growth in the near to mid term.
“Risk of interest rates impacting distributions is well flagged out, but given the way we see base rates increasing, we believe that the actual impact could be a tad more than expected,” said DBS analyst Derek Tan.
Against this tough backdrop, it is important that investors focus on Singapore Reits (S-Reits) with the potential of delivering growth in their distribution per unit and net asset value. On top of that, Tan said investors should keep an eye out for S-Reits with low refinancing risks.
Analysts who spoke to The Business Times pointed to Reits in the Singapore office, suburban retail and industrial sectors as among those that could potentially benefit from “structural growth trends” going into H2.
“We like the office sector, so our favourite (S-Reit pick) would be Keppel Reit,” Tan said.
For one, the analyst sees Keppel Reit as a purer play to the Singapore office sector. “(It has a) robust outlook, coupled with minimal risk to refinancing and operational cost challenges,” he added.
According to SGX Research, Keppel Reit was one of the top 5 S-Reits that booked the highest net institutional inflows in the first half of 2022, proportionate to their current market capitalisation.
More than three-quarters of Keppel Reit’s S$9 billion portfolio as at December 2021 was located in Singapore. It also held assets in Australia and South Korea.
For FY2021 ended December, Keppel Reit reported a 31.4 per cent jump in net property income (NPI) attributable to unitholders to S$155.8 million.
Distributable income rose 9 per cent to S$212.1 million, while distribution per unit (DPU) was up 1.6 per cent to S$0.0582.
Units of Keppel Reit closed at S$1.09 on Monday (Jul 4), reflecting a yield of 5.3 per cent based on its FY2021 DPU.
Meanwhile, RHB analyst Vijay Natarajan favours Ascendas Reit as his top Reit pick.
“Ascendas Reit is the largest industrial S-Reit and a good proxy to the Singapore industrial segment – which accounts for 60 per cent of its assets,” Natarajan said. “This, in our view, offers the best mix of defensive cum growth potential.”
In addition, Natarajan said Ascendas Reit’s trading at around 5.5 per cent yield is “attractive”, with most downside risks already buffered in.
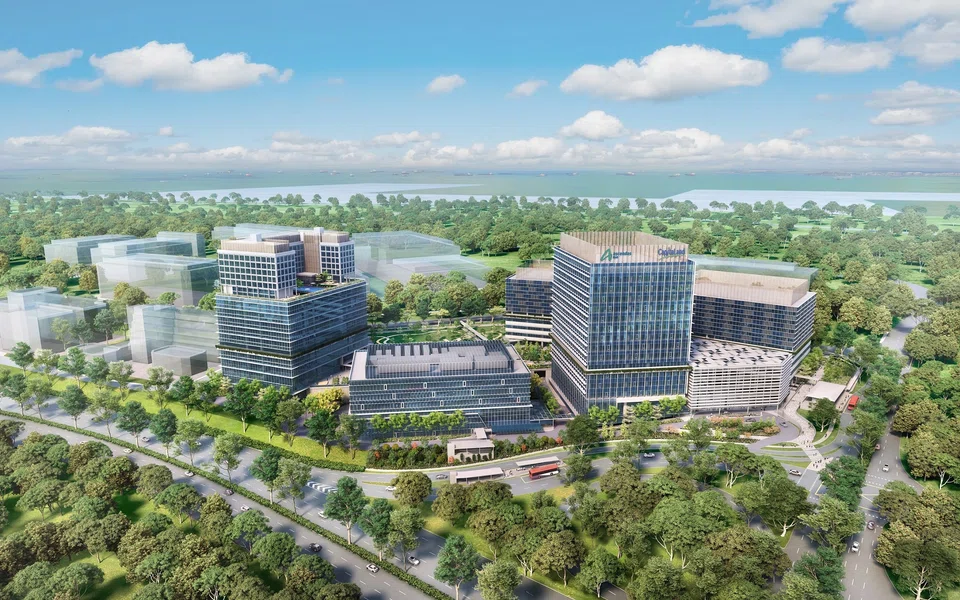
Ascendas Reit - the first and largest locally listed industrial Reit - had S$16.3 billion in assets under management as at Dec 31, 2021. Its portfolio comprises some 220 properties across the developed markets of Singapore, Australia, the US, UK and Europe.
Ascendas Reit reported a 16.9 per cent rise in gross revenue to S$1.2 billion for FY2021, while its NPI climbed 18.6 per cent to S$920.8 million.
The Reit posted a 3.9 per cent increase in DPU to S$0.15258. Based on its closing price of S$2.87 on Jul 4, this translates to a yield of 5.3 per cent.
On the retail front, Natarajan said the potential accretive acquisition of the Mercatus suburban mall portfolio could be a key catalyst for Frasers Centrepoint Trust (FCT) .
“We see a good possibility of FCT teaming up with its sponsor to acquire the 4 suburban retail assets from Mercatus Co-operative,” he said in a recent report. “(This) in our view presents a good strategic fit to FCT’s portfolio and could further boost the Reit’s standing as a dominant suburban mall player in Singapore.”
As at end-September 2021, FCT’s portfolio comprised 9 retail malls and an office building located in the suburban regions of Singapore, with assets under management of around S$6.1 billion.
For FY2021 ended September, FCT’s gross revenue more than doubled to S$341.2 million, while NPI soared 122.4 per cent to S$246.6 million.
DPU for FY2021 came in 33.7 per cent higher at S$0.12085. Units of FCT closed at S$2.26 on Jul 4, representing a yield of 5.3 per cent based on its FY2021 DPU.
Aside from FCT, DBS’s Tan believes that the Mercatus sale is likely to also attract other local property players. These include fellow S-Reits CapitaLand Integrated Commercial Trust (CICT) and Lendlease Global Commercial Reit (LREIT) , as well as property developers City Developments and Far East Organization.
“This transaction is expected to support capital values for retail malls in the suburban space, with selected malls in CICT, FCT, and LREIT to benefit,” Tan said in a recent report. “As such, we anticipate it to support valuations, implying that net asset valuations (NAVs) should remain resilient.”






