

S-Reits’ DPU may rise in FY2025 as interest costs peak
Their rent reversions held steady in Q4 FY2024
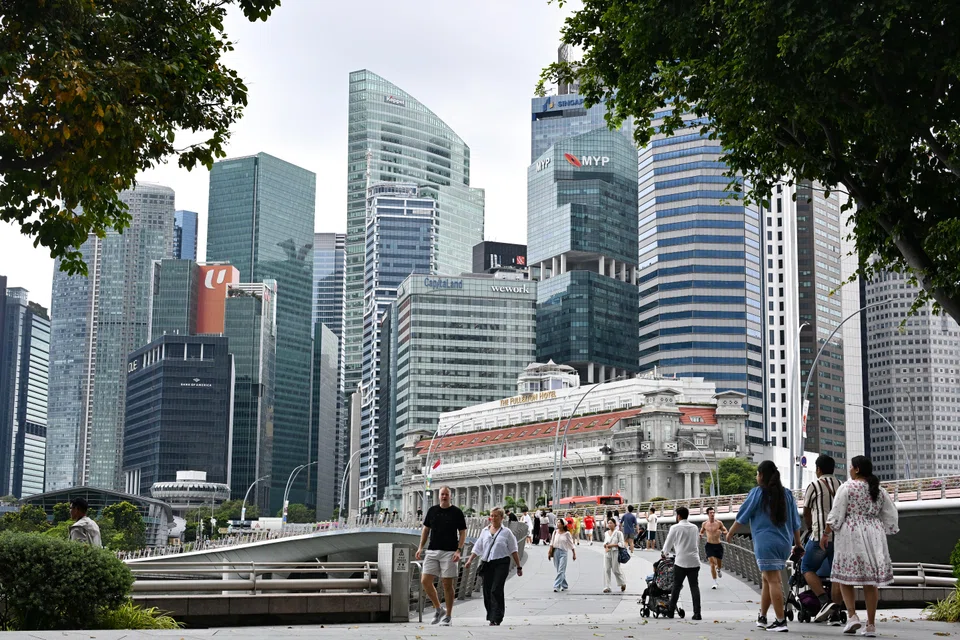
[SINGAPORE] High financing costs continue to weigh on Singapore-listed real estate investment trusts (S-Reits) in the latest round of financial results, but analysts believe there is room for their distribution per unit (DPU) to rise in FY2025, with interest costs peaking.
Distributable income and DPU continued to fall for the majority of S-Reits in the latest reporting season.
Of the 34 S-Reits and property trusts that disclosed their financial information for the period ended Dec 31, 2024, 19 posted declines in distributions and 21 reported lower DPUs, data compiled by The Business Times showed.
Performance was mixed when it came to revenue growth, with a fairly even split between those which posted higher revenue growth and those that did not.
The results, analysts said, were in line with expectations.
“The majority (of S-Reits) experienced year-on-year declines in DPU, primarily due to elevated financing costs impacting profitability,” said Liu Miaomiao, a senior research analyst at Phillip Securities Research.
Singapore assets performed better than their overseas counterparts in terms of net asset value and operations, noted Krishna Guha, an analyst at Maybank Securities.
“Steady” reversions for S-Reits
S-Reits’ rent reversions “held steady” in the fourth quarter of FY2024, said Macquarie Equity Research analysts in a note on Feb 21. In particular, strong reversions for Singapore assets held up most portfolio valuations.
Across the various sectors, logistics delivered the strongest reversions at positive double digits. The Macquarie analysts said they expected S-Reits’ reversions to remain positive in FY2025, although there may be a slight downward moderation.
Sector performance
The data centre sector’s performance stood out for FY2024, said Liu of Phillip Securities. She noted that Keppel DC Reit achieved a 39 per cent rent reversion during the year, fuelled by colocation contract renewals in Singapore.
“This momentum is projected to extend into 2025, underpinned by strong demand and constrained supply of data centre facilities in the region,” she added.
Although there were signs of a slowdown in the office Reit sector, Morningstar analyst Xavier Lee expected office rents to rise in the coming financial year. He said that with IOI Central Boulevard Towers nearing full occupancy, office vacancy rates will tighten, raising the sector’s rents.
IOI Central Boulevard Towers is a Grade A office development in the Central Business District. It is fully owned and managed by IOI Properties Singapore.
In the retail sector, occupancy rates remained relatively unchanged, with positive reversions in the mid- to high-teens, said Maybank’s Guha.
However, Macquarie’s analysts noted that tenant sales were “slightly soft” in Q4 FY2024 compared to the year-ago period, particularly for downtown malls. The decrease was in line with a dip in Singapore’s retail spending over November and December as more people travelled overseas.
Nevertheless, the analysts were optimistic on tenant sales in FY2025.
Interest rates
S-Reits have yet to benefit fully from the sharp drop in the Singapore Overnight Rate Average (Sora) last quarter, said Guha, who expects the sector to experience some tailwinds in the first half of 2025.
The Sora, which is an interest-rate benchmark for Singapore dollar loans, fell from a high of 3.9 per cent in September 2024 to 2.1 per cent in December 2024.
Macquarie’s analysts believe that the average cost of debt for most S-Reits is likely to peak soon. They noted that this was relatively stable in Q4 FY2024 compared to the quarter before, as most of the refinancing for the year was completed earlier.
They added that most S-Reits expect their average cost of their debt to inch up, but that the rate of increase will likely moderate between 10 and 30 basis points.
Among the Reits whose average cost of debt has peaked, according to analysts, are Frasers Centrepoint Trust , Keppel DC Reit and CapitaLand Ascott Trust . These Reits will likely be less affected by steeper interest costs in a higher-for-longer interest-rate environment.
On the other hand, Keppel Reit , Mapletree Industrial Trust and Mapletree Logistics Trust are expected to have some of their low-rate debt expire in FY2025. As a result, they may be hit by higher interest costs when they refinance their loans, said Macquarie.
Going forward
With interest costs falling, Liu expects S-Reits’ DPUs to grow at a modest rate of around 1 per cent in 2025, with broader benefits expected by 2026.
However, a slower-than-expected pace of central bank rate cuts may temper these gains, she added.
Morningstar’s Lee said that some S-Reits’ DPUs could decline as they remove distribution top-ups from their divestment gains, or face losses in contribution from divested assets.
Macquarie’s analysts said that they would downgrade Keppel Reit and Frasers Logistics and Commercial Trust (FLCT) to “neutral”. They expect Keppel Reit’s DPU to drop in FY2025 due to higher management fees paid in cash, and lower capital distributions from FLCT.
Several analysts also believe that S-Reits will benefit in FY2025 from changes proposed by the Monetary Authority of Singapore’s review committee to revive the local stock market.
However, Lee said that ultimately, S-Reits’ price performance will depend on the ability of Reit managers to grow their distributions over time.
TRENDING NOW

Singapore’s central gas buyer affirms Indonesia’s role as ‘important partner’ amid export review warning

Why the biggest business decision about AI isn’t which model to choose

Is Manila Asia’s new dining hot spot?

KKR founders among investors buying 42% of Peter Lim’s Valencia; club valued at US$1.4 billion

