

Sabana's manager wants to leave failed merger behind; will work on improving portfolio and performance
Singapore
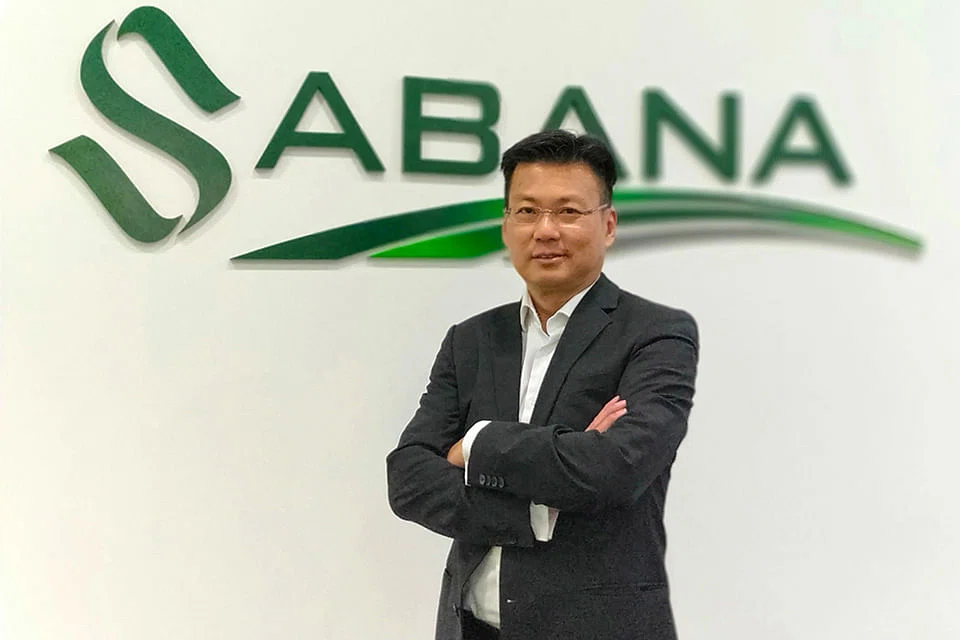
THE chief executive officer (CEO) of Sabana Shari'ah Compliant Industrial Reit's manager Donald Han has made it clear that he wants to leave behind the failed merger with ESR-Reit and work on improving the real estate investment trust's (Reit) portfolio and performance.
In a media call on Friday, he said: "I am generally a forward-looking person. There is a lot for us to do in 2021, being a new year. It's a start for us to continue with the refreshed strategy which we started two (to) three years ago, and that continues until we can stabilise our properties."
The Reit is in phase two of the strategy, which consists of rejuvenating select assets and proactively leasing and managing its assets. But perhaps the merger journey was not for nothing. Mr Han said the manager is trying to incorporate into its strategy the feedback it has received during the merger process. For instance, it is considering if it should remove its syariah compliance.
"For the time being, (there is) no change, but we will provide necessary updates," he said.
In response to unitholders' proposal that the Reit dispose its assets to recover value, he replied that the manager does not officially market the assets, but is open to offers at the right price. For instance, it is looking at potentially either divesting its asset at
1 Tuas Avenue 4 or leasing it to a tenant on a built-to-suit basis.
The Reit's distribution per unit (DPU) rose by 47.7 per cent to 2.29 Singapore cents for the six months ended Dec 31, 2020 - up from 1.55 cents a year ago. The distribution includes about 0.58 cent withheld from the first-half distribution.
Gross revenue was down
5.5 per cent to S$37.4 million for the second half of the year, from S$39.6 million a year ago, mainly due to lower contributions from 10 Changi South Street 2 following the termination of a master lease in H2 2019.
Net property income (NPI) fell 11.7 per cent on the year to S$23.8 million for the period, from S$26.9 million, impacted also by higher allowances of impairment loss on trade receiveables as some tenants asked to defer rental payments after being affected by Covid-19.
Including some S$6.1 million in distribution withheld from H1 2020, total distribution declared to unitholders rose 48.1 per cent year on year to S$24.1 million, from S$16.3 million. The distribution will be paid on Feb 26, after books close on Feb 1.
For the full year, DPU was
5.5 per cent lower at 2.76 Singapore cents, versus 2.92 cents a year ago, and distributable income fell 5.3 per cent to S$29.1 million. Gross revenue dipped 6.1 per cent to S$71.7 million, while NPI eased 13.5 per cent to S$44.6 million.
The manager also made provision for legal, professional and advisory fees of about S$2.7 million relating to the merger attempt with ESR-Reit, which Mr Han said the manager is working to negotiate lower. The question of who will bear the cost remains under negotiation.
Meanwhile, the prognosis in the industrial property landscape remains weak. Rental reversion for industrial properties is likely to remain negative for the year. Islandwide, industrial rents fell by 1.6 per cent year on year, as there is still an oversupply in the market.
The Reit had negative rental reversion of 0.2 per cent in H2 2020, while occupancy dipped to 76.5 per cent, from 77.3 per cent at end-June 2020.
The Reit has also seen an increased take-up at its new NTP+ mall at New Tech Park which is 77.3 per cent leased in phase one of its launch, as at end-Dec 2020. It is also in the final round of negotiations for the lease of 100 per cent of the food court space in phase two. The mall is on track for completion this quarter.
The manager also announced board additions Willy Shee and Yeo Wee Kiong as new independent non-executive directors, following the resignation in December 2020 of Ng Shin Ein as independent non-executive director.
Lim & Tan Securities in a Friday note said that the Reit is trading cheaply and still at a hefty discount from the consensus 12-month target price of S$0.48. It said: "We believe investors can look to accumulate Sabana Reit as after the failed merger with ESR-Reit, the manager continues to explore all viable options to create sustainable long-term value for unitholders."
Units of Sabana Reit added S$0.02 or 5.3 per cent to S$0.395.
TRENDING NOW

From legacy to launch: Francis Yeoh and Yeoh Pei Xien on family unity and YTL’s next‑gen ventures
Things to know about DBS’ incoming chairman Anthony Lim
Wealthy Indonesians snap up government bonds as yields near 8%: OCBC
From local AI partnerships to global opportunities: How MNCs help Singapore firms scale

