

Seatrium will have to wait longer to catch wind in sail
The company had to grapple with lawsuits as well as loss-making projects that it took on post-pandemic
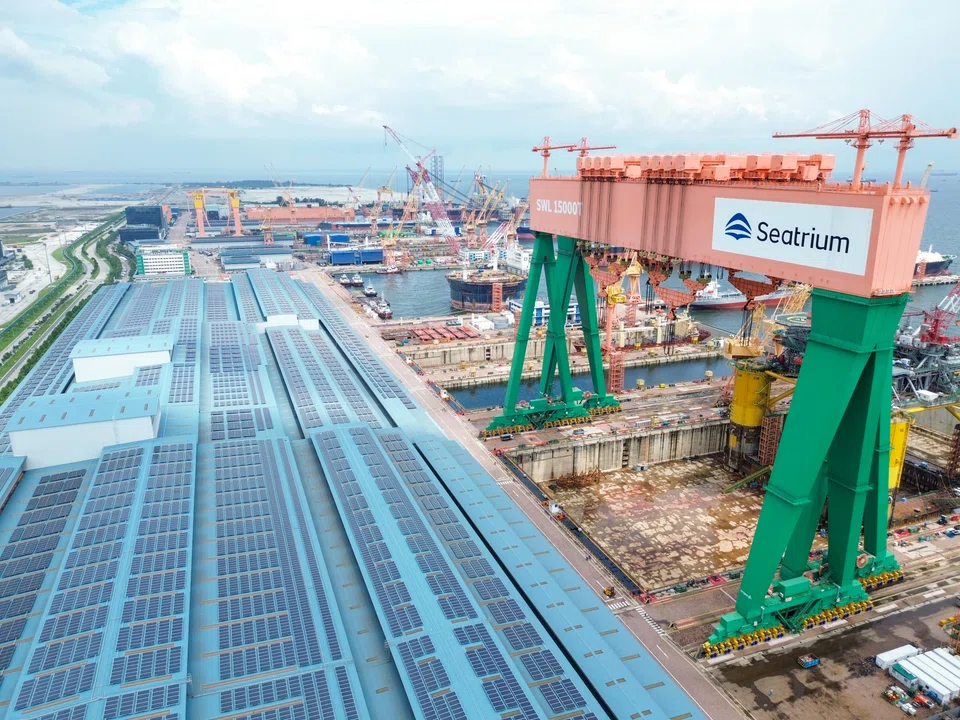
WHILE strong demand and tight supply have buoyed Singapore-listed maritime players in general, analysts believe it could take some time for offshore and marine giant Seatrium to recover its profitability.
Maybank analyst Jarick Seet pointed out that Seatrium – which was formed after the consolidation of Sembcorp Marine and Keppel Offshore and Marine – has been winning more contracts recently.
However, he noted that the company has had to grapple with lawsuits as well as loss-making projects that it took on post-pandemic.
“Those projects need to be cleared off first before their earnings can turn (for the better),” he said.
DBS analyst Ho Pei Hwa noted in a report on Mar 18 that the company’s share price has corrected from a high of about S$0.15 in Sep 2023 due to the cancellation of its offshore wind project, write-down uncertainty and delayed contract awards.
She noted that the company’s profitability targets seem less inspiring as the organisation said that it expects to generate S$1 billion in earnings before interest, taxes, depreciation and amortisation (Ebitda) by 2028.
Ho said this seems to be a given, since the company had already achieved S$600 million in Ebitda before provisions and write-downs in 2023.
“However, the worst should be behind us, with the finalisation of a massive write-down, conclusion of the Brazil Operation Car Wash case, and ... notification to proceed with the third TenneT project,” she said.
The company announced in February that it would work with its consortium partner, GE Vernova, to build a third offshore wind project for TenneT, the national electricity transmission system operator in the Netherlands.
On Apr 15, the company also announced that it was ordered to pay US$108 million in vendor termination and arbitration fees to MHWirth, a wholly owned subsidiary of US drilling services provider HMH.
She maintained a “buy” call on the company with a price target of S$0.15, with key catalysts being more order wins and earnings or margin expansion.
Singapore Exchange (SGX) market strategist Geoff Howie noted that Seatrium is also seeking shareholder approval to consolidate its shares and reduce volatility in its share price.
“With the minimum tick size at 0.1 cent... each minimum move in the stock is 1.25 per cent,” he said. “A move from S$0.09 to S$0.08 has been equivalent to an 11 per cent move.”
The company has received SGX approval for a 20 to one share consolidation, which will be subject to a vote at the company’s annual general meeting to be held on Apr 26.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Jacqueline Loh to step down as MAS deputy MD in senior leadership reshuffle

Why 1 in 2 young Singaporeans who said ‘no kids’ now say ‘yes please’: new study

Private home prices accelerate with 1.4% rise while HDB resale values dip further in Q3: flash data

