

Seatrium’s net order book swells to S$17.7 billion, but firm expects loss for FY2023
Mia Pei &
Uma Devi
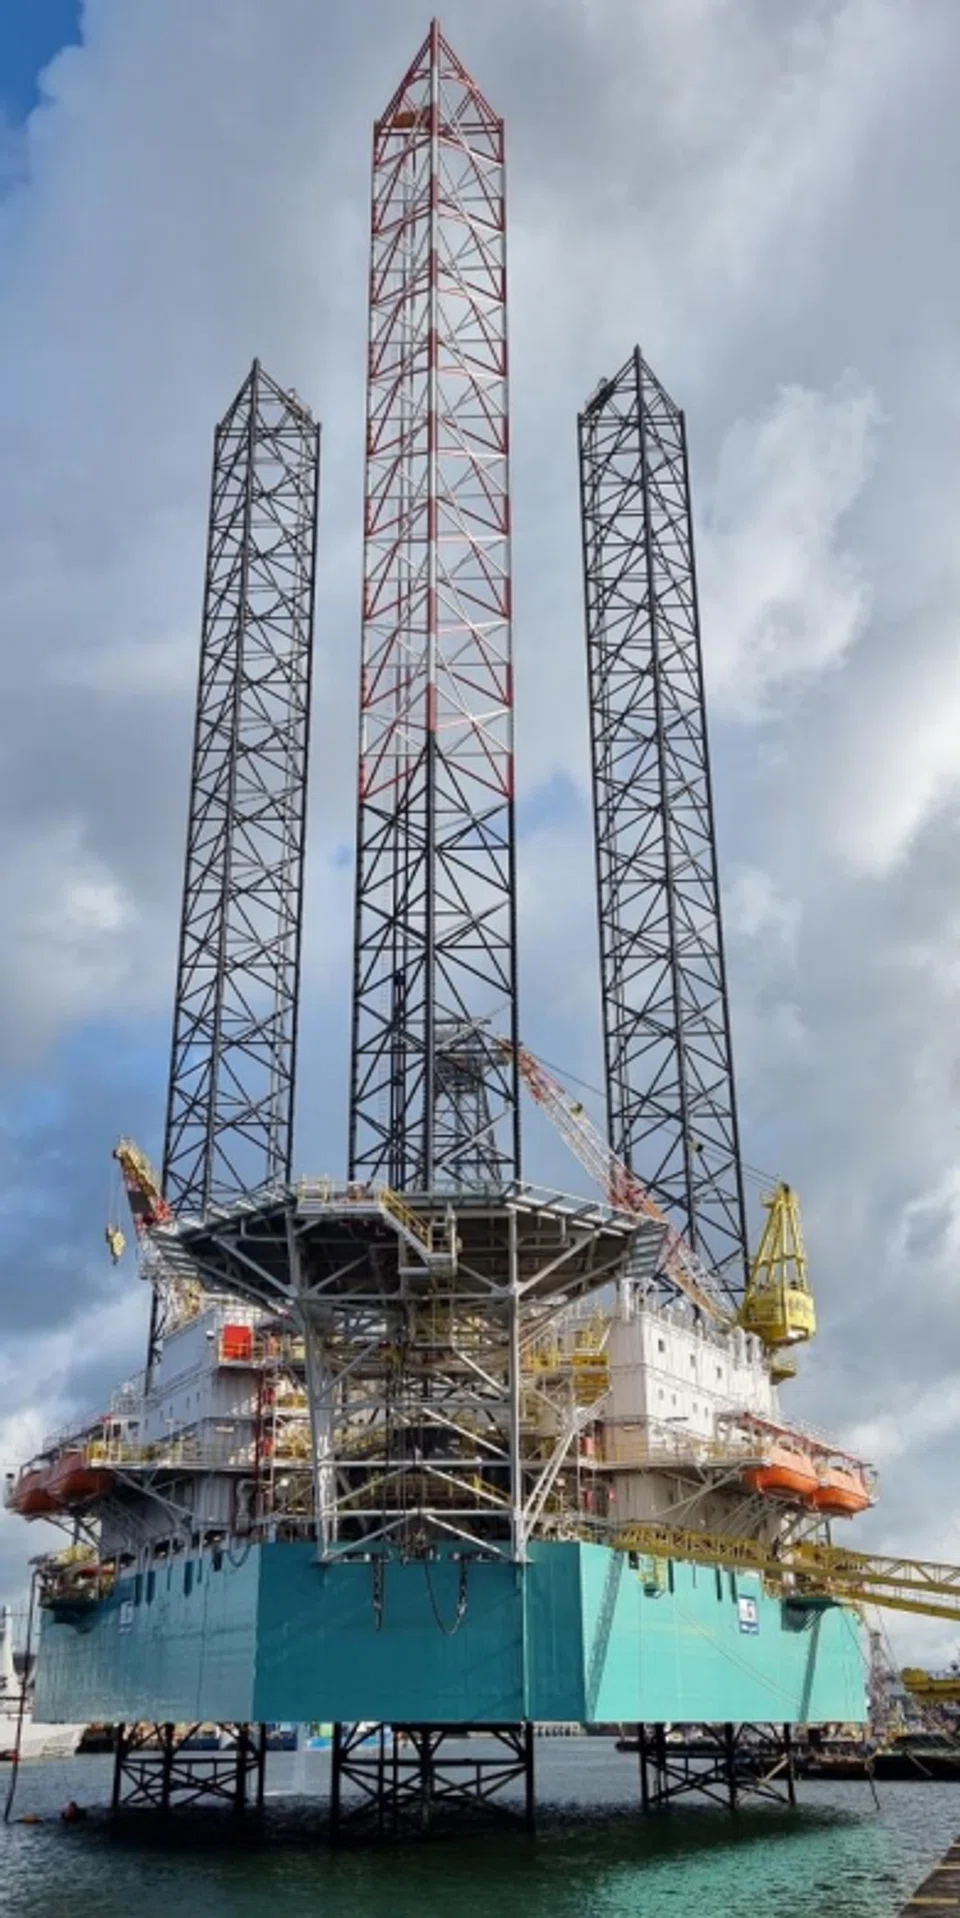
SEATRIUM on Wednesday (Nov 8) announced that it had secured new contract wins of S$4.3 billion for the nine-month period till end-September, which took its net order book to S$17.7 billion.
Projects related to renewables and green solutions contributed to about 40 per cent of the net order book, said the offshore and marine group in its third-quarter business update on Wednesday. The order book has 33 projects under execution till 2030, the company said in the update.
Seatrium is a product of the combination of Sembcorp Marine and Keppel Offshore and Marine in February 2023.
The group highlighted better operating cash flows for the three quarters, with a lower net gearing ratio of 0.15 times, compared with 0.17 times as at the end of June. Despite its operational and financial performance improving, the group noted that it expects a net loss for FY2023.
Speaking to reporters and analysts on a call on Wednesday, Seatrium chief executive Chris Ong declined to comment on the provisions that the group is expected to book in the second half of the year. But he said the group was reviewing the “relevance of all (its) assets” in an ongoing strategic review.
He also declined to comment on when the company would return to profitability.
However, he noted that Seatrium was the result of a “merger of two big companies that were emerging from the tailwinds” of a very prolonged downturn.
“We have a lot of challenges around execution, executing the order book well. But we are all very focused on looking at (Seatrium’s) Ebitda (earnings before interest, taxes, depreciation and amortisation), including the Ebitda margin, controlling costs, and getting the best operating leverage out of the two groups that have been merged.”
Asked to name Seatrium’s largest challenge in the near term, Ong cited two – margins, as well as securing new contracts.
He acknowledged that while there are enough projects in the pipeline for the group to chase, Seatrium needs to get its cost structure right to “maximise its margin”.
Globally, the environment of high inflation levels and elevated interest rates, along with geopolitical tensions, makes for an uncertain market, he said.
He added that Seatrium has a good cost database, as well as a database of suppliers and providers with a good track record.
Seatrium’s “milestone payment” system, which gives the group contractual rights to be paid for each milestone achieved in each project, also puts the group at an advantage relative to its peers, and buffers it against market volatility and unforeseen circumstances, he said.
In July, Seatrium reported a deeper net loss of S$264.4 million for the half year ended June, mainly due to project costs and merger-related provisions.
Ong said that as part of the group’s review of its capital structure, the management is looking at a “number of options”, including a share consolidation. “We’re actively looking at how we can consolidate our shares,” he said.
Asked when this would happen, he stressed that “many factors” were in play, and that the group would need to garner shareholder approval. “We will have to time it, and we don’t have a view on that right now. Suffice to say we are looking at it.”
Shares of Seatrium closed on Wednesday at S$0.109, down S$0.004 or 3.54 per cent.
TRENDING NOW

MAS allocates S$1.45 billion to five asset managers in third EQDP batch: Chee Hong Tat

‘My grandfather’s legacy’: Sherman Kwek lays out three-year plan for CDL to drive returns

‘How many will survive?’: Bubble fears arise as China’s humanoid robotics face reality check

CDL to hire dedicated CEO for fund management as it steps up push into private funds

