Sembcorp wastes little time on goal to unlock more value
Anita Gabriel
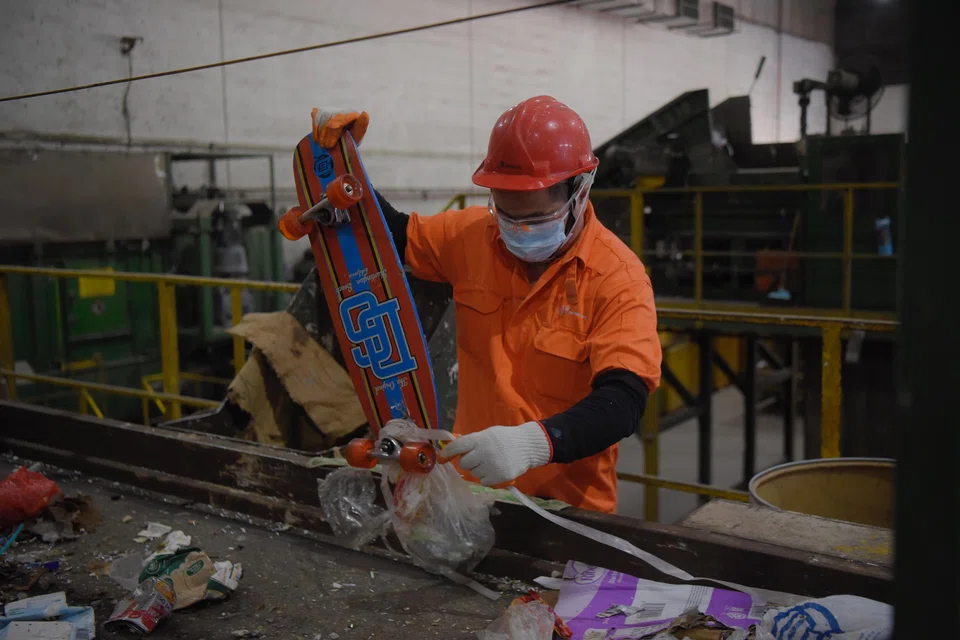
SEMBCORP Industries’ recent announcement that it is exploring the potential divestment of the waste management business and its energy-from-waste (EfW) plant appears to have sent investors into a tizzy.
More than a week ago, the company said it has hired HSBC as its financial adviser. More interestingly, it said that preliminary discussions with selected parties on the exercise have commenced.
Since the announcement on Jun 5, Sembcorp ’s stock has gained S$0.27 or more than 5 per cent from S$5.19 to S$5.46 on Monday (Jun 12), with daily average trading volume having perked up as well.
The company’s disclosure followed a Reuters report attributed to sources that US private equity group KKR & Co and Australia’s Macquarie Asset Management were among potential bidders for Sembcorp’s wholly-owned waste and recycling arm SembWaste.
The potential merger and acquisition play is likely to stir up excitement in Singapore’s waste management space nearly 10 months after Keppel Corp scooped up an 80 per cent chunk of SembWaste’s sector peer, 800 Super, for S$304 million.
This deal followed a 2019 buyout of 800 Super, then listed on the Catalist, by its controlling owners and founders the Lee family; the exercise which resulted in the privatisation of the company was financially backed by KKR.
Sembcorp’s intention to steer away from yet another legacy business may be easy to appreciate, as was its big move three years ago to ditch the flailing offshore and marine business, and demerge from Seatrium, then called Sembcorp Marine.
This is especially so as Sembcorp sharpens its lens on renewable energy, be it through acquisitions and organic growth.
It is also in line with the company’s asset-light goals, which is all the rage among many of Singapore’s behemoth firms as they seek to monetise assets, deleverage balance sheets and sweeten their ROE (return on equity) proposition to investors.
According to a report by CGS-CIMB Research’s analysts, the landscape for the waste management business has turned more competitive, while SembWaste’s market share has also shrunk over time.
SembWaste – a public waste collector under the National Environment Agency – covers only two of six sectors in Singapore. The City-Punggol contract expires in December 2027, while the Clementi-Bukit Merah contract expires in June 2028. It lost its grip over the Woodlands-Yishun sector to Alba W&H Smart City in December 2021.
CGS-CIMB estimates that the disposals of SembWaste and Sembcorp’s EfW plant could fetch around S$486 million to S$520 million, resulting in a divestment gain of S$225 million to S$250 million.
This is based on the assumption that SembWaste is valued at nine to 10 times its FY2022 enterprise multiples, and the EfW facility is valued at one time price-to-book value (book value estimated at S$180 million).
No doubt, the asset monetisation is key to Sembcorp’s goal to expand and redeploy capital where its heart is – clean energy.
All that attention has borne impressive results – at nearly 11 gigawatts (GW) in gross installed capacity as at end-March 2023, Sembcorp’s renewables portfolio has shot past its 2025 target of 10 GW. The investing fraternity is now keenly awaiting Sembcorp’s refreshed target.
There may be more good news afoot from elsewhere, too.
Sembcorp’s market capitalisation, which stands at around S$9.8 billion, qualifies the counter to be included in the MSCI SG following the next quarterly review set for Aug 10.
If or when these events unfold in the company’s favour, one can expect renewed excitement in Sembcorp’s stock, which over the first quarter was one of the Straits Times Index constituents that booked the highest net institutional inflow proportionate to quarter-end market capitalisation.