

Semiconductor companies poised for more broad-based recovery in 2025
Some Singapore-listed players, such as Frencken Group and Grand Venture Technology, may come out ahead and outperform as well, say market watchers
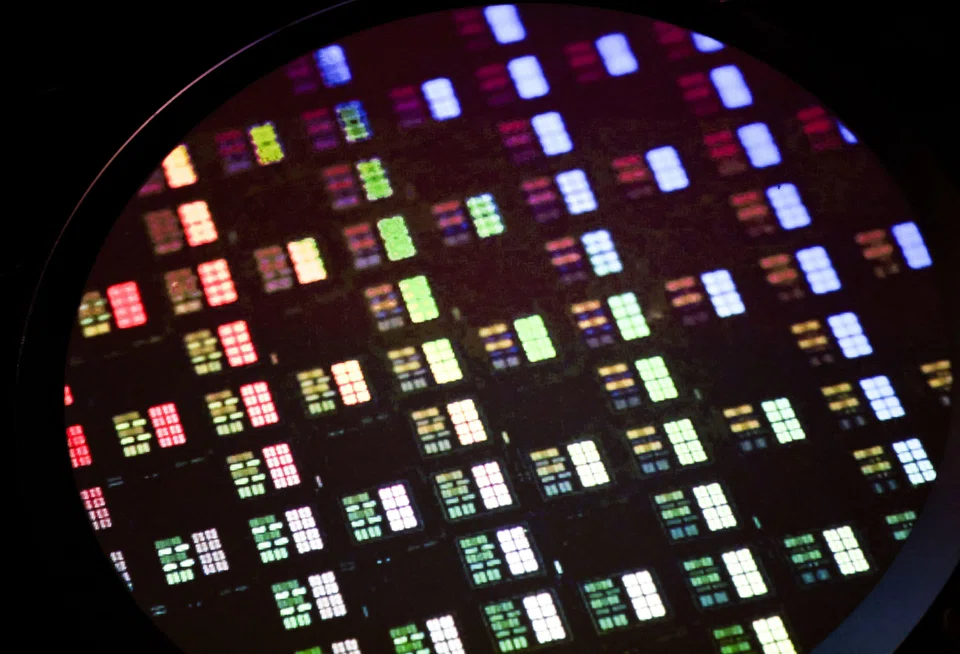
THE semiconductor industry saw a bumpy recovery in 2024, but a more broad-based rebound is expected in the coming year.
Some Singapore-listed players, such as Frencken Group and Grand Venture Technology (GVT), may come out ahead and outperform as well, according to market watchers.
Rajeev Rajput, senior principal analyst at Gartner, said that the semiconductor market has been recovering from a chip oversupply in 2023, which was caused by weak macroeconomic conditions and falling electronics production.
“The market is now in a recovery phase, although it is taking longer than anticipated due to certain markets like automotive and industrial,” he said, adding that there was not a “full-fledged” recovery in 2024.
Still, he believes that the worst is behind the industry.
“Momentum in 2024 was moderately restrained by weakness in automotive and industrial markets. However, in 2025, all markets will contribute towards growth,” he said.
Rajput noted that the industry is heading into a “super cycle” – semiconductor revenue is expected to record double-digit growth in 2024 and 2025, followed by high single-digit growth in 2026.
Similarly, Forrester senior analyst Alvin Nguyen said that demand from specific markets, such as data centres, outstrips supply as corporates move to deploy artificial intelligence (AI) solutions that demand more computing power.
“This is driving the buildout of new semiconductor fabrication plants with higher end processes, as well as upgrading existing plants,” he said.
In 2025, he expects the AI, automotive and communications sectors to drive demand for semiconductors in 2025.
But Nguyen warned that there are risks to the AI growth story.
Semiconductor chip demand could be hit if AI demand slows, especially if AI chip production cannot meet demand and enterprises decide to look elsewhere to make returns on their investments.
A slowdown in the development of AI models or geopolitical factors that lead to export controls and data sovereignty laws may also restrict or complicate the acquisition of semiconductors for AI development and deployment, he said.
Bank of America Securities Asia technology and memory analyst Simon Woo noted that while the industry is in an upcycle, some deceleration of growth and softening in chip pricing momentum has been observed, even if there is no downturn yet.
“There is a decoupled trend seen among the chipmakers and also among the AI and non-AI chips. For example, AI-related chipmakers’ better earnings momentum compared to the companies which have low AI chip sales exposure,” he said.
Local winners
As the sector progresses in its current upcycle, analysts believe that there are some bright spots that investors could potentially pay closer attention to.
While it has missed estimates this year, CGS International and Maybank remain bullish on Frencken.
The company serves semiconductor customers with complex components that go into processes such as wafer fabrication and die bonding.
After the company posted its third-quarter earnings for the period ended Sep 30, 2024, CGS International’s William Tng noted that the company’s nine-month revenue was in line with his expectations, even if they fell short of Bloomberg’s consensus forecast. Revenue for the nine months grew 6.7 per cent year on year to S$571.3 million.
At its earnings briefing, the company’s management cited uneven recovery within the semiconductor segment as an issue that has delayed timing in demand in some sub-segments.
Still, Tng said that he expects order recovery among the company’s semiconductor customers to remain intact, even if the company’s customers are delaying order deliveries.
He noted that while about 49 per cent of the company’s FY23 revenue originated from three key customers, it also has customers in the healthcare, industry and life sciences segments. The company is also actively recruiting new customers.
Similarly, Maybank analyst Jarick Seet said that while a ramp up in semiconductor orders is only expected in the second to third quarter of next year, Frencken remains his top pick in the Singapore tech sector.
He added that while the majority of Frencken’s local peers are suffering from significant declines in net profit after tax (NPAT), Frencken’s NPAT is expected to grow strongly in the next few years.
“Potential trade restrictions between major powers the US and China will continue to impact global demand but we believe that the long-term growth story is intact,” he said.
Meanwhile, DBS analysts Ling Lee Keng and Amanda Tan are bullish about GVT’s prospects.
In its operational update for the three months ended Sep 30, 2024, the company posted a 51.3 per cent year-on-year increase in net profit after tax to S$2 million, on a 52.8 per cent increase in revenue to S$43.5 million over the same period.
“The semiconductor segment which comprises slightly more than half of group revenue, soared 50.8 per cent year on year on improving demand from key customers as GVT won new programmes and increased its wallet share,” the analysts said.
They added that the company is a beneficiary of the AI boom.
“Tailwinds in AI benefit GVT through the semiconductor value chain with GVT involved in through-silicon via (TSV) deposition tools in the front-end, and packaging technologies such as thermal compression bonding and hybrid bonding for high-bandwidth memory as well as testers in the back end,” they said.
TSVs are used to build 3D semiconductor packages that contain multiple dies. Such chips have risen in popularity as a means of packing more processing power onto a single semiconductor package, which is necessary as AI demands ever more processing power.
High-bandwidth memory is also used in graphics processing units that are used to train AI models. This sort of memory is faster at feeding data to processing units, which can make training faster and more efficient.
“Another encouraging trend for GVT is the China plus one supply chain diversification which is expected to gain momentum under Trump’s presidency as they can support supply chains that have moved to Asia,” the analysts said.






