

SGX listcos’ Q3 profits fall 6.8%; tech, Reits expected to lead recovery in 2024
THE earnings of companies listed on the Singapore Exchange (SGX) fell for the third quarter of 2023 ended September amid high interest rates, persistent inflation and an economic slowdown in China.
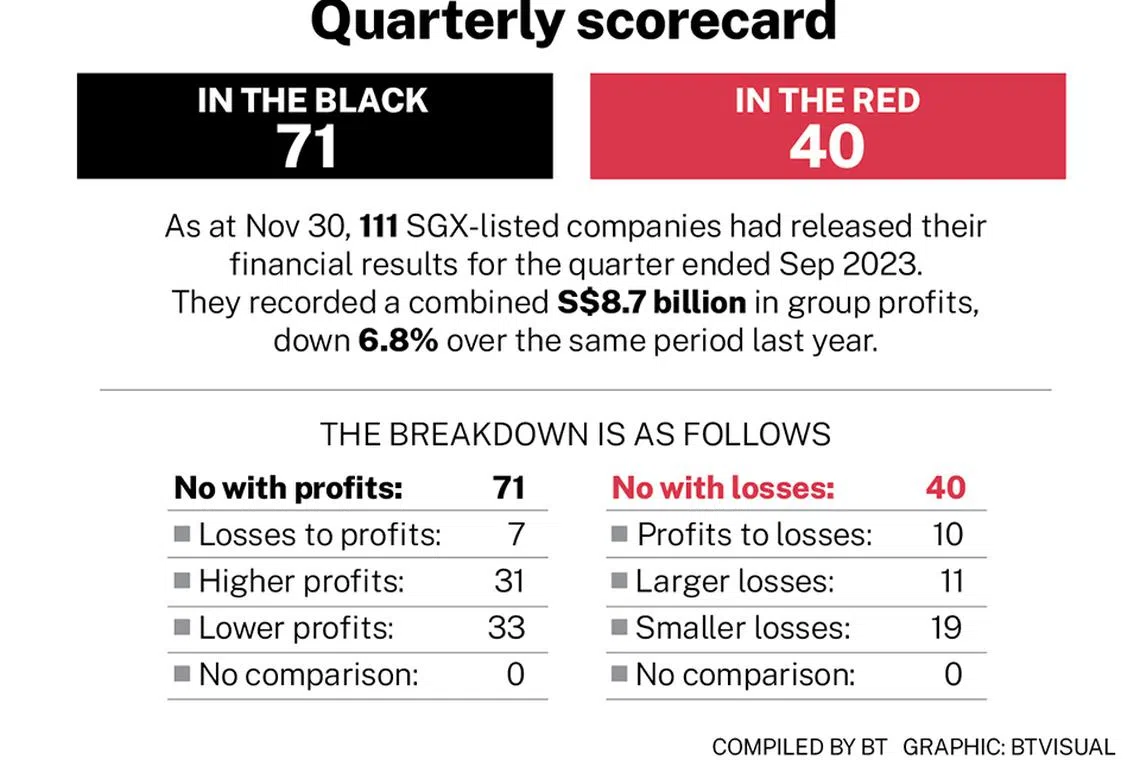
A compilation of results by The Business Times as at Nov 30 showed that the aggregate profits of the 111 companies that had released their quarterly financial results or updates for the quarter stood at S$8.7 billion, down 6.8 per cent from the corresponding period last year.
While analysts expected earnings for Q4 to remain weak for most sectors, they were optimistic that some sectors such as technology and real estate investment trusts (Reits) would see some recovery in 2024.
Of the 111 companies that released their financial results, 71 were profitable for the quarter to September, while 40 were in the red.
Of the 71 profitable companies, 33 posted a smaller bottom line. Another 31 managed to improve their earnings, and seven swung back into profitability from a loss in the year-ago period.
Nineteen of the companies in the red managed to trim their losses, but 11 had their losses balloon, and 10 became loss-making during the quarter.
The banking trio – DBS , UOB and OCBC – led the pack in the earnings tally, with national carrier Singapore Airlines (SIA) just behind.
Local Reits Mapletree Pan Asia Commercial Trust , Mapletree Logistics Trust and Mapletree Industrial Trust also ranked among the top companies in terms of net profit recorded for the quarter ended September.
At the bottom of the pack was dual-listed Top Glove . The glove manufacturer posted a net loss of S$134.7 million for its Q4, versus a net loss of S$18.3 million the previous year, due to lower revenue and a RM388.5 million (S$111.5 million) impairment over the quarter.
Headwinds expected
Peggy Mak, research manager at Phillip Securities Research, said that apart from banks and airlines, most companies reported weaker year-on-year net profit.
This was particularly so for companies with exposure to China, such as Wilmar International , added Mak. The commodity group’s net profit for Q3 fell 59 per cent year on year.
Most companies were also showing “some slippage” in their margins as high interest rates and inflation persisted, said Thilan Wickramasinghe, head of research for Singapore at Maybank Securities.
That said, overall margins were still significantly higher than what they were the previous year, he noted.
Analysts agreed that the banking sector had remained resilient amid an elevated interest rate environment.
Mak noted that net profit of the local banks had increased year on year due to a higher net interest margin (NIM) and fee income from credit cards and wealth management.
On the other hand, their quarter-on-quarter performance was mixed, as loan growth fell and higher specific provisions were made in the quarter to account for collateral revaluation, added Mak.
Meanwhile, despite SIA’s strong earnings showing as a result of high passenger loads in Q3, Mak said the national carrier could see lower yield in future.
She noted that the airline’s yield had begun to fall as lower-yielding budget flights take on a bigger share of the increase in passenger load.
“We expect airfare to subside from the current high level, as competition seeps in from other carriers adding capacity aggressively,” said Mak.
Reits rebound on the horizon
Analysts were of the view that Reits’ earnings in the latest quarter had been affected by higher interest costs.
DBS analyst Foo Fang Boon said that Reits had their fair share of downwards earning revision in Q3 due to higher interest costs.
Similarly, Mak said, the Q3 distribution for Reits was “broadly lower” and also affected by the lower income from foreign assets due to the strong Singapore dollar.
Within the sector, hospitality Reits generally reported a higher net property income while retail Reits rebounded in gross revenue, said Mak.
Nevertheless, Foo said there was “cautious optimism” that the Reit sector will improve in 2024 due to developments such as the US Federal Reserve’s pivot towards a rate pause.
The strong line-up of meetings, incentives, conferences, and exhibitions events in the first quarter of 2024 and the return of international travellers should also pave the way for hospitality Reits to deliver positive year-on-year growth, he added.
He expressed similar optimism for the tech sector despite the slowdown in the industry. He noted that the purchasing managers’ index (PMI) for electronics in November this year had expanded.
The latest PMI for electronics stood at 49.9, a 0.1-point improvement from the previous month. The figure is shy of the 50-point threshold, which indicates a growth in the industry.
Mak said that the performance of the tech sector mirrored that of the US semiconductor players. Orders in Q3 were subdued as customers’ inventory destocking persisted.
Nevertheless, Mak said, the tech sector appeared to be making a broad-based recovery, and inventory restocking might happen in Q2 of 2024.
“This should benefit the local companies such as AEM , Frencken and Grand Venture , which support the equipment makers,” said Mak.
*Amendment note: An earlier version of the graphic in the story stated that SGX-listed companies recorded a combined S$8.7 million in group profits, up 6.8 per cent over the same period last year. It is in fact a combined S$8.7 billion in group profits, which is down 6.8 per cent over the same period last year.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Income Insurance appoints former Manulife Singapore top man as new CEO

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

