

Should CICT and MCT swap some of their local offices for properties in London?
SUNTEC Real Estate Investment Trust (Suntec Reit) has been busy buying office assets in the United Kingdom.
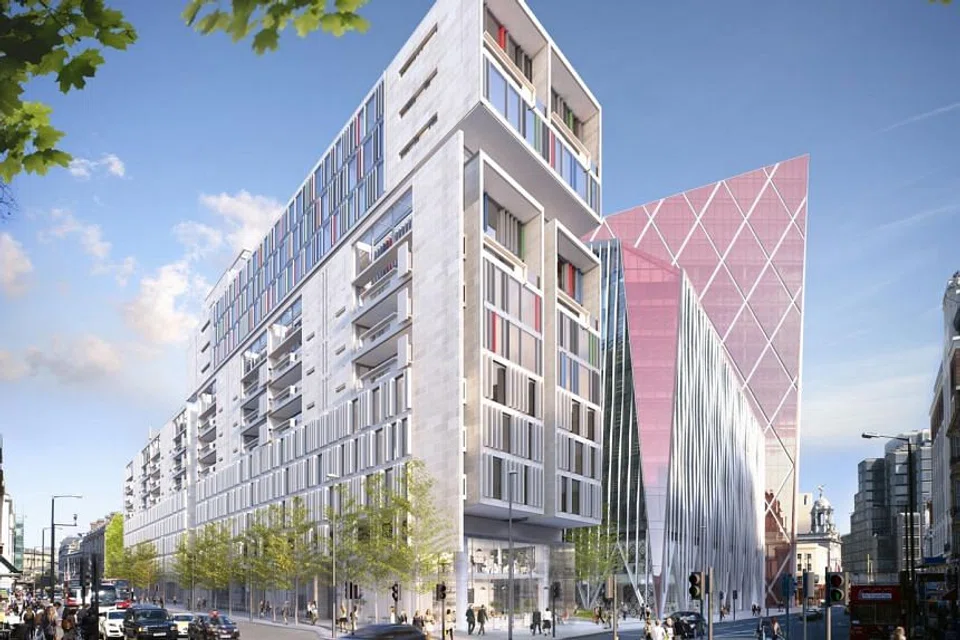
On June 29, the trust's manager announced the purchase of a Grade A office building with ancillary retail, The Minster Building, located in the City of London for an agreed property value of £353 million (S$667.2 million).
And in December, Suntec Reit completed its maiden acquisition in London of a 50 per cent interest in two Grade A office buildings with ancillary retail for an agreed property value of £430.6 million. Dubbed the Nova Properties, they are situated opposite London's Victoria station.
Meanwhile, Suntec Reit has been reducing its exposure to the Singapore office segment.
In June, the trust announced divestments of a 30 per cent stake in 9 Penang Road at an agreed property value of S$295.5 million and 78,491 sq ft of Suntec City Office strata units at an agreed property value of S$197 million. Proceeds from these sales will help fund the purchase of The Minster Building.
Suntec Reit's moves to increase its exposure in London and lower it in Singapore make sense from a numbers perspective. Unitholders may also be pleased that the trust's foray into London has not involved any new issue of units.
The office spaces at Suntec City are being sold at a net property income (NPI) yield of 3.1 per cent for a divestment gain of S$13.9 million.
The stake at 9 Penang Road is being sold at NPI yield of 3.3 per cent on a stabilised basis. Suntec Reit is part of the joint venture that redeveloped 9 Penang Road, where Swiss Bank UBS has fully leased both office towers. The sale by the trust is at a premium of 30.3 per cent to the total development cost of S$756.0 million, and it will realise a divestment gain of S$66.5 million.
As for The Minster Building, the NPI yield is 4.5 per cent. The pro forma financial effect of acquiring The Minster Building is an uplift to Suntec Reit's distribution per unit in FY2020 of 3.6 per cent, assuming the acquisition was completed on Jan 1, 2020 and funded with proceeds from the 9 Penang Road and Suntec City divestments, Sterling-denominated loans and perpetual securities.
The Minster Building sits on a land lease with 968 years remaining and has a weighted average lease expiry of 12.3 years. In contrast, 9 Penang Road and Suntec City Office sit on much shorter 99-year land leases that commenced in 2016 and 1989, respectively.
The Nova Properties were acquired at an NPI yield of around 4.6 per cent and sit on a land lease with about 1,041 years outstanding.
Debt costs in the UK and Singapore are fairly comparable. The borrowing costs of Elite Commercial Reit, which owns only UK assets, are 1.9 per cent per annum. Frasers Centrepoint Trust, which owns only Singapore assets, has borrowing costs of 2.2 per cent per annum.
The risk-free rate as represented by 10-year government bond yields is lower for the UK compared with Singapore - at around 0.7 per cent and 1.5 per cent per annum, respectively.
Compelling proposition
By diversifying into London, Suntec Reit is therefore securing better entry yields, a better yield spread to the risk-free rate, and property with a longer outstanding land lease tenure but still within an established international business city - a compelling proposition.
Reit investors are typically hungry for yield. Suntec Reit's swapping of some Singapore assets for London assets appears to be the right call.
Post these latest transactions, Singapore will still account for just over 70 per cent of Suntec Reit's portfolio value. The manager has targeted for overseas assets to account for 30 to 40 per cent of portfolio value.
How will this shift affect investors' opinions of Suntec Reit?
Investors have historically showed a preference for commercial Reits that are Singapore-centric. CapitaLand Integrated Commercial Trust (CICT) and Mapletree Commercial Trust (MCT) trade at premiums to their book values.
But high-quality office and retail assets in Singapore are tightly held, and yields on transacted prices are low.
Should CICT and MCT follow the lead of Suntec Reit and increase their overseas exposure to give investors better returns?
These Reits can afford to make large overseas acquisitions while still keeping a strong Singapore flavour. For CICT, 96 per cent of a portfolio valued at S$22.3 billion as at end-2020 was made up of Singapore assets. Another 4 per cent came from German assets. MCT's portfolio of assets worth S$8.7 billion as at March 31, 2021 comprises solely Singapore assets.
Investors who have been drawn to CICT and MCT for exposure to high-quality Singapore commercial assets may not mind that these trusts make some yield-accretive acquisitions of high-quality overseas assets.
Growing a presence in the vibrant business hub of London to add geographic diversification, bump up distribution to unitholders and lengthen the tenure of land lease outstanding can be a strategy worth pursuing for CICT and MCT.
TRENDING NOW

OCBC Q3 profit rises 3% to S$2.04 billion, slightly above expectations
Stocks to watch: OCBC, IHH Healthcare, FLCT, SingPost, Koh Brothers Eco Engineering

From legacy to launch: Francis Yeoh and Yeoh Pei Xien on family unity and YTL’s next‑gen ventures

Wealthy Indonesians snap up government bonds as yields near 8%: OCBC

