

Should investors sell SIA's soaring shares?
Investors who choose to sell should do so because SIA has terrible fundamentals rather than because its stock has surged
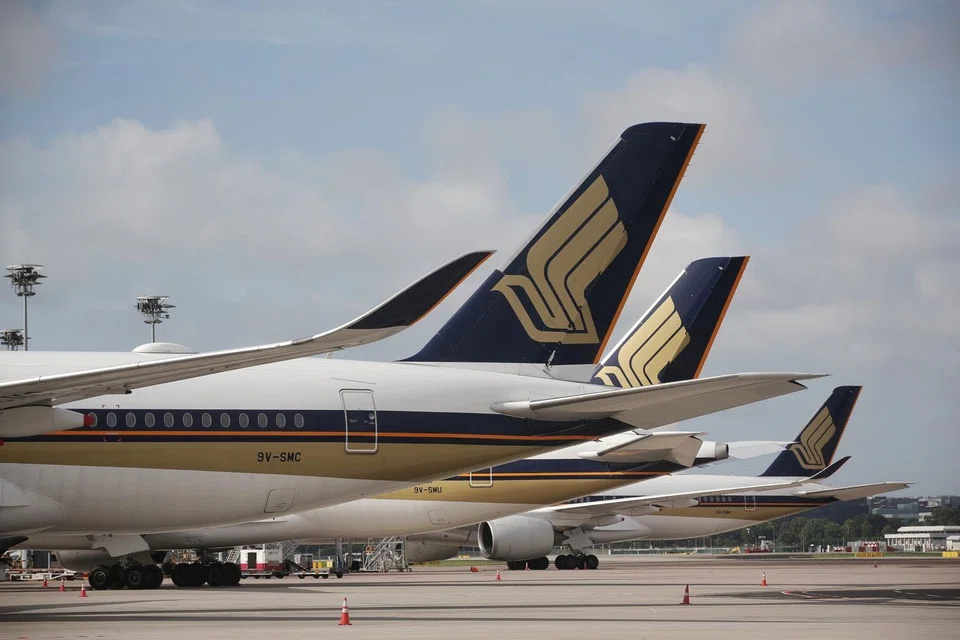
CUT your losses short and let your winners run, goes the old market adage. But what if the stock in question is Singapore Airlines (SIA)?
Since the end of October last year, shares in SIA have rocketed some 59 per cent, sharply outperforming the Straits Times Index (STI), which climbed about 32 per cent.
On a year-to-date basis, SIA is up more than 26 per cent, making it the second best performing component stock of the STI, behind Yangzijiang Shipbuilding (which is up more than 36 per cent) and ahead of Hongkong Land (which is up more than 21 per cent). The STI was up almost 13 per cent during the same period.
Yet, SIA's steep ascent is beginning to make some analysts queasy. This past week, UOB Kay Hian (UOBKH) put a "sell" recommendation on the stock with a price target of S$4.40. SIA closed at S$5.40 on Friday.
The basis of UOB Kay Hian's call appears to simply be that SIA has run up too much.
SIA has outperformed more than just the STI. It has also climbed at a faster pace than the Jets exchange-traded fund (ETF), noted UOBKH in a report. The Jets ETF - which holds stocks such as Southwest Airlines, Delta Air Lines and Air Canada - is up more than 18 per cent since the beginning of the year.
On top of that, despite all optimism in the market about an imminent recovery for the airline sector, the reality on the ground is much more sober.
The UOBKH report referenced an analysis by the International Air Transport Association (Iata) that showed the airline industry likely to remain cash negative throughout 2021. Iata had previously expected airlines to turn cash positive by Q4 2021.
"At the industry level, airlines are now not expected to be cash positive until 2022," Iata noted in a press release in February. "Estimates for cash burn in 2021 have ballooned to the US$75 billion to US$95 billion range, from a previously anticipated US$48 billion."
In short, the global rollout of vaccination programmes will probably not result in governments around the world agreeing to as extensive a re-opening of international borders as SIA's share price seems to be indicating.
According to the UOBKH report, SIA is now trading at 1.6 times its estimated FY2022 book value or about a 70 per cent premium to its pre-Covid-19 levels.
Anticipated recovery
If mere overvaluation were reason enough for investors to sell a stock, however, the whole market would have collapsed by now.
Two weeks ago, shortly after the S&P 500 index sailed past the 4,000 mark for the first time, this column noted that US stocks were trading at nearly 22 times forward earnings. The S&P 500 traded at an average of about 18 times forward earnings over the last five years, and some 16 times forward earnings over the last 10 years.
With an unfolding recovery in global economic activity spurring corporate earnings, and interest rates still at extremely low levels, investors are unlikely to abandon the stock market any time soon.
Ironically, airlines have been such great outperformers recently because they were hit so hard when the pandemic started and are now viewed as having a long runway of growth.
Even if the volume of international flights takes longer than expected to recover, news flow about "vaccine passports" and "travel bubbles" is likely to maintain a sense of anticipation in the market.
Meanwhile, SIA's financial and operational numbers suggest the group is steadily - albeit very slowly - rebuilding its business.
For March 2021, the SIA group's airlines carried just over 100,000 passengers. That is a far cry from the more than 3 million they regularly carried every month before Covid-19, but it was still the highest number of passengers for any month since March 2020 when they carried almost 1.1 million passengers.
Similarly, the group's revenue passenger-kilometres in March 2021 of 463.9 million was the highest since the 4.75 billion it reported for March 2020 when it was already cutting back its flights. Prior to Covid-19, SIA's monthly revenue passenger-km often exceeded 13 billion.
On the capacity front, SIA group's airlines had 3.62 billion available seat-km in March 2021. This was more than any previous month since March 2020, when it had nearly 8.3 billion available seat-km, but much less than the approximately 15 billion available seat-km it regularly reported every month before Covid-19.
Temasek support
SIA is still deeply in the red though. For the nine months to Dec 31, it reported a 78.9 per cent year-on-year decline in revenue to just S$2.7 billion. SIA posted a loss of S$3.6 billion for the 9-month period, compared to earnings of S$520 million for the same period the previous year.
Until there is a more significant recovery in traffic, UOBKH said, SIA could suffer a monthly operating cash burn of as much as S$250 million. SIA has also indicated that its capital expenditure will come in at S$4 billion for FY2022, and S$4.5 billion for FY2023.
Assuming the capex is distributed evenly, SIA will burn at least S$3.8 billion of cash, or some 30 per cent of its liquid funds, by the end of September, UOBKH said.
With the backing of Temasek Holdings, SIA is unlikely to face difficulty raising funds. Last year, SIA raised S$8.8 billion through rights issues of new shares and 10-year mandatory convertible bonds (MCBs). Temasek took up most of the MCBs because of poor demand.
Last month, SIA noted that it has used some S$8.2 billion of the proceeds of the rights issues. Since the beginning of FY2021, however, it has also boosted its liquidity through S$2.1 billion worth of loans secured against its aircraft, S$2 billion worth of convertible bond and note issues, and additional bank credit lines.
SIA also has an option to issue a further S$6.2 billion worth of MCBs. Interestingly, the first tranche of MCBs, which traded more than 10 per cent below par last year, are now trading 2 per cent above par.
Real reason to sell
Of course, all these MCBs and convertible bonds will weigh on the long-term return of SIA's shares. This brings me to the real reason investors might want to sell the stock.
Prior to Covid-19, SIA managed to deliver a much admired standard of service as well as report positive earnings every full financial year and pay a dividend.
Yet, SIA faces famously cutthroat competition on its long-haul and short-haul routes. Fuel costs are volatile and consume about one-third of its revenues. SIA also has to constantly invest in new aircraft to maintain its market leading position.
Over the 10-year period to FY2019, before Covid-19 struck, SIA's return on equity averaged just 4.6 per cent. During the same period, shares in SIA delivered a total return of minus 13.3 per cent. The STI returned 54.3 per cent.
Investors who want to sell SIA right now should do so because the company has terrible investment fundamentals, rather than simply because its shares have surged.
- For more analysis and insight on market trends and corporate issues, listen to the Mark To Market podcast at bt.sg/mark2mkt
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Cliff Tan has 7 million followers and a 4-month waitlist. Why won’t he expand his business?

Could stablecoins be the future of money?

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

