

Should Isetan have disclosed offer for its Wisma Atria stake?
Anita Gabriel
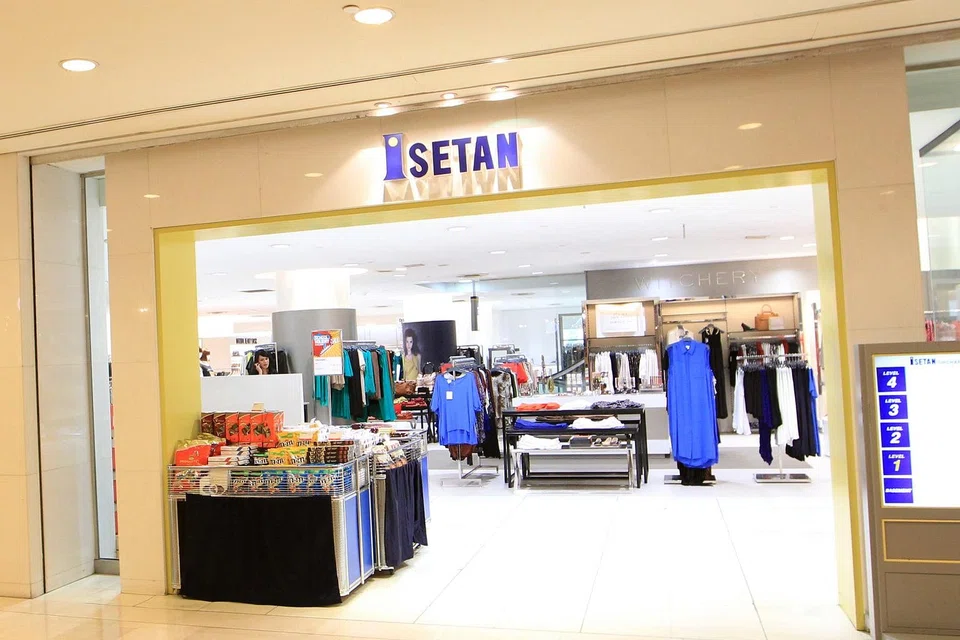
ISETAN Singapore may be facing a testing time, like many traditional retailers, as a result of changing shopping habits and brutal online competition but that's no reason to be cagey with its shareholders.
Last month, the Japanese department store operator disclosed that a fire occurred at its flagship Isetan Scotts at the Shaw House in the morning of Sept 19. The Singapore-listed retailer said there were no injuries and damage was "limited" and hence, it was unlikely to materially impact the firm's FY2019 showing. The announcement was issued in the evening on the day of the incident.
Contrast this rapid disclosure to Isetan's reticence over a more consequential matter - the possible sale of a key asset.
On Sept 10, The Business Times reported that the manager of YTL's Starhill Global Reit (SGReit) had issued a letter of intent to Isetan more than a month earlier to acquire the latter's share of Wisma Atria, a prime leasehold property in the heart of Orchard Road. SGReit owns about 74 per cent of Wisma Atria's total share value of strata lots.
Isetan shares have stayed in stratospheric levels this year, shrugging off the general market weakness, as investors bet on a potential asset sale to unlock value in the company. Naturally, news that there was indeed a bid on the table sent Isetan shares up by nearly 10 per cent to S$5.24 - storming past its 52-week high of S$4.80 - on Sept 10, which led the firm to call for a trading halt.
That same evening, Isetan issued a statement that it had (indeed) received a non-binding expression of interest (EOI) from SGreit's manager to acquire its investment property at Wisma Atria. There was no mention of when the EOI was received, if it had a lapse date or any other details related to an offer.
Sources told BT that YTL Starhill Global Reit Management has signalled that it is prepared to offer more than S$290.7 million - the fair value of Isetan's investment stake in Wisma Atria as at the end of 2018 as determined by an independent valuer. This is notably higher than its market capitalisation that currently stands at S$200 million.
Isetan said it was reviewing the EOI contents and evaluating whether the proposal was in line with its long-term strategy, adding that it hasn't entered into any definitive decision or agreement.
This vague statement did not go down well with some shareholders, who claimed it was not the first time Isetan has chosen reticence over candour.
In its annual general meeting in April, Isetan directors were asked by shareholders why the company wasn't contemplating a sale of Wisma Atria, the proceeds of which could potentially be returned to shareholders by way of a capital distribution. Shareholders were told that "major transactions" were unable to proceed without shareholders' approval.
The cryptic answer suggested that Isetan's parent in Japan, Isetan Mitsukoshi, was intent on guarding its share of Wisma Atria, wanting instead to better the returns from the "strategic asset". How exactly it plans to do this hasn't yet been articulated.
But one thing is clear - the Japanese retailer cannot afford to sit on its hands, not least because the property has 42 years left on the lease. Further, a slowing Singapore economy could lead to a fall in discretionary consumer spending and hurt high-end malls such as Wisma Atria in the Orchard shopping belt.
These factors risk eroding potential value accretion for the company.
It's hard to read into Isetan's reserved posture: whether it has to do with the conventional Japanese culture or if it belies something deeper - perhaps, a disinclination for an outright sale of Wisma Atria or that it may be holding out for a sweeter offer.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

If AI has a one-in-five chance of destroying us, what do we do with the remaining four?

