

SIA expected to unveil better Q4 results
Analysts see boost to profits from reduced fuel costs and lower hedging losses
Nisha Ramchandani
Singapore
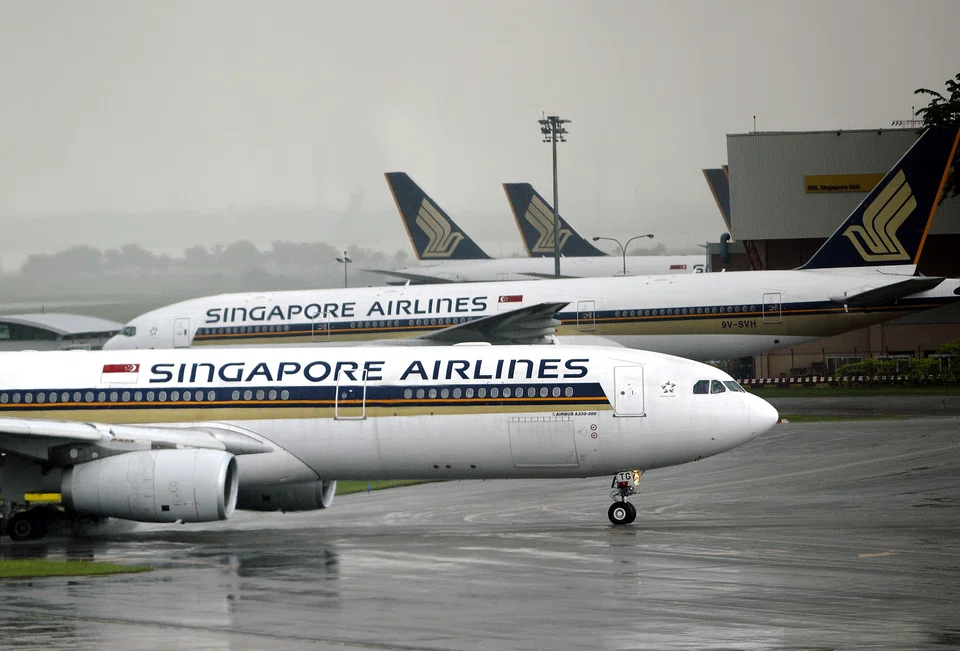
A BETTER performance could be on the cards for Singapore Airlines (SIA), when it reports its fourth-quarter and full-year results on Thursday, aided in part by lower fuel costs and lower hedging losses.
UOB Kay Hian director of Asia transport research, K Ajith, expects SIA to marginally pip the consensus FY2015 net profit estimate of S$382 million. "Key drivers are lower fuel prices, lower fuel hedging losses and improved cargo profitability arising from higher utilisation," he said, predicting a final dividend of 17 Singapore cents for the financial year. But he flagged potential "surprises" from foreign exchange-related losses on aircraft disposal.
Meanwhile, Maybank Kim Eng analyst Mohshin Aziz expects a core net profit of S$165.7 million for the fourth quarter, compared to a core net loss of S$0.9 million a year ago. For the full year, Mr Aziz is projecting a core net profit of nearly S$448 million, versus S$397.8 million in FY2014.
"SIA's FY15 operating statistics were in line with our expectations," he said in a report on Tuesday. "System traffic growth was flat year on year and load factor decreased 0.4 percentage point year on year to 67.7 per cent. This is a respectable performance in light of the challenging market conditions."
While fuel hedging losses are expected in the fourth quarter, the quantum is likely to be lower compared to Q3 FY2015, analysts said. SIA had revealed previously that it had hedged about 65 per cent of its fuel needs at US$116 per barrel until end-March 2015, which saw it chalking up hedging losses in Q3 FY2015 despite the slump in jet fuel prices.
However, SIA's subsidiary Tiger Airways could also pose a slight drag on earnings at the non-operating level due to substantial provisions, noted Mr Ajith. Budget carrier Tiger last week reported a smaller net loss of S$18.82 million for the fiscal fourth-quarter on the back of its turnaround efforts, which included pulling the plug on loss-making operations in Australia, the Philippines and Indonesia, as well as rationalising Tigerair Singapore's network. However, its full-year net loss swelled 18.5 per cent to S$264.23 million.
Still, CAPA-Centre for Aviation said in a recent report that Tigerair Singapore should be able to return to profitability in FY2016.
"The (Tiger) group should also be back in the black as all the overseas joint ventures have been sold or closed," CAPA added. "Profits will likely be modest and come at the expense of market share."
For the current financial year ending March 31, 2016, SIA's loads are likely to remain flat as the group manages capacity and as the gradual introduction of its premium economy product from August impacts capacity as well.
"Yields are a tougher call," Mr Ajith told BT. "The industry is very dynamic and it appears that the Middle Eastern carriers are becoming more aggressive."
But premium economy seats are expected to see better yields vis-a-vis economy seats of up to 20-30 per cent higher.
Meanwhile, Maybank's Mr Aziz is optimistic that FY2016 will be positive for SIA "given the healthy global demand, recovering cargo market, the benefits of lower jet fuel prices and better performances of its subsidiaries".
Shares in SIA closed at S$11.65 on Tuesday, down 19 cents.
TRENDING NOW

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

URA to review guidelines on floor space to give developers more design flexibility: Chee Hong Tat

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Can a first-time homebuyer couple earning S$18,000 a month afford a new EC unit?

