

SIA sets S$850m convertible bonds coupon at 1.625%
Five-year bonds upsized due to oversubscription; initial conversion price is S$5.743 for each new ordinary share
Singapore
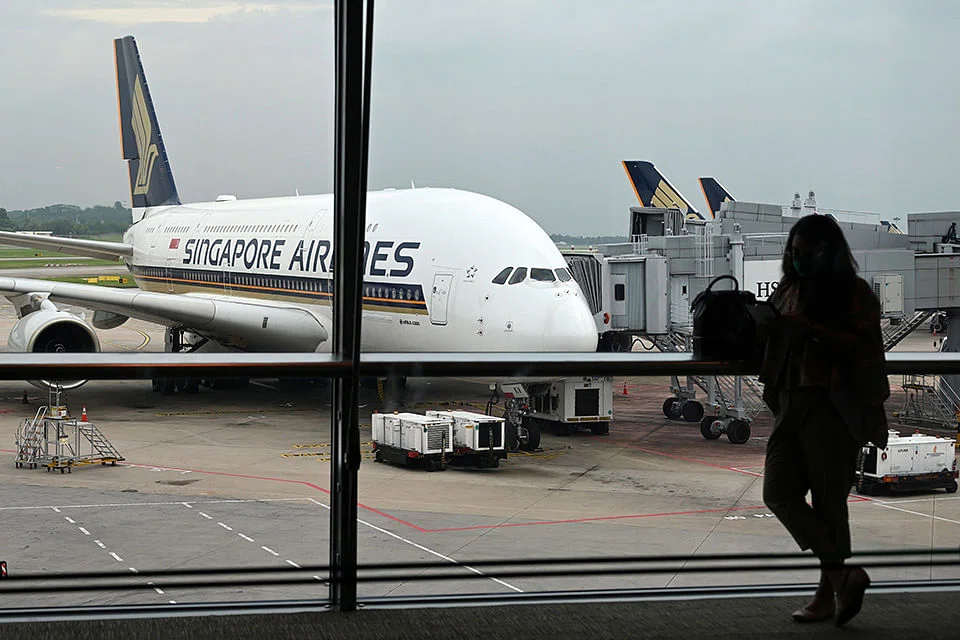
HAVING garnered strong investor interest, Singapore Airlines' (SIA) new S$850 million five-year convertible bonds have been upsized and will carry a 1.625 per cent coupon.
The initial conversion price is S$5.743 for each new ordinary share, said the flag carrier in a filing early Friday. That represents a conversion premium of about 45.8 per cent over SIA's closing stock price on Thursday.
The offering was four times oversubscribed by institutional and other investors, which enabled the national carrier to upsize the deal from an initial S$750 million and with more attractive terms for SIA, the airline said in a statement on Friday.
HSBC was the sole bookrunner and lead manager of the sale. John Huang, HSBC managing director and head of strategic equity and financing for the Asia-Pacific, said the transaction benefitted from the announcement of the Singapore-Hong Kong air travel bubble which brought cheer to airlines, as well as risk-on investor sentiment driven by positive news of Covid-19 vaccines.
"This is a landmark transaction for the Singapore market and generated significant interest globally, with the final order book well oversubscribed with high-quality institutional investors," Mr Huang said.
SIA was thus able to achieve the highest conversion premium by an airline in Asia ex-Japan and the largest convertible bond transaction from a Singapore-based issuer in nearly a decade, he added.
Goh Choon Phong, SIA chief executive, said the placement was executed "with a highly competitive coupon and substantial conversion premium".
Such attractive terms for the company underscore the confidence that investors have in SIA and its ability to overcome near-term challenges and emerge a leader in the industry, said Mr Goh.
The unsubordinated and unsecured bonds will be issued at par, and will mature on Dec 3, 2025. If they are all converted, the airline will allot and issue about 148 million new ordinary shares, which represent about 5 per cent of the existing issued shares.
SIA plans to allocate 60-80 per cent of the proceeds from the issuance for operating cash flow and debt service, while 20-40 per cent will go into capital expenditure. DBS Group Research on Friday said the convertible bonds will help to further boost the company's liquidity position.
Since the start of FY2020/2021, including the latest issuance, SIA has raised about S$12.2 billion in total. That includes S$8.8 billion from its rights issue earlier this year, S$2 billion from secured financing and more than S$500 million through new committed lines of credit and a short-term unsecured loan. It also retains the option of raising up to another S$6.2 billion in additional mandatory convertible bonds, which it can exercise by July 2021.
DBS analyst Paul Yong said SIA is in a strong liquidity position to ride through the crisis, with over S$7 billion in cash and bank balances and an estimated cash burn rate of about S$300 million per month, excluding capital expenditure.
This also comes as SIA's losses are likely to narrow - Mr Yong expects the airline to record further losses in the second half of its current fiscal year ending March 31, 2021, albeit with significantly lower impairment charges and likely less ineffectiveness in fuel hedging. He estimates SIA will record annual revenues of S$4.2 billion for FY21 and S$12 billion for FY22, an operating loss of S$2.1 billion for FY21, followed by an operating profit of S$222 million for FY22.
In its statement, SIA said it will continue to explore other means to strengthen its liquidity as necessary. "Positive discussions" have taken place on aircraft sale-and-leaseback transactions, as indicated in its half-year results.
According to DBS, SIA's stock is fairly valued at just under one time of FY22 price-to-book-value ratio. DBS maintained its "hold" call but cut its target price to S$3.60 from S$3.75.
Shares of SIA ended Friday down S$0.11 or 2.8 per cent at S$3.83.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Morgan Stanley investment-bank list leaked in email boo-boo

Could Grab CEO Anthony Tan’s US$30 million share purchase be aimed at reassuring investors?

From folding clothes to factory work: Why China is sending humanoid robots to school

