

SIA’s mandatory convertible bonds worth a look now as yield rises, recovery takes off
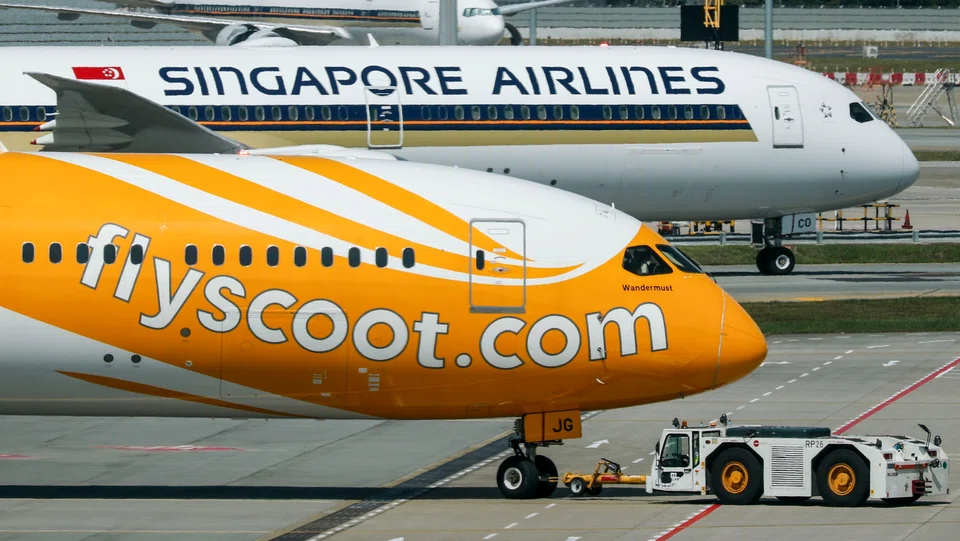
MANDATORY convertible bonds (MCBs) sold by Singapore Airlines (SIA) over the last 2 years could offer an interesting investing opportunity amid growing optimism that the carrier is firmly on a recovery track.
On Monday (May 23), the MCBs issued in 2020 were trading marginally below par, at S$0.990. The 2021 tranche of MCBs was trading at S$0.958.
The zero-coupon MCBs worth S$9.7 billion in total issue value with maturity in 2030 were liquidity lifelines for the mainboard-listed airline when it was pummelled by the pandemic and navigating the toughest year in its history in 2020.
The MCBs were initially shunned by investors partly because they can only be redeemed at the option of SIA, failing which they will be mandatorily converted into new SIA shares after 10 years.
With the reopening of international borders, however, it is looking increasingly likely that SIA will have the financial capacity to redeem the MCBs and avoid a significant expansion in its share base.
For FY2022, SIA’s annual net loss dipped by nearly 80 per cent to S$962 million and the group managed to achieve an operating cash surplus of S$824.4 million.
The carrier also reported a passenger load factor of 72.7 per cent for April — the highest since the pandemic hit global shores in early 2020.
Now that the carrier’s cash burn has stopped and is taking off on the recovery path, analysts have raised their forecasts for the group’s FY2023 earnings. One analyst even thinks SIA could possibly redeem the MCBs as early as FY2023, over 2 batches with the second redemption in FY2024.
The analyst from UOB Kay Hian, Roy Chen, noted that the redemption value of the MCBs stood at about S$10.1 billion as at end March, less than SIA’s cash holding of S$13.7 billion. He thinks that SIA could refinance the MCBs with straight debt.
Indeed, the airline acknowledged that it has no need to maintain a large cash balance, in response to a question at last Thursday’s results briefing. However, as it has just begun on its recovery path, it wants to be sure about the sustainability of its operating cash flows before addressing the structure of its balance sheet.
While SIA has no definitive plan at this point in time to redeem the MCBs, it said it will consider doing so during a future review of its balance sheet. SIA has the option to redeem the MCBs in whole or in part on every 6-month anniversary of the issue dates.
Should SIA redeem the MCBs — at a yield of 4-6 per cent depending on when the redemption is the MCB holder who buys the security from the stock exchange below S$1 — like now — would get a yield higher than the nominal rate.
The carrier will pay MCB holders a yield of 4 per cent per annum if the fixed-income security is redeemed within the first 4 years, 5 per cent per annum if redeemed between the fifth and seventh year, and 6 per cent beyond that and before maturity, compounded semi-annually.
What could stop SIA from redeeming its MCBs in the near future? Refinancing the MCBs with straight debt would push SIA’s gearing ratio up. This could have implications for SIA’s outstanding bonds or other borrowings, which may have covenants stipulating that the carrier must maintain a certain level of debt-equity ratio or other financial metrics.
Investors who purchase SIA’s MCBs also face the risk of the market value of these instruments dipping as interest rates rise. Bond prices move in opposite directions with interest rates. MCB holders who choose to sell before maturity may realise a capital loss.
If SIA does not redeem the MCBs, they will eventually be converted into new shares at S$4.84 per share (subject to adjustments in certain events). With the steep recovery in SIA’s shares in recent months, this is no longer a frightening prospect. On Monday, SIA’s share price closed at S$5.48.
The bulk of the MCBs were taken up by Temasek when they were issued. Public investors might now have an opportunity to get in at a lower price, at a time when SIA’s prospects look much brighter.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Asean’s challenge is to become resilient against global geopolitics: former Indonesia trade minister

