

Silverlake Axis eyes potential in insurtech space
Kelly Ng
THE influx of non-traditional digital banks in recent years may have spurred some excitement in the financial services ecosystem, but at least one banking solutions provider is not jumping on the bandwagon.
Rather than trying to widen its market share by servicing the non-bank players, mainboard-listed Silverlake Axis has been strengthening its offerings for Asean’s incumbent lenders.
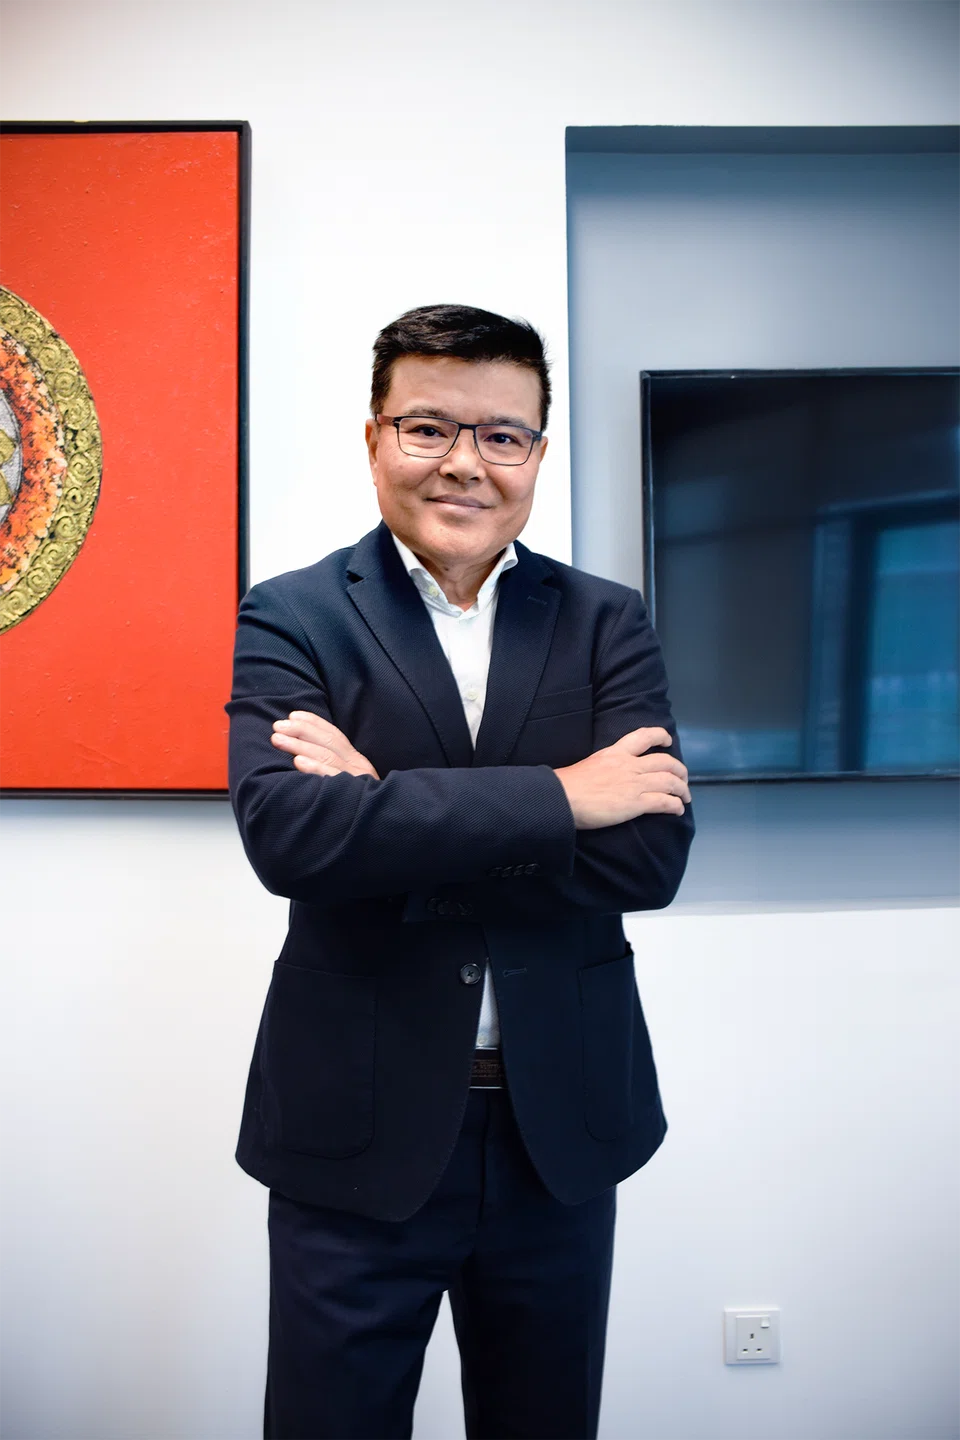
Silverlake Axis has established a foothold in the financial sector here, having been in the region for over 30 years now, its managing director Andrew Tan told The Business Times. The company counts as its clients 8 of Asean’s biggest banks, including Singapore’s OCBC and UOB, as well as CIMB, Bank Raya and Siam Commercial Bank.
Silverlake Axis was founded in Malaysia back in 1989 by Goh Peng Ooi, who previously led the banking solutions group at IBM. For the first 10 years, its operations spanned South-east Asia.
In the early 2000s, it expanded into other Asian markets, including China and Sri Lanka, and also set foot in the Middle East. In 2012, it entered the African market.
Its focus, of late, has centred on reshaping lenders into tech-driven financial institutions, and "not just financial institutions with IT departments", Tan said.
While he acknowledged that fintech firms offering banking services bring formidable competition to Silverlake Axis’s clientele, Tan believes Silverlake Axis can help incumbents emerge stronger in the contest.
"Technologies like the ATMs and Internet banking were also very disruptive when they came along some decades ago. The main difference now is that, unlike in the past, when banks were in control and can easily acquire these technologies, the disruptive forces now come in the form of ‘outsiders’ and non-banking entities," Tan said.
With that, a new cohort of banking service vendors has also emerged. These tout themselves as providing versatile platforms at low costs.
But Tan believes the roles of non-bank institutions will remain "niche", supporting "specific customer demographics".
"Larger institutions will still dominate. There are plenty of opportunities for these large banks to transform, innovate, and rethink their business models," he said.
There is also the risk of implementation failures when financial institutions migrate from one platform to another.
"Core banking transformation is not a walk in the park. It’s like a plane changing its engine in mid-flight. According to IDC, 40 per cent of core banking transformations fail or stop completely," Tan said, citing figures from the International Data Corporation.
One area where Silverlake Axis has seen successful innovations is in banking for the Muslim community in its home market.
In November 2020, it partnered a leading Islamic insurance provider to launch a "crowdsourcing" app for Takaful insurance. Unlike conventional insurance, in which the risk is transferred from the insured to the insurer, Takaful, or Islamic insurance, relies on members contributing money into a pool system to guarantee each other against loss or damage.
Also in 2020, Silverlake Axis helped power a new app that allows Muslim users to conveniently conduct various transactions related to haj affairs.
Insurtech opportunities
Silverlake Axis has also ventured into insurance technology to plug the protection gap in its Asia-Pacific markets.
The company in February launched Fermion Group, which consolidates its insurtech offerings as a distinct corporate entity headquartered in Singapore. Fermion works with about 150 insurance companies by offering data as well as end-to-end digital engagement solutions, such as customer onboarding, claims, and renewals.
The opportunities for insurtech are "particularly interesting" in Asean, Tan said, noting the growing middle-class and young population in the region.
Non-life insurance penetration in emerging markets is less than a third that of developed markets in terms of premiums as a percentage of gross domestic product, according to data from reinsurance company Swiss Re Institute.
As of 2019, the penetration rate reportedly remained below 1 per cent in Indonesia, Philippines, and Vietnam, and below 2 per cent in Thailand, Singapore, and Malaysia, thus presenting significant untapped potential, Tan said.
"There is a lot of scope to transform both industry and market. It is driving the gig industry here. People are digitally-savvy and have very different expectations when it comes to insurance offerings," he said.
In particular, these clients are increasingly looking for personalised solutions based on their needs and lifestyle habits.
"How popular are linear TV or radio today? People now pick and choose what, when, and where they like to watch or listen. Gone are the days when consumers just consume what is fed to them," he said.
These days, insurance has also been moving towards "preventive" services, such as helping clients keep fit, maintain a healthy diet, and sleep well, and away from mitigating damage from accidents or diseases. Tan considers this shift a "logical progression" as societies climb higher along Maslow's hierarchy of needs.
Moving into insurtech is a "natural crossover" for a core banking solutions provider, he said.
"From a consumer perspective there’s no difference if the long-term savings, whether for retirement or education purposes, are with banks, insurance, or wealth management firms. Everything is intertwined in the financial system.
"Fermion is one of those things we are putting a lot of bets on. We have been investing, bringing along new talent, and looking to buy companies."
Fermion has its roots in the amalgamation of 2 existing companies: Merimen, which first started offering software-as-a-service for the motor insurance industry; and Cyber Village, which provides digital engagement solutions for financial institutions.
Fermion last September inked a teaming agreement with Malaysia-based insurtech specialist DynaFront Holdings, in which the companies agreed to co-create innovations "to achieve digital insurance leadership".
The company is in talks with a Singapore-based corporate that specialises in online distribution of insurance for the travel sector, Tan said, but declined to name the company.
Steady growth
Shares of Silverlake Axis have underperformed the broader market over the last 5 years, falling 43 per cent even as the Straits Times Index gained over 6 per cent.
The underperformance could be a result of the group's shaky financial performance. Revenue rose from RM549.9 million in FY2017 ended June to RM680.8 million in FY19, but fell subsequently to RM663.7 million in FY20 and RM626.1 million in FY21. Net profit, meanwhile, was impacted by several one-offs - which led to large swings. The company's bottom line fell 84 per cent from RM863.7 million in FY17 to RM134.1 million in FY18, then climbed 83 per cent to RM245.6 million. Net earnings have fallen in the recent 2 years. From FY20 to FY21, full-year earnings fell 11 per cent from RM84.7 million to RM75.6 million (S$23.9 million).
But analysts believe Silverlake's fortunes could improve. CGS-CIMB analyst Andrea Choong noted in a February 2022 note that the company signed 2 large deals in Thailand and Indonesia in Q2 FY22, which are expected continue contributing licensing and project services revenue for the next 3 financial years. Silverlake Axis is well-positioned to capture banks' growing investment appetite for tech and core banking system upgrades, she said.
Both Choong and DBS analyst Ling Lee Keng have "buy" calls on the stock with target prices of S$0.41 and S$0.39, respectively. Shares of Silverlake Axis are already doing better this year. They closed Friday (Apr 22) at S$0.32, up 10.3 per cent for the year.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

