

Singapore Airlines expected to be profitable in FY2023, analyst consensus shows
SINGAPORE Airlines (SIA) is expected to return to profitability on an annual basis in FY2023, according to analysts’ estimates.
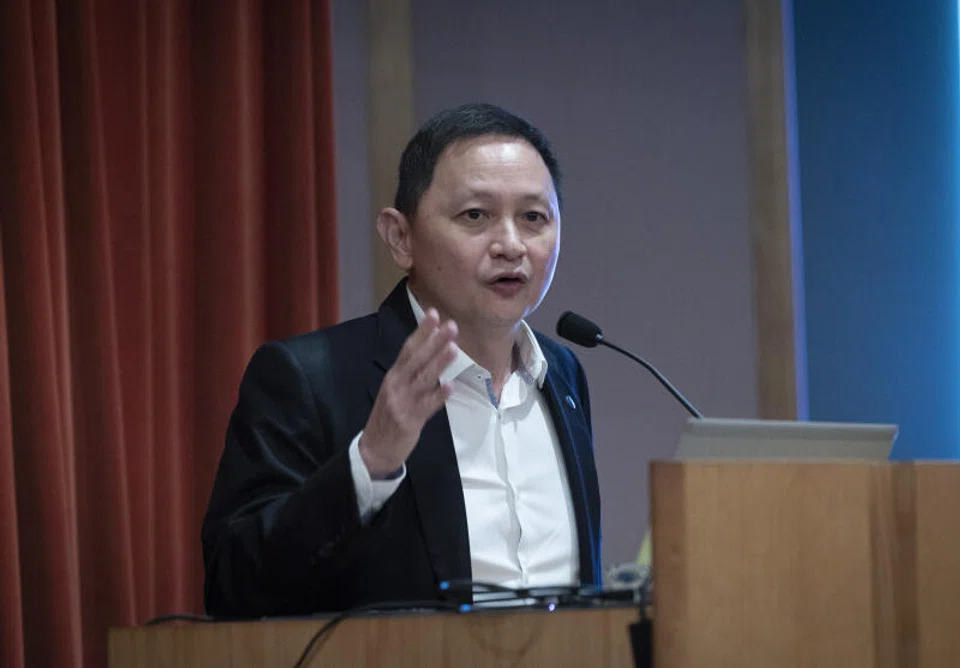
The carrier’s chief Goh Choon Phong, at an earnings briefing on Thursday (May 19), first pointed to it already being operationally profitable for the second half of FY2022 to March, and then suggested that one look to analysts for estimates, when asked about the timing of SIA’s return to profitability.
According to the analysts polled by Bloomberg, the mainboard-listed airline should be able to generate about S$160 million in net profit or earnings per share of 3.7 cents on a turnover of S$13.1 billion for FY2023 to March 2023.
The analysts had forecast the carrier would be in the red by S$954.3 million for FY2022 on a top line of S$7.5 billion. They were not too far off. SIA reported on Wednesday a top line of about S$7.6 billion and a lower net loss of S$962 million for FY2022. This was SIA’s third consecutive annual loss.
A Nomura equity analyst was neutral on the stock with a target price of S$5.30 following SIA’s FY2022 financial results release, but projected the group will still be running a deficit of S$171 million for FY2023.
An analyst from CGS-CIMB downgraded the stock to a “hold” as the share price has already re-rated 60 per cent from its 2020 lows. But he raised the target price to S$5.92.
Both analysts flagged higher fuel prices and staff expenses as potential factors that could weigh on SIA’s profitability, even as the group capitalises on pent-up travel demand and robust freight shipments.
When the quarantine-free vaccinated travel lanes were launched in 2021, the corporate bookings had lagged leisure travel. But since April this year when Singapore significantly relaxed border requirements without the need for on-arrival testing, SIA has seen “a strong rebound on corporate travel”.
“Moving forward, we are seeing that the contribution is already very similar to pre-Covid. So I will say definitely that the momentum that we are seeing in our forward bookings is coming across all customer segments,” said executive vice-president of the commercial division, Lee Lik Hsin, at the briefing.
On inflationary pressure, Goh said this is an issue the aviation industry faces but SIA has had “the best cost structure” even before the pandemic. “And with the experience of the last 2 years and the continued transformation, we can be assured that we have improved our cost structure,” said Goh. Also, Goh addressed the question of the airline extending sponsorship of Formula One, despite it incurring significant loss for FY2022. The deal, a “worthwhile” one, would provide a spin-off effect in bringing people into Singapore and for brand exposure, he noted.
Meanwhile, there is no definitive plan on redeeming the potentially dilutive mandatory convertible bonds worth S$9.7 billion, but the airline will look at it when its recovery firms up.
The counter was 5 Singapore cents lower at S$5.38 on Thursday when market closed.






