

Singapore banks' dividend cap may last beyond FY20: DBS
Lower-for-longer rates are likely to weigh on NIMs and recovery of ROE: DBS Group Research
Fiona Lam
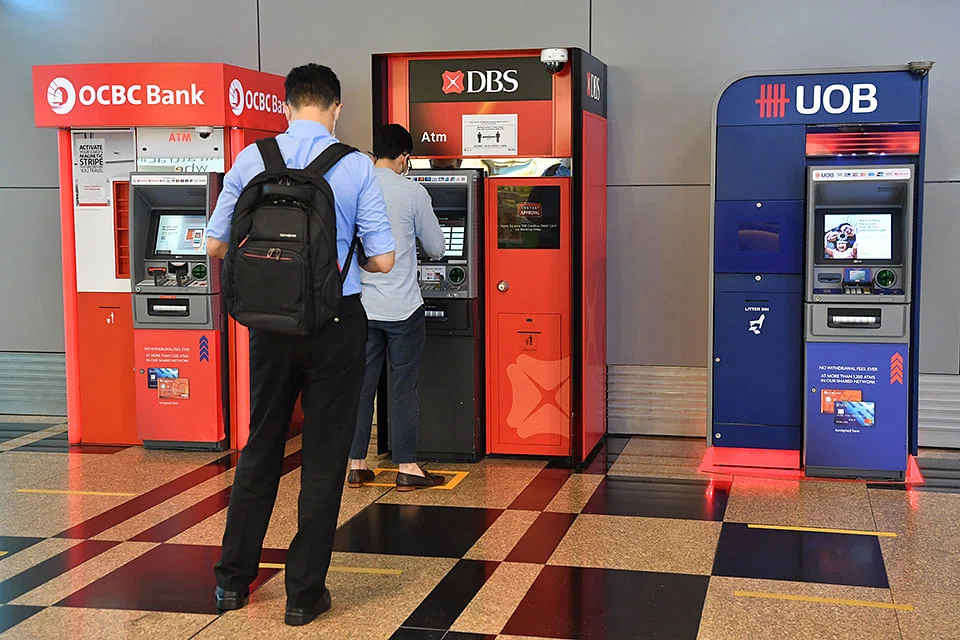
Singapore
IT is possible that the dividend cap for Singapore banks could be extended into FY21, given the lower net interest income, relatively soft credit demand and uncertainty over asset quality, said DBS Group Research.
This comes as lower-for-longer rates are likely to weigh on net interest margins (NIMs) and recovery of return on equity (ROE), analyst Lim Rui Wen wrote in a report on Thursday night.
Short-term rates have priced in no hikes for several years as the hurdle to hike rates is now set much higher. The US Federal Reserve last month made a major policy change allowing inflation to stay above its 2 per cent target "for some time" before raising rates, which will keep borrowing rates low for much longer than in prior economic expansions.
In July, the Monetary Authority of Singapore called on the three local banks to cap their total dividends per share for FY20 at 60 per cent of FY19's, so they can shore up capital amid the uncertain economic climate.
If the 60 per cent cap is extended beyond FY20, it will be from a prudent standpoint, taking into account the continued uncertainty from the coronavirus pandemic and uneven recovery paths across countries, regions and industries, DBS said.
The moratoriums offered by the Singapore banks are set to expire towards the end of this year.
To prevent a "cliff effect", it is key that the banks proactively restructure and reschedule their loans, DBS wrote, adding that going forward, any moratorium extension will likely be made on a targeted basis.
About 5-16 per cent of the trio's total loans were under moratorium as at the second quarter of this year.
Moratoriums for homeowners and small and medium enterprises (SMEs) - which form the bulk of moratorium loans locally - will end on Dec 31, based on measures introduced in March. Individuals are also allowed to defer premium payments for life and health insurance till Sept 30.
"We believe there may be a case for the extension of mortgage moratoriums minimally against the increasingly weak employment outlook into H2 2020," the analyst said.
DBS sees further room for such extensions on a targeted basis, for example for households that have lost a substantial part of their income or jobs. This is despite the low likelihood of large loan losses for mortgages given the low loan-to-value and a resilient property market, Ms Lim added.
However, if a Covid-19 vaccine remains elusive, asset quality uncertainties will likely weigh on the trio of lenders through FY21, as central banks in the region balance between supporting industries hit by the pandemic and ensuring the stability of banking systems, DBS noted.
The research team said that the Singapore banks' valuations remained inexpensive compared to regional peers, at about 0.8 times FY21 price-to-book-value ratios and trading near -2 standard deviations.
"We continue to prefer UOB to OCBC as a more defensive pick, due to UOB's larger domestic exposure, higher ROE and dividend yield," Ms Lim wrote.
She has a "buy" call for UOB with a target price of S$22.20, and a "hold" rating for OCBC with a S$9.30 target price.
UOB shares closed at S$19.40 on Friday, up S$0.01 or 0.05 per cent, while OCBC was flat at S$8.58. DBS fell S$0.03 or 0.2 per cent to finish at S$20.51.
TRENDING NOW
IOI Properties and CapitaLand Investment closer to acquiring One Raffles Place in joint bid

OCBC sheds S$8 billion in value as shares close nearly 6% down; analysts cautious on banks

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Crystal Jade closes four more outlets, cuts 120 jobs ahead of proposed sale

