

Singapore banks likely to see slower Q3 growth amid weak loans, flattish interest margins
Tan Nai Lun
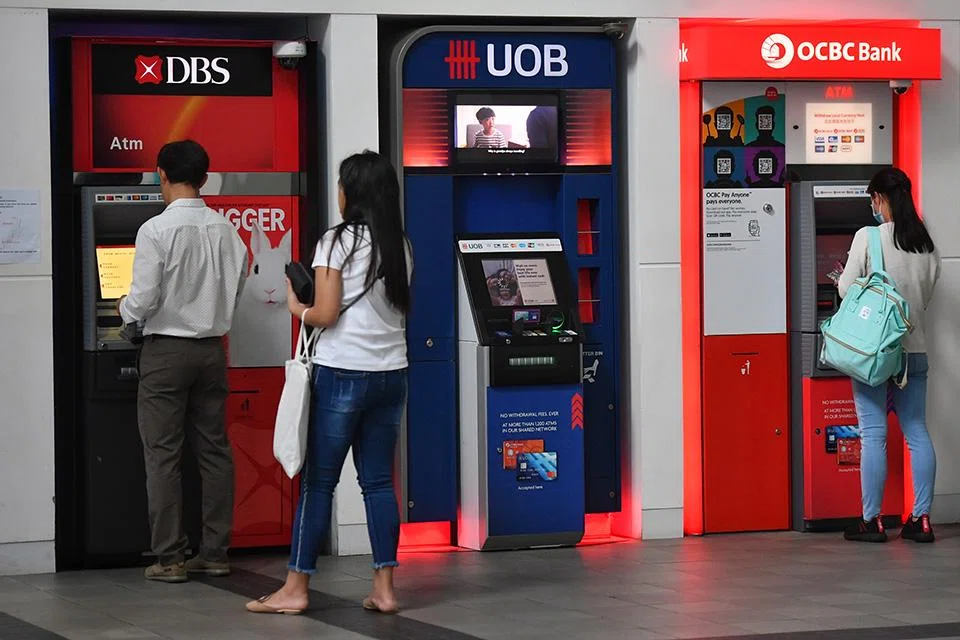
THE trio of local banks – DBS , OCBC and UOB – are likely to post slower growth for the third quarter ended September 2023, with earnings expected to be weighed down by weak loans and minimal expansion in net interest margins (NIMs), analysts said.
The Singapore banks are due to report their Q3 results in the coming weeks. This will begin with UOB on Oct 26, followed by DBS on Nov 6 and OCBC on Nov 10.
While analysts still see some room for NIMs to grow, the figures are expected to remain largely flattish.
Thilan Wickramasinghe, head of research for Singapore at Maybank Investment Banking Group, said the July interest rate hike by the US Federal Reserve could add to asset yields for the local lenders.
With the sector flush with liquidity, Wickramasinghe also expects Q2’s rational deposit competition and stable current account savings account (Casa) ratios will continue into Q3.
But still-hefty funding costs likely slowed asset yield growth and kept NIMs flattish across the sector for Q3, said CGS-CIMB analysts Andrea Choong and Lim Siew Khee.
They expect NIMs for DBS to have risen slightly as the higher Hong Kong Interbank Offered Rate offset the effects of continued Casa outflow in July and August.
However, the CGS-CIMB analysts expect NIMs will stay broadly steady for OCBC and UOB. Stabilising asset yields at OCBC are balanced by hefty funding, while loan yield growth for UOB may have been stifled by stiff competition for high quality corporate exposures.
Loans remain weak
Meanwhile, market watchers expect the banks will make further downgrades to their loan growth guidance – which are currently around the low- to mid-single-digit range – as loan demand continues to be weak, and loan growth remains muted in Q3.
Wickramasinghe noted that weak demand for trade-related debt was a key driver for weaker loans in Q2.
Continued weakness in China, plus accessibility of cheaper domestic funding, could also drive further contraction in volumes, he said.
The CGS-CIMB team said weaker corporate demand as a result of Fed rates remaining high also limited credit growth across the industry.
DBS Group Research analyst Lim Rui Wen noted that intensifying competition could start to erode loan yields beyond Q3, especially for mortgages and high-quality corporate loans.
Overall fee income, however, should remain largely stable, she said.
Lim pointed out the absence of a more meaningful recovery in wealth management fees as markets continue to be challenging, while card fees buffer other fee income.
Wickramasinghe also noted that wealth management fees showed little signs of recovery given cautious client sentiment, even as high interest rates kept funds locked up in deposits.
The CGS-CIMB team expects it will still take time for wealth management income to rise significantly as risk-on momentum builds up, especially as the Fed fund futures are pricing in the first-rate cut only in mid-2024.
Asset quality remains
Nevertheless, analysts expect asset quality will remain benign for Q3.
CGS-CIMB’s analysts noted that the banks have not indicated systemic risks at the current juncture.
The earnings downside in this area may be mitigated by the write-back of the banks’ management overlays worth around S$1-2 billion, they said.
DBS’ Lim also expects the management overlay – capital set aside by the banks to provide a buffer against shocks – will continue to provide strong support to the banks’ share prices.
Asset quality is likely to remain benign as current interest rates seem to be high enough to filter out marginal customers, while not high enough to cause undue stress to a majority of customers, Wickramasinghe said.
But he expects the banks will have a more cautious tone on asset quality and provisioning, given that additional cautionary provisions from slower macro growth cannot be discounted.
Citi analyst Tan Yong Hong said lingering concerns over potential asset quality risks and slower growth will likely cap meaningful upside to the banks’ share prices.
While there could be sporadic earnings upsides from a marginal uptick in NIMs, trading income or lower credit cost, Tan expects sustainability of earnings would come into question.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

