

Singapore banks may face squeeze in net interest margins amid muted loan growth, high demand for FDs
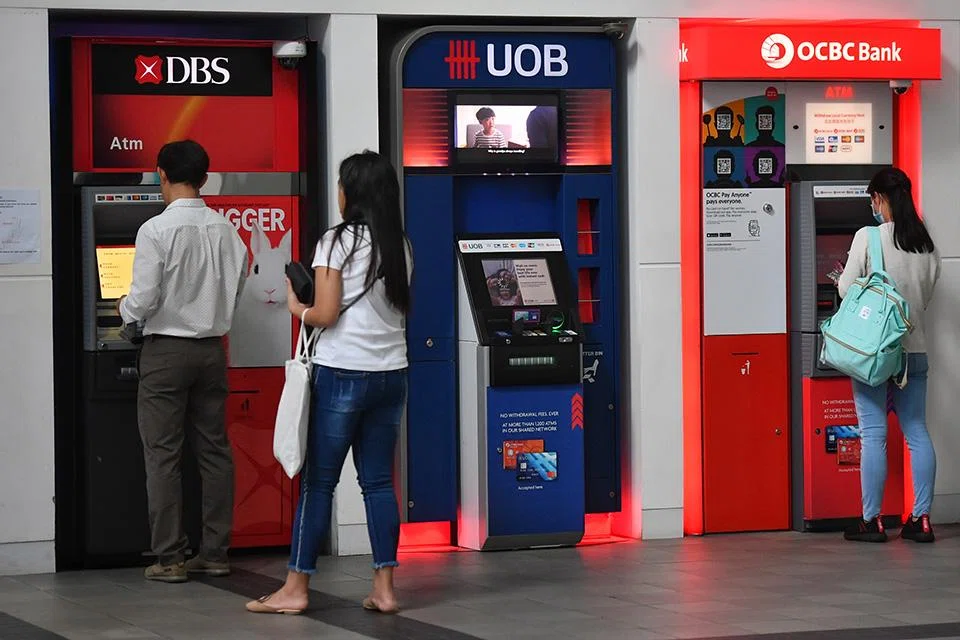
SINGAPORE banks could be in for tougher times as loan growth moderates and Singapore’s savers continue piling into higher-interest fixed deposit products, analysts said.
Recently released statistics from the Monetary Authority of Singapore (MAS) showed that the overall non-bank loan-to-deposit ratio had fallen to 73.3 per cent in February 2023, from 81.2 per cent in February 2022.
In July 2021, the loan-to-deposit ratio was 85 per cent. Comparable statistics are not available for earlier periods following changes in MAS classifications. Non-bank loans and deposits are those of individuals and non-bank companies or other institutions.
Total loans and advances, including bills financing, have fallen 4.5 per cent to S$1.29 trillion in February 2023, from S$1.35 trillion in February 2022.
Most of the decline can be attributed to non-resident loans and advances, down 5.8 per cent; and bills payable outside Singapore, down 33.1 per cent.
Resident loans and advances fell year on year by 2.8 per cent, while bills payable in Singapore were down 18.4 per cent.
Deposits, meanwhile, are rising. Total deposits and balances of non-bank customers came to S$1.77 trillion in February 2023, up 6.1 per cent from S$1.66 trillion in February 2022.
The biggest increase came from fixed deposits (FDs), up 78 per cent to S$839 billion. Savings deposits fell 19.5 per cent to S$260.9 billion, and demand deposits fell 27.4 per cent to S$590.2 billion.
The proportion of fixed deposits in the Singapore banking system has exceeded demand deposits since September 2022, when fixed deposits totalled S$709.9 billion and demand deposits totalled S$683.1 billion.
In July 2021, fixed deposits totalled S$441.9 billion and demand deposits totalled S$749.1 billion.
Commenting on the statistics, Ivan Tan, a banking analyst at S&P Global Ratings, said the decline in the loan-to-deposit ratio reflected a moderation in loans growth that he expects will continue this year.
He believes loan growth in Singapore will be in the low to mid-single digits in 2023.
At the same time, funding costs will rise for the local banks. Tan noted that banks have had to raise their rates on fixed deposits as well as current and savings accounts (Casa) to compete with the attractive yields on Singapore Treasury Bills (T-bills).
T-bills are relatively short-term instruments and with very low risks, meaning they are effective competitors for savings.
DBS analyst Lim Rui Wen expects the rise in the cost of local banks’ deposits to continue.
Net interest margins for the three local banks, which are now touching new highs, will be hurt if banks are unable to pass on the higher cost of funds.
In its recently released annual report, OCBC said its net interest margin (NIM), at 1.91 per cent, was the highest in over 10 years.
DBS said its latest NIM is now running at more than 2 per cent – the highest in more than a decade. But the bank also flagged that Casa outflows and higher deposit costs had moderated its NIM increase in the fourth quarter of last year.
Maybank head of research Thilan Wickramasinghe said deposits may also be growing as money flows into Singapore in search of a safe haven. But he, too, believes loan growth will remain muted in 2023.
Even so, he added, there is still room for NIMs to rise somewhat as central banks continue to raise interest rates in their battle against inflation. This, he said, should somewhat offset weaker credit growth.
TRENDING NOW
China Investment Corp, PGIM’s 50% stake in Nex mall up for sale; asking about S$1.2 billion

Higher rates, weaker spending: Is the Philippines entering stagflation?
Singapore tech stocks plunge as Nasdaq bloodbath spills into region

OCBC wealth clients turn defensive amid market volatility as Q3 profit rises 3%

