

Singapore banks may miss the O&M boat when sector recovers
In the meantime, other players are picking up assets on the cheap while the banks ponder their next moves
IT IS no secret that the big three local banks have resorted to foreclosing vessels to salvage outstanding loans extended to offshore and marine (O&M) companies under distress.
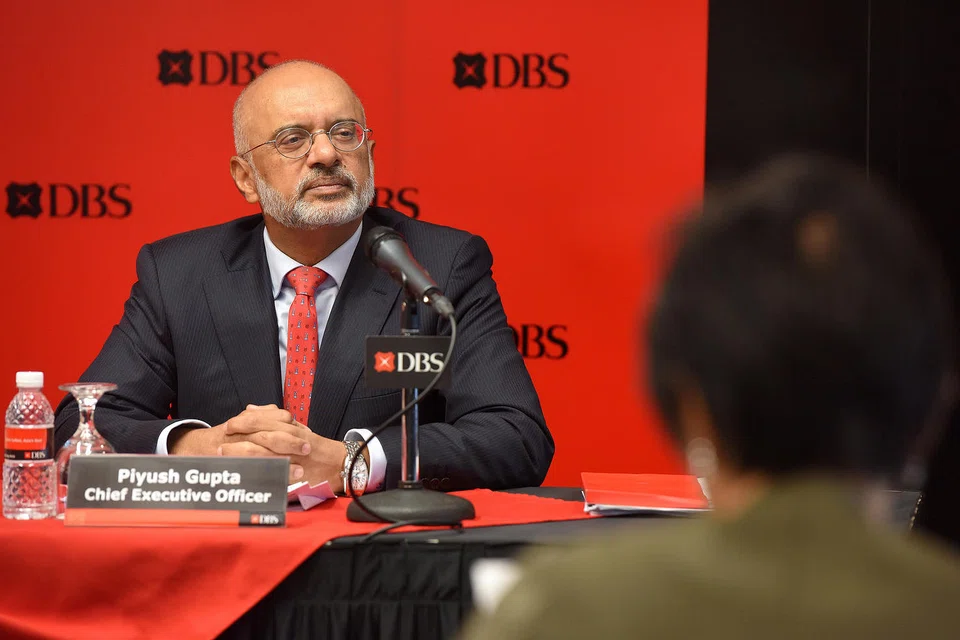
DBS group chief executive, Piyush Gupta at a Singapore Maritime Week panel session openly joked that the bank has emerged as "a reluctant owner" of shipping assets.
Mr Gupta made this remark in late April, just weeks after a former stock market darling, Ezra Holdings, filed for Chapter 11 bankruptcy protection. Two other listed O&M players, Swissco Holdings and Swiber Holdings, have headed into judicial management (JM).
Stresses from their O&M exposure had forced the big three banks to increase their non-performing loan (NPL) provisions.
The banks have thus claimed that they are done with O&M provisions; the challenge at hand now is how they may then partake in the restructuring of the sector so as to mitigate their damages sustained from the O&M fallout.
There are worrying signs, however, that a tendency to over-compensate may cost the banks here the opportunity to redeem their standing in the O&M sector.
To begin with, banks are no longer underwriting loans for the construction of ships from scratch.
Singapore's banks are not alone in this - banks worldwide have pulled the plug on newbuild financing as overcapacity besieged most O&M segments.
Where Singapore has lagged behind is the restructuring of massive O&M debts here, the process in which the three big banks have played a major role.
Pareto Securities Pte Ltd's chief executive, David Palmer observed that in many cases, banks and companies "were merely moving debt and maturities around" and "replacing lower-priced debt with increasingly expensive debt". This attempt at kicking the can further down the road has contributed to the heightened insolvency risk in Singapore's O&M sector.
Singapore's banks have several options to recover debt from insolvent O&M companies. One option is to foreclose vessels mortgaged to bank loans, as Mr Gupta alluded to.
A second route taken by banks backing listed O&M entities in Norway and the US is to swap debt for equity; this seems to fall outside the comfort zone of senior lenders here, perhaps owing to the due impairments from taking equity in companies under financial duress.
The inconvenient truth though for Singapore's banks is that the market valuations of the vessels reflected in their books, have fallen drastically. In some cases, these valuations are hovering at just above scrap values.
So it is apparent that losses are inevitable if banks want to offload these assets any time soon. Or they can choose to put these vessels out to work in the market. To cut deals in either case will call on banks to take haircuts and banks' resistance to do so had emerged as show-stoppers, one source said.
As Singapore's banks ponder over their next moves, fund houses and private equity players have entered the fray to pick up assets on the cheap.
What these investors are eyeing are the high-margin returns possible from holding on to these bargain asset buys until the O&M market stages a rebound.
Oil companies have already signalled plans to revisit deferred projects now that oil prices have stabilised in the US$50s.
Taking into account the responses from Singapore's financial sector, M3 Marine's managing director, Mike Meade summed the situation up in this bleak prediction: "When the O&M sector eventually stages a rebound, Singapore's banks would have been so scarred by this downturn that they could have missed the boat altogether."






