

Singapore banks see improved asset quality in 2021 with recovery ahead
They expect lower credit costs with bulk of provisions already taken, setting stage for a pick-up; they also await lifting of dividend cap
Singapore
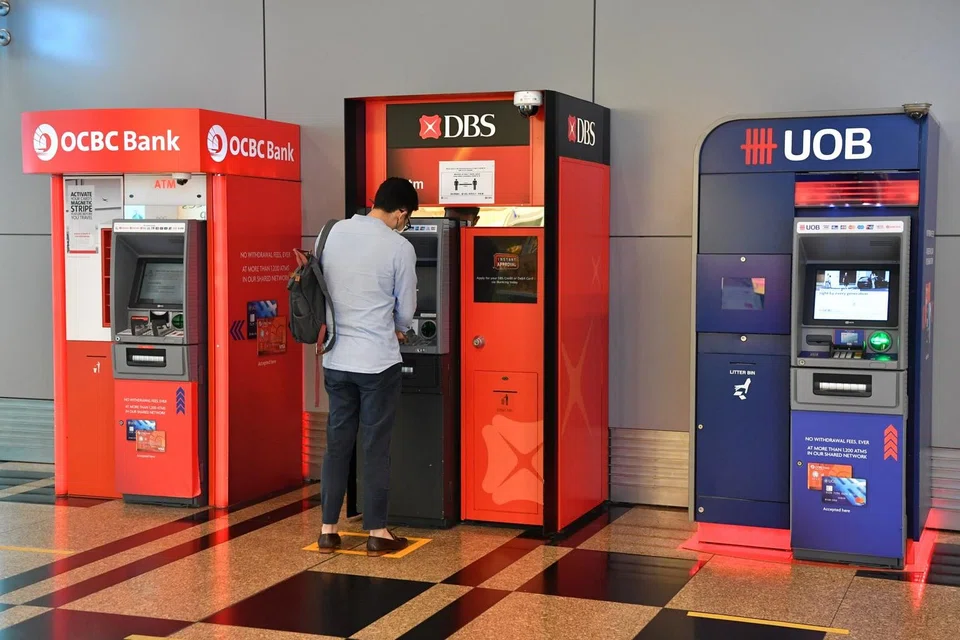
SINGAPORE banks are easing their worst outlooks on bad debt, as loan relief is scaled back amid growing optimism on economic recovery this year.
With increased clarity on asset quality, banks are guiding for lower credit costs in 2021 as the bulk of provisions have already been taken, setting the stage for a pickup after a year that saw businesses and economies hard-hit by the pandemic.
In the latest fourth-quarter results, DBS - the first among the trio to kick off earnings season - projected for total allowances over 2020-2021 to come in at the middle end of the S$3-5 billion range.
DBS chief Piyush Gupta told the media: "Our guesses are that we're not going to need as much credit provision as originally anticipated. I'm certainly feeling more optimistic about the overall quality of the portfolio and asset conditions now than I was able to tell you three months or six months ago."
It was a sentiment echoed by OCBC and UOB, which announced their results this week.
Outgoing OCBC group chief executive Samuel Tsien expects credit costs to come in at the lower end of its two-year projection of between 100 and 130 basis points. With credit costs for FY2020 at 67 basis points, credit costs in 2021 could be half of that and closer to pre-Covid levels. This comes on the back of an "orderly and very well-managed" exit from Covid-19 relief programmes - an outcome that is "better than expected", he added.
UOB chief financial officer Lee Wai Fai estimated that credit costs for 2021 will come in at 30-40 basis points, "significantly lower" than previously guided. This improvement in asset quality emerges as the majority of moratoriums have expired at the end of last year, with banks reporting significant declines in loans under relief programmes and most customers resuming payments.
For DBS, slightly over 1 per cent of its loan book remains under moratorium - the lowest among the three banks. Out of the S$5 billion of housing loans that were under moratorium for DBS, about 10 per cent of these have applied to extend. About 25 per cent of DBS's SME clients in Singapore who were on government moratorium schemes have applied to continue deferring repayments on their loans
Moratorium extension numbers are highest in DBS's Hong Kong loan book. At its peak, loans under moratorium stood at around S$6.5 billion - about half are currently under extension. Mr Gupta noted that extended moratorium schemes are being contained, with more visibility on realised credit costs from the second quarter of this year when the extended moratoriums expire.
For OCBC, loans under moratorium make up 2 per cent of total loans, down from 4 per cent at the end of December. At the end of September 2020, it had been 9 per cent of the bank's loan book.
At UOB, about 6 per cent of its total loans are under relief as of end-January, down from almost 9 per cent at end-December 2020. This takes into account government relief programmes, UOB's own relief programmes and the Enterprise Singapore loan schemes.
Even as credit cost risks recede, all three banks saw profits and net interest income slide in the fourth quarter compared to a year ago on the back of lower net interest income and higher allowances, capping off a year roiled by a global health crisis.
DBS's net profit for the fourth quarter was down 33 per cent to S$1.01 billion, in line with analyst estimates. Total allowances in Q4 came in almost five times higher than the year-ago period at S$577 million.
OCBC beat analyst expectations, with net profit down 9 per cent to S$1.13 billion, with allowances for the quarter 37 per cent higher than a year ago.
UOB's net profit was down 32 per cent to S$688 million, as allowance for credit and other losses more than doubled to S$396 million for the quarter, in line with analyst estimates.
With the improvement in asset quality, banks are awaiting guidance from the Monetary Authority of Singapore (MAS) on the lifting of dividend caps as the curtain falls on FY2020.
Bank dividends were a far cry from the same time a year ago: in the latest quarter, DBS proposed a final dividend payout of 18 Singapore cents per share, against 33 cents a year ago; OCBC proposed a final dividend of 15.9 Singapore cents per share, down from 28 cents in the year-ago period; and UOB proposed a final dividend of 39 Singapore cents per share, down from the final dividend of 55 Singapore cents and special dividend of 20 cents previously.
Banks, however, are keen for dividend caps to be lifted. OCBC's chief financial officer Darren Tan said the bank hopes the cap will be lifted "as a way to recognise and reward our shareholders' confidence in us".
UOB said the bank will resume its 50 per cent dividend payout ratio once the dividend cap is lifted.
This comes as the banks have shored up capital over the year, with the common equity tier-one (CET-1) ratio increasing for both OCBC and UOB.
OCBC's CET-1 ratio - a measure of banks' capital strength - rose to 15.2 per cent in December 2020, up from 14.4 per cent the quarter before, on the back of the positive impact of the migration to internal ratings-based approach at OCBC Wing Hang Bank. It is by far the highest among the three banks.
UOB's CET-1 ratio was 14.7 per cent, up from 14 a quarter ago. DBS's CET-1 ratio remained the same as the previous quarter at 13.9, but this was mainly due to the amalgamation of its Lakshmi Vilas Bank takeover which lowered CET-1 by 0.3 percentage points.
With the banks' CET-1 ratio above the optimal range of 12.5-13.5 per cent, analysts projected that there could be a possible upside to dividends once the dividend caps are lifted. For instance, Jefferies has raised its forecast for OCBC's FY2021 dividend to 48 Singapore cents from 41 Singapore cents.
Such strong capital levels could result in potential merger and acquisition exercises for OCBC, given the capital firepower, noted CGS-CIMB analyst Andrea Choong.
On Thursday, shares of DBS closed up 50 cents or 1.89 per cent to S$26.90; OCBC rose 22 cents or 2.03 per cent to S$11.07; and UOB gained 77 cents or 3.22 per cent, to end at S$24.65.
READ MORE: UOB optimistic despite Q4 profit down 32%
TRENDING NOW
DBS remains analysts’ pick ahead of Q3 earnings after Singapore banks’ share slump
Singapore identifies 7 firms responsible for haze fires, notices issued urging action: Grace Fu
Good Class Bungalow market activity picks up pace on ‘realistic’ pricing

High Court rules against Julius Baer’s Singapore trust arm in US$50 million family trust dispute

