

Singapore banks surge to record highs on Tuesday
The strong performances come ahead of the upcoming Federal Open Market Committee’s meeting
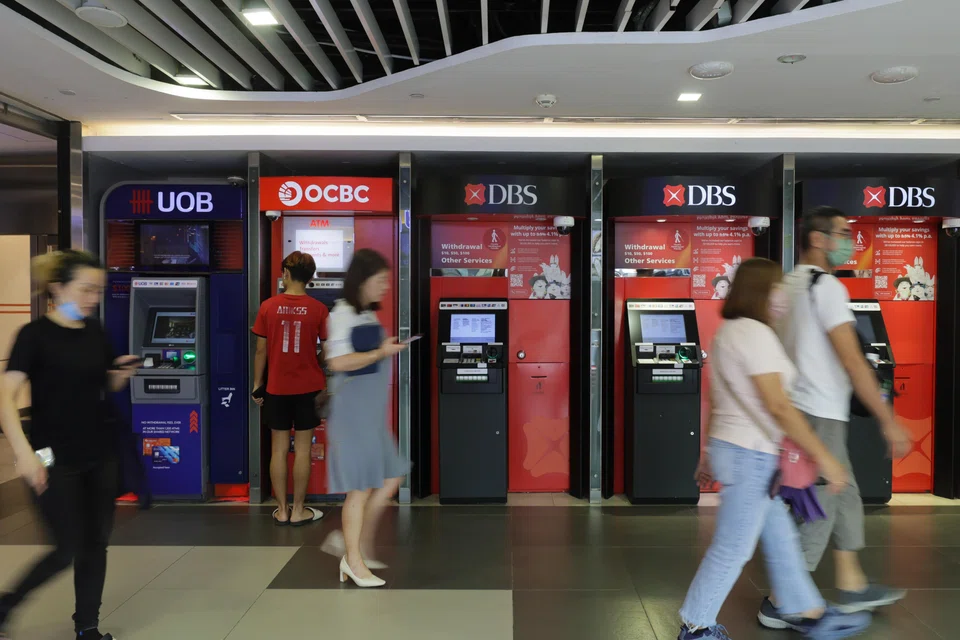
THE share prices of DBS and OCBC closed at a record high on Tuesday (Jul 2), with UOB also putting in a strong showing.
All three local banks started moving up after the midday break, with OCBC and UOB breaching all-time records after an initially mixed showing at the opening bell.
For the first time, Singapore’s largest lender DBS surpassed the S$37 per share mark to reach S$37.08 as at 2.06 pm, up S$0.96 or 2.7 per cent. Shares of OCBC leapt S$0.27 or 1.9 per cent to hit a historical peak of S$14.77 as at 2.08 pm.
UOB gained as much as S$0.33 or 1.1 per cent to S$31.63 as at 2.24 pm, marking the counter’s highest levels since April 2022.
The three counters ended higher at the end of the trading day. DBS eventually closed at S$37.10 after surging S$0.98 or 2.71 per cent. OCBC ended S$0.30 or 2.07 per cent higher at S$14.80 while UOB gained S$0.35 or 1.12 per cent to close at S$31.65.
The strong performances of all three banks came ahead of the Federal Open Market Committee’s meeting due at end-July.
The US central bank left rates unchanged within the 5.25 to 5.5 per cent range after the last meeting on Jun 12, while pencilling in just one rate cut before the year-end.
This delay in anticipated Fed rate cuts provides optimism to the FY2024 business outlook of Singapore’s banks, said CGS International analysts, who reiterated the sector’s “neutral” rating on Monday.
CGS International has “add” calls for UOB and OCBC with the respective target prices of S$33.30 and S$15.40.
“UOB is our top pick in the sector as we look forward to earnings synergies to materialise from the integration of its newly acquired Citi franchise,” said its analysts.
“We believe write-backs of management overlays are unlikely until Covid-19 truly blows over. The credit quality of (UOB’s) portfolio of loans under moratorium remains healthy. Asset quality concerns from its small and medium-sized enterprise and Asean portfolio are also well contained, in our view.”
For OCBC, CGS International highlighted the bank’s “robust” Common Equity Tier 1 ratio of about 16 per cent as at end-Q1 FY2024 as a “key advantage” in view of mergers and acquisitions, or to cushion against potential asset quality deterioration.
The research house rated DBS “hold” with a target of S$35.90. It nonetheless believes DBS’ asset quality risks of exposure to onshore China property remains “contained”, as most of its loans are extended to Chinese state-owned enterprises.
Noting that Singapore’s equity market gained 3.4 per cent in the second quarter this year alone, Phillip Capital attributed this partially to “another commendable quarter” from the local banks as attractive dividend yield and fee income recovery drove their share prices.
In a research report on Monday, Phillip Capital research head Paul Chew said he saw upside to DBS’ dividends as the bank had no cap on its dividend payout ratio, as opposed to UOB’s and OCBC’s 50 per cent.
“Stable net interest margins, low-single-digit loan growth, and double-digit growth in fee income will sustain (DBS’) earnings momentum,” he added.
RHB Research also foresaw continued growth for DBS’ absolute dividend per share (DPS), with investors having a “good line of sight as to its growth trajectory” given the bank’s commitment to increase DPS by 24 Singapore cents per annum.
In its research note on Tuesday, RHB noted that the bank’s mid-term return on equity guidance of 15 to 17 per cent “compares favourably” against its pre-pandemic range of 9.5 to 12.8 per cent.






