

Singapore banks unlikely to cut mortgage rates in 2024 despite expected Fed rate cuts
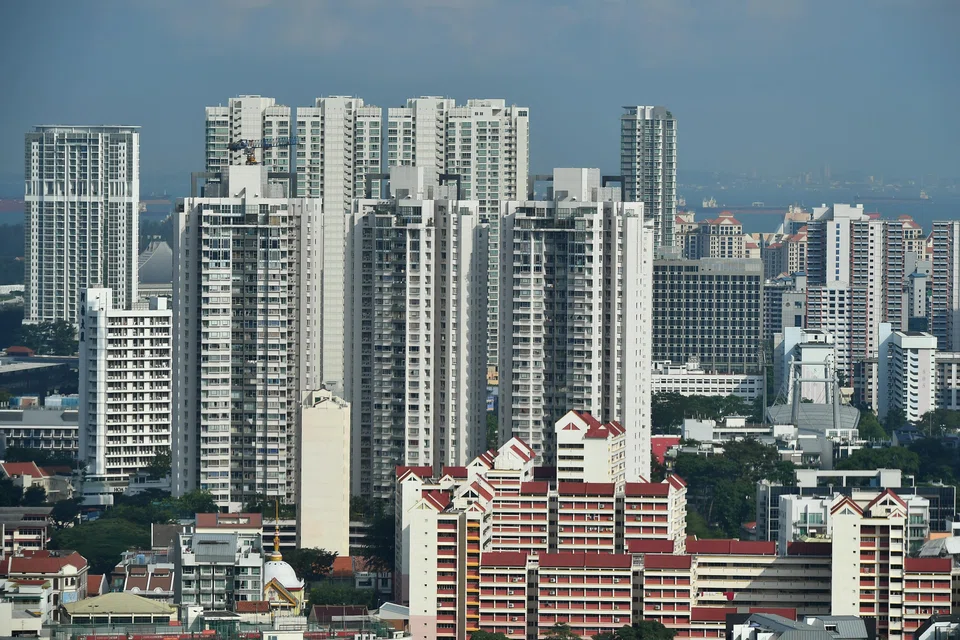
ONGOING economic uncertainties and rising costs are likely to keep Singapore banks from slashing their home loan rates in 2024, despite expectations that the US Federal Reserve will cut its benchmark interest rate at least three times this year.
While home mortgage rates are forecast to be trimmed alongside the expected rate cuts, analysts said the degree of adjustments may differ as banks continue to strive for better risk-return profiles.
Clive Chng, associate director at Redbrick Mortgage Advisory, said it is reasonable to expect that banks will continue to be selective in their pricing amid global uncertainties and interest rate volatility.
“This selectiveness is not just a reflection of the competitive market, but also an indication of their focus on maintaining a balance between risk and return,” he said, noting that the local banks are known for their prudent and strategic approaches to loan pricing.
Bloomberg Intelligence credit analyst Rena Kwok and industry analyst Ken Foong also expect the trio of local lenders not to be in any hurry to lower their mortgage rates.
Even as the banks defend their market share, these loans offer favourable risk-returns, the analysts said in a recent note.
Furthermore, a mortgage price-war scenario is unlikely given an overall rise in funding costs, said Thilan Wickramasinghe, head of Singapore research at Maybank Investment Banking Group.
This is despite the fact that the local banks have enjoyed large deposit inflows, giving them access to competitively priced liquidity and an advantage in maintaining their slice of the market, he said.
However, MortgageWise.sg executive director Darren Goh noted that mortgages are like commodities as it is difficult to differentiate one from another, hence the pricing of these mortgages is key for banks to maintain market share and to meet targets. (*See amendment note)
“Banks may initially hold out slashing their mortgage rates, but it usually won’t last more than two months before a price war will see rates settling at a lower level,” he said.
Stiff competition
DBS analyst Lim Rui Wen noted that there has been stiff competition in mortgage rates since the second half of 2023, even as benchmark rates rose.
According to checks on mortgage rate comparison websites, fixed-rate loan packages are currently around 3 to 3.5 per cent. In January 2023, fixed home-loan rates offered by Singapore banks hit a peak of 4.25 per cent per annum.
Meanwhile, floating-rate packages – pegged to the Singapore Overnight Rate Average (Sora) – are currently around 4.2 to 4.4 per cent.
Three-month and six-month compounded Sora rates have hovered around 3.6 to 3.7 per cent since July 2023, according to data from the Monetary Authority of Singapore (MAS).
Lim expects Fed rate cuts may further accelerate downward revisions of both fixed and floating rates, as banks try to boost their mortgage portfolios amid weak loan growth expectations.
“As loan growth outlook broadly remains weak, we believe extending mortgages continue to be attractive for banks,” she said.
But Maybank’s Wickramasinghe believes mortgage rates – especially fixed rates – may not fall in tandem with or in the same quantum as the policy cuts.
Amid a notable shift by borrowers towards fixed-rate mortgages, he said lower policy rates may not immediately impact the mortgage margins of the banks.
Redbrick’s Chng also noted some alternate scenarios to consider: based on current data, there could be a moderate to slight decrease in mortgage rates in 2024 to align with global interest rate trends, especially if MAS adopts a similar easing policy.
If banks remain selective and competition continues to be stiff, there could also be a trend towards more competitive mortgage rates and features as banks strive to attract creditworthy borrowers, he said.
But this will also be influenced by broader economic factors, local monetary policies and global interest rate trends, he added.
MortgageWise.sg’s Goh said that for consumers, this would mean that homeowners should keep an exit option and review their rates within 12 months. “In fact, be very wary this year, as the runway to benefit from even a one-year fixed rate has become shorter and sentiments can change in no time – like what we’d seen.”
He noted that it was “just a little more than a month ago” that the narrative was that rates will stay higher for longer.
Flat growth in mortgage portfolio
Analysts believe mortgage loan growth for the local banks will be largely flat or in the low single digits for 2024.
Lim noted that the residential property market has a largely flattish outlook for 2024, and may be further weighed by worse-than-expected economic conditions and more mortgage repayments due to high interest rates.
Maybank’s Wickramasinghe also expects new private property sales to be flat in 2024 due to lower completions.
Regardless, the Bloomberg Intelligence analysts noted that the local banks have built a healthy loan pipeline over the past few years, which should support their mortgage growth this year.
*Amendment note: This article has been updated for clarity.
TRENDING NOW

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Income Insurance appoints former Manulife Singapore top man as new CEO

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

