

Singapore digital banks GXS, MariBank lean on South-east Asia to fuel profitability
They state that loans will be a key driver for growth
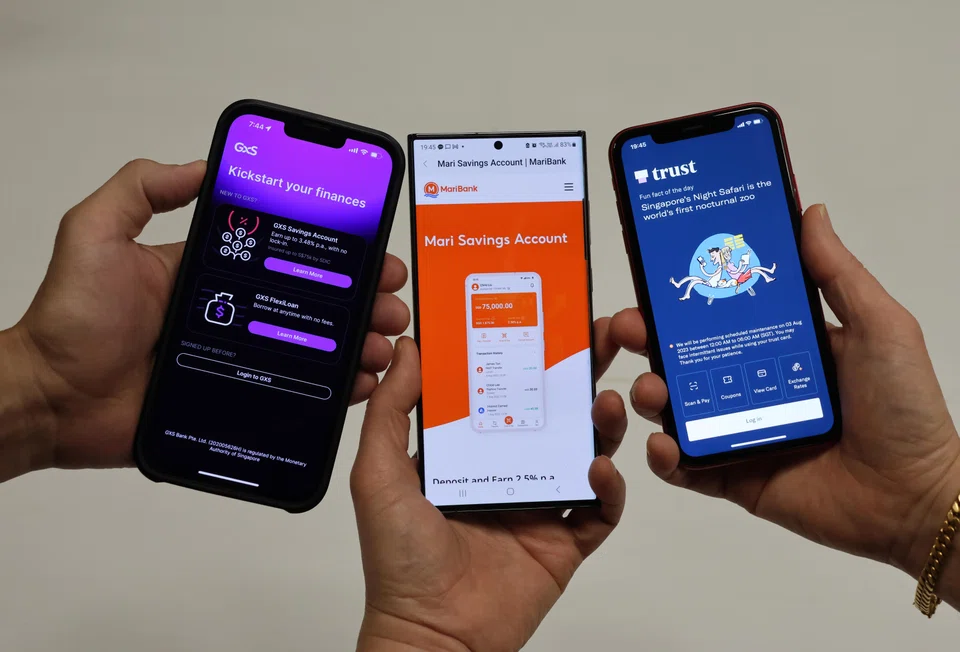
[SINGAPORE] Singapore’s digital banks are turning to faster-growing South-east Asian markets to drive loan growth as they set their sights on the path to profitability. This is amid rising interest income and mounting investor scrutiny.
Regional businesses in Malaysia and the Philippines are becoming increasingly important contributors to growth for both GXS Bank and MariBank, as competition intensifies in Singapore’s more mature banking market.
In FY2025, both GXS Bank and MariBank in Singapore reported higher interest income, reflecting how lending has remained a key driver of their growth strategies.
At GXS Bank, interest income grew some 60.4 per cent from S$44.1 million in 2024 to S$70.8 million in 2025. At MariBank, that growth was some 33.7 per cent, from S$53.1 million in 2024 to S$71.9 million in 2025.
GXS Bank started with GXBank in Malaysia already part of the wider group in 2022, while MariBank acquired SeaBank Philippines – now known as MariBank Philippines – from parent company Sea in April 2025.
The emerging markets in South-east Asia have a higher growth headroom than Singapore, said Avishek Nandy, partner at Bain & Company.
“Bain estimates the Asean-6 banking pool will exceed S$400 billion by 2030 – and with around 220 million unbanked adults across the region (outside of Singapore), that’s where the structural digital banking opportunity sits,” Nandy told The Business Times. The banking pool refers to the revenue opportunities available.
He noted that Indonesia’s banking market alone is expected to grow from about US$60 billion today to more than US$120 billion by 2030, while the Philippines and Vietnam are expanding even faster from smaller bases.
This is compared with a US$70 billion banking pool in Singapore today, which Bain expects to grow to about US$100 billion by 2030, driven by wealth and corporate banking.
At MariBank, its Philippines business contributed S$155.1 million of the group’s S$227.1 million in total interest income for 2025.
The digital bank in the Philippines also contributed S$21.8 million of the S$25.9 million in net fee and commission income in 2025 for the larger MariBank group.
MariBank Philippines was profitable, shaving some S$9 million off group losses for 2025.
It originated from Banco Laguna, a rural bank converted into a digital bank after its acquisition by Sea in 2020. It was then named SeaBank Philippines, before being rebranded to MariBank Philippines in July 2025.
At GXS, Malaysia’s GXBank contributed S$24.2 million out of S$95 million in net interest income in 2025, up from S$15.6 million out of S$59.8 million in 2024.
GXBank generated some S$4 million out of S$5.6 million in net fee and commission income in 2025 – a reversal from 2024, when GXBank incurred a S$3.2 million expense.
Compressed margins, path to profitability
Still, observers cautioned that digital banks’ reliance on lending could come under pressure if margins tighten amid a shifting interest-rate environment and intensifying competition.
Ho Hean Chan, banking and capital markets assurance leader and partner at PwC Singapore, said: “Fed cuts could exert some downward pressure on Singapore digital banks’ loan yields.”
However, he noted that it will be factors such as credit demand, competition and inflation that are key for local loan interest rates, pricing and return. There is a danger of margin compression if funding costs fail to fall in tandem with rates or competition restrains loan pricing, he added.
While markets had earlier expected two US Federal Reserve rate cuts in 2026, analysts have since revised forecasts to no cuts for the remainder of the year amid heightened geopolitical tensions in the Middle East.
Mohit Mehrotra, financial services industry leader at Deloitte South-east Asia, said: “Looking ahead to 2026, digital banks will need to navigate an increasingly K-shaped economy across the Asean region.”
A K-shaped economy refers to various sectors recovering at different rates after a recession.
On the consumer front, higher inflation and unemployment rates amid an ageing population will affect wealth accumulation. On the business front, challenges around trade, energy and credit are putting pressures on clients’ balance sheets and income flows, he added.
Beyond balance sheet expansion, digital banks here will need to innovate on products and offerings to address the needs of the underserved segment, said Seah Li Yun, EY Asean banking and capital markets leader.
“Sustained business performance and returns will increasingly depend on growth in fees and commissions income from product and service offerings, alongside cost optimisation to maintain structurally lean operating models,” she said.
Profitability will be coming into increasing focus for digital banks in South-east Asia, as several are approaching the critical three-to-five year window, where the boards of parent companies want a credible breakeven path, noted Bain’s Nandy.
Globally, fewer than 5 per cent of digital banks are profitable, and most broke even within five to seven years.
“Achieving profitability through improved cost management and diversified revenue streams remains a key hurdle for digital banks,” said PwC’s Ho.
Trust Bank, a joint venture digital bank between Standard Chartered and NTUC, turned profitable in March – the first among the three digital banks to cross the threshold.
Unlike GXS Bank and MariBank, which operate under digital full bank licences that impose deposit caps and restrictions on certain banking services, Trust Bank does not face such constraints. It is able to offer the entire suite of banking products services from its launch.
Observers believe that digital banks will have to build out banking products beyond just deposits and loans to turn and maintain profitability.
“They need to develop sustainable monetisation models that extend beyond traditional banking services, such as wealth management, financial advisory and strategic partnerships within the broader financial ecosystem,” said Ho.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Could stablecoins be the future of money?
ST Engineering opens tech-focused aircraft maintenance facility in Changi; to create over 500 jobs

