

Singapore retail Reits, DPUs expected to be resilient over long-term: Morningstar
Singapore
WHILE the near-term distributions of retail real estate investment trusts (Reits) in Singapore might be affected due to the Covid-19 outbreak, these distributions should remain intact over the long-term period, according to a report by Morningstar Equity Research.
"In the near term, uncertainties remain as the duration of the coronavirus outbreak is unknown. However, in the long term, we expect distribution per unit (DPU) growth to be underpinned by population growth, a growing middle-income class, improving consumer sentiment, growth in the tourism industry and favourable supply-demand dynamics," wrote Morningstar equity analyst, Ken Foong.
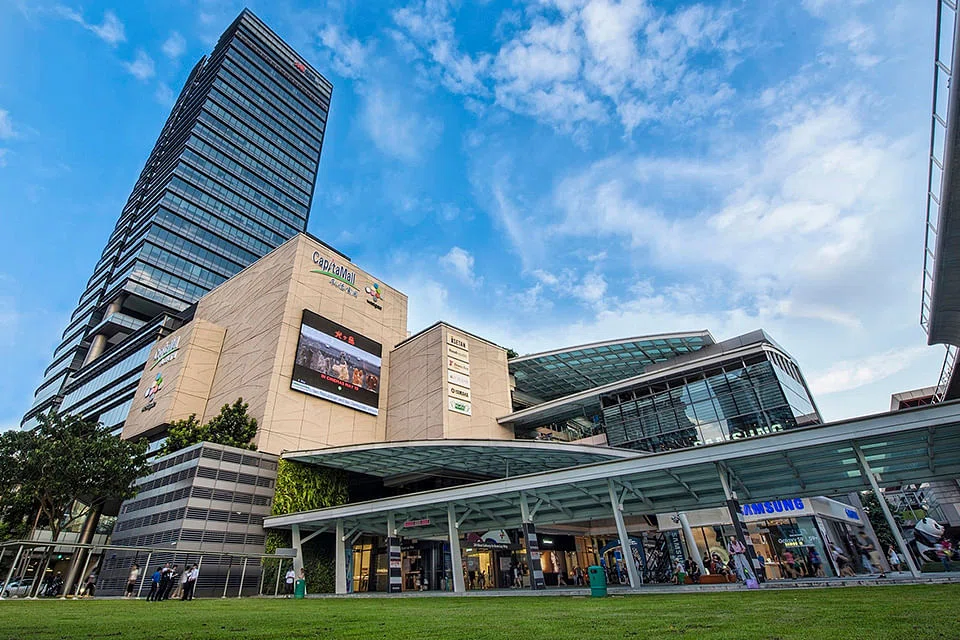
Three locally listed Reits are particularly attractive, in Morningstar's view: CapitaLand Mall Trust (CMT), Suntec Reit, and Frasers Centrepoint Trust (FCT).
Among the three, Morningstar favours CMT as it views the Reit's merger with CapitaLand Commercial Trust as a positive.
The merger is expected to produce a Reit juggernaut that is more resilient through market cycles and better able to take on integrated developments. Morningstar believes that commercial development is trending towards such integrated developments, or projects that incorporate both office and retail assets.
Meanwhile, Mr Foong expects Suntec Reit to be resilient through the market cycle due to its "diversified nature" comprising retail, convention centre and office space.
As for FCT, Morningstar believes that population growth along with the Reit's large residential catchment area could underpin long-term DPU growth. FCT's portfolio consists of seven suburban malls.
Morningstar's research team also covers Ascendas Reit, CapitaLand Commercial Trust, Keppel Reit and Mapletree Logistics Trust.
Overall, Morningstar does not expect the S-Reits under its coverage to cut their payout ratios to below 90 per cent. It noted, however, that there might be risks to DPUs in the near term. This could be the case especially for retail Reits, which may delay their distributions to conserve cash.
After factoring the various rental rebates announced by the retail Reits, as well as lower near-term growth rates and occupancy rates for all Reits, Morningstar has reduced its DPU estimates by 7.3 per cent for the 2020 fiscal year, and by 2.4 per cent for 2021.
It has also increased the uncertainty for FCT to "medium" from "low". With 100 per cent of its portfolio in the retail space, FCT is likely to be the most affected by the pandemic.
Morningstar said the balance sheets of these S-Reits remain sound and that they are better positioned compared with the period before the 2008/2009 financial crisis. As such, it does not anticipate any debt refinancing issues in the short-term.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Seatrium allocates S$200 million for new share buyback programme

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026
Stocks to watch: Mapletree Logistics Trust, Seatrium, Keppel DC Reit, Food Empire

