

Singapore's 'Popiah King' may anchor Pacific Radiance's S$120m rescue deal
Observers feel that at least for now, "high net worths" are likely to outnumber institutional funds in the O&M equity space
Singapore
SINGAPORE'S "Popiah King" may emerge as the next prominent business magnate in town to extend rescue financing to a listed company in the embattled offshore and marine (O&M) sector.
The Business Times understands that talks have been ongoing between Sam Goi - Singapore's 10th wealthiest on the Forbes Singapore Rich List 2017 - and Pacific Radiance over a deal that could see the tycoon anchor an equity raising exercise for the firm.
Mr Goi, who is also executive chairman of listed GSH Corp, is understood to be travelling and did not respond to BT's request for comments as of press time. Pacific Radiance also did not respond to a request for comments. But sources said that the founder of the world's largest popiah skin maker, Tee Yih Jia Food Manufacturing, may fork out the lion's share of some S$120 million worth of new equity being raised for Pacific Radiance. This new equity is conditional on the offshore support vessel (OSV) firm completing its debt restructuring exercise.
Mainboard-listed Pacific Radiance did not disclose the commercial terms agreed with its incoming equity investors. The group has been in voluntary suspension since February as it seeks to restructure its debts via a scheme of arrangement. Considering the structure of the firm's debt revamp, however, market watchers suggested that any proposed issuance of new shares is likely to be pegged at a discount to its last traded price of 10.4 Singapore cents.
The firm has indicated that its incoming investors will hold up to 65 per cent of its enlarged share capital. Its proposed debt revamp also called for forgiveness towards US$100 million of bank loans. In addition, the firm has said it will table a debt-to-equity swap proposal for holders of some S$100 million of medium-term notes.
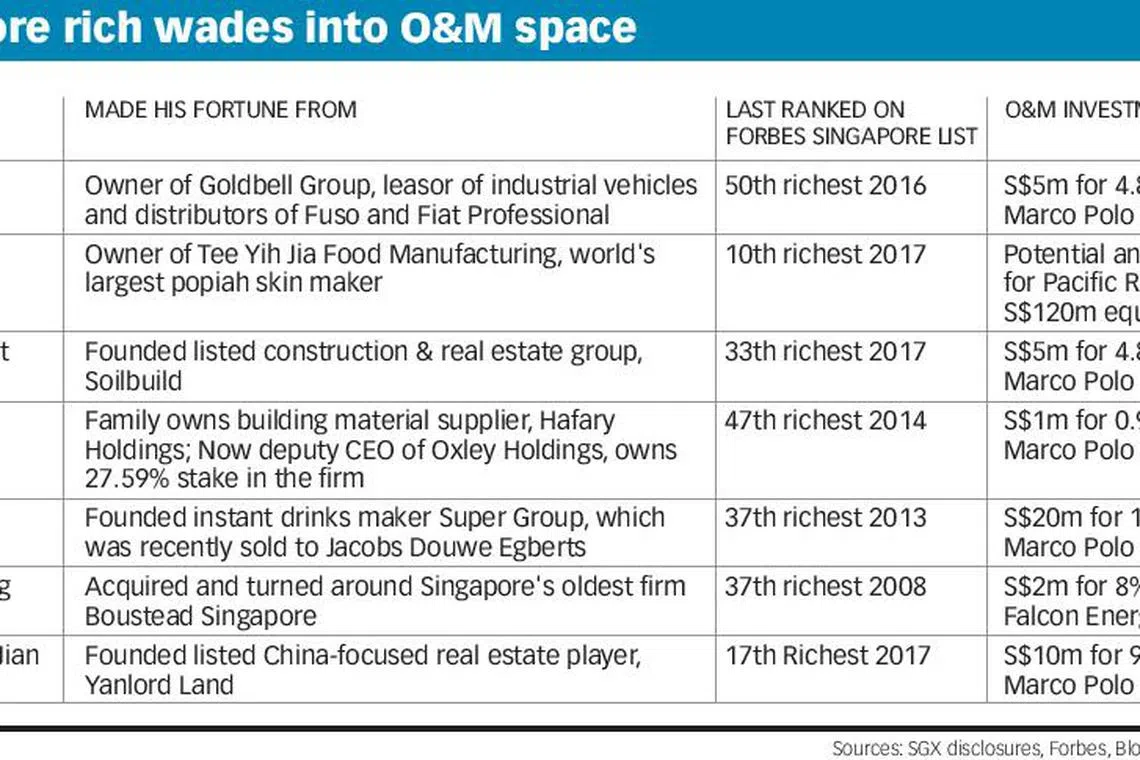
Once the new equity deal for Pacific Radiance is confirmed, Mr Goi would join the ranks of a small but growing group of homegrown tycoons who have waded into the O&M equity space during the sector's multi-year downturn.
Just two weeks ago, Boustead Singapore chairman and executive Wong Fui Fong emerged as a significant shareholder in another listed OSV-focused player, Falcon Energy Group (FEG) after forking out S$2 million for an 8 per cent stake in FEG. Speaking to The Business Times then, Mr Wong said he was responding to early signs of recovery in the oil and gas industry. "The O&G industry (that answers for the bulk of O&M order books) is recovering albeit slowly," he said.
FEG is in the midst of restructuring some US$80 million worth of bank loans on its books. A third OSV-focused group, Marco Polo Marine, has newly emerged from months-long corporate workout with the backing of S$60 million new equity raised from nine investors.
Five business leaders participated in Marco Polo's rescue financing deal. Marco Polo named the investment vehicles of Super Group's David Teo, Goldbell Group's William Chua and the founding chairman and CEO of Yanlord Land Group, Zhong Sheng Jian, among its investors. Also in the fray were Soilbuild's co-founder, Lim Chap Huat and Oxley Holdings' deputy CEO Eric Low. These high net worth individuals accounted for over half of the new equity recently injected into Marco Polo.
If the mix of investors seen in Marco Polo's rescue financing is anything to go by, high net worth individuals could make up the bulk of incoming equity being raised for Pacific Radiance.
Observers generally agreed that at least for now, "high net worths" are likely to outnumber institutional funds in the O&M equity space.
UOB Kay Hian's equity analyst Foo Zhi Wei said this outcome should be unsurprising because "high net worths" tend to take a longer term view of their investments. He noted that the mandates for large institutional funds are "shorter in terms of payback periods" for their investments. So this group of investors may not be keen to take position in the O&M equity space, given that the broader sector is expected to take several quarters to return to profitability.
Mike Meade, managing director of offshore broker firm M3 Marine, pointed out that what has clearly helped bolster interest in O&M equities is that oil prices have been "very, very stable". With prices now trending above US$70, even touching above US$80 recently, hopes of a more visible recovery in O&M contracting activity have been buoyed.
New investors are also encouraged by the willingness of some firms to dilute existing equity and their debt-holders to take haircuts, which helps bring book values more in line with current market conditions, Mr Meade said.
Mr Meade also flagged one important element surfacing in the restructuring of Singapore's O&M sector - that personal relationships with and trust in the existing management have also made a difference when cutting equity deals for firms facing financial duress.
In an earlier interview with BT, Darren Teo, who heads up Apricot Capital, David Teo's family office, said the trust placed in his childhood friend, Marco Polo CEO Sean Lee, is one key factor driving the Teos' investment in the firm. Boustead's Mr Wong also pointed to his trust in FEG's managing director PT Tan as a major factor behind his decision to fork out millions of dollars from his own pocket for FEG shares.
That said, not all institutional investors have stayed away from the O&M equity space. Azure All-Star Fund stood out as one exception for having emerged among the nine white knights identified for Marco Polo. The fund had pumped in S$2.5 million for its share of equity investment. Azure's CEO, Terence Wong, said he was "playing into the recovery story" for the O&M sector.
"I took (the) view that the market has more or less bottomed out," he told BT.






