

Size and sponsor matter for investors in new S-Reit listings, say observers
One analyst notes that many are wary of locally listed Reits with foreign assets, due to higher cost of capital and potential market downturn difficulties
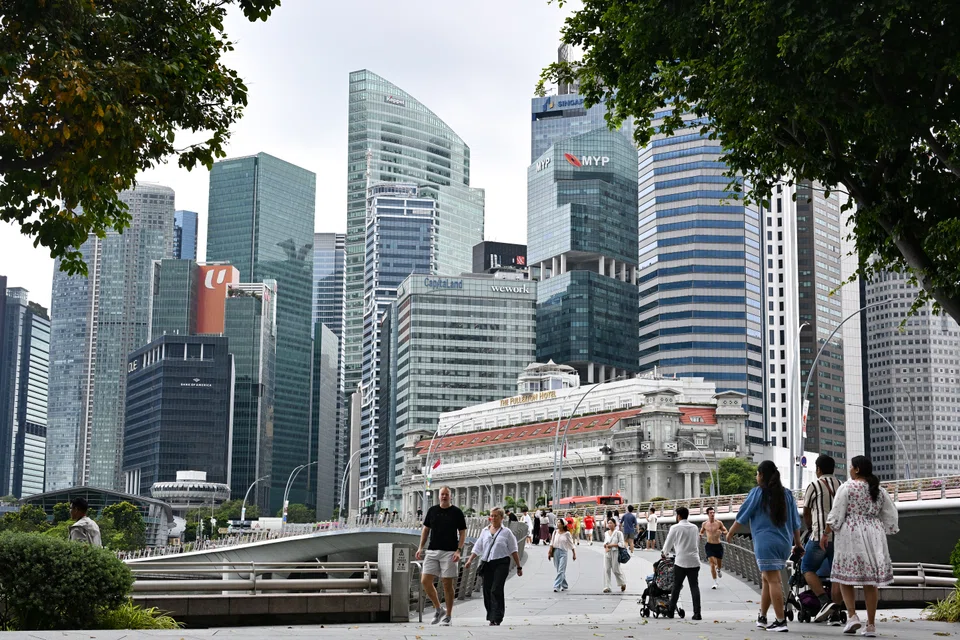
[SINGAPORE] Industry watchers are “cautiously optimistic” about the prospect of new real estate investment trust (Reit) listings on the Singapore bourse, noting that these additions will add diversity and variety to the Reit market here.
However, the new listings will need to have at least S$1 billion in market capitalisation and be sponsored by an entity with a good track record to generate investor interest, they added.
Several Reits are expected to list on the Singapore Exchange (SGX) this year. Japan’s Nippon Telegraph & Telephone (NTT) is said to be mulling the listing of a data centre Reit, while French property asset manager Praemia Reim is considering listing a healthcare Reit, media reports indicated.
Centurion Corporation also announced in January that it was exploring the establishment of a Reit comprising some of its worker and student accommodation assets on the SGX mainboard.
Size and sponsor
Vijay Natarajan, an analyst at RHB Bank Singapore, said that “having a meaningful portfolio size is important” to investors when it comes to new Reit listings, particularly for those with overseas assets.
He noted that investors here are wary of smaller Singapore-listed Reits – or S-Reits – with foreign assets, since they have a higher cost of capital and may struggle to navigate severe market downturns.
These Reits have also been affected by macroeconomic challenges in countries where their assets are located. S-Reits with China assets, for instance, have performed poorly due to the country’s property-sector crisis.
Natarajan predicts that new Reit listings with overseas assets will need to be at least S$1 billion in size, and backed by sponsors with a strong track record to attract domestic investor interest.
A quality sponsor, he added, is one with operational experience and familiarity with “trading, selling and managing real estate assets over a period of at least 10 years, particularly in markets where the sponsor’s assets are located”. They must also be able to enhance the quality of the assets over time.
Derek Tan, head of regional property research at DBS Group Research, agreed. “Nobody will invest if the sponsor is unknown,” he said.
To that end, some of the potential new listings can be considered “quality” listings, said market watchers.
NTT, which has years of experience in operating data centres and has several assets in Japan, plans to raise as much as US$1 billion in its initial public offering (IPO) here.
Meanwhile, Praemia Reim’s possible healthcare Reit could raise “several hundred million US dollars”, based on media reports. Half the assets managed by the company are in the healthcare and education sectors in Europe.
A listing sponsored by Centurion would also “pique investor interest”, said DBS’ Tan.
The dormitory operator, which has yet to specify the size of its potential IPO listing, has experience developing and managing worker accommodations in Singapore, as well as student accommodations in countries such as Australia and the United Kingdom.
More variety in Reit market
Lee Wei Hock, deputy assurance head at EY Singapore, said that the listing of larger Reits will bring greater variety to the domestic Reit market.
Such activity will also help to attract capital flows – especially from global institutional investors – and promote market buoyancy, benefiting Singapore’s overall Reit market.
Liu Miaomiao, research analyst at Phillip Securities Research, said that the listing of larger Reits alongside the possible exit of smaller ones could improve the overall quality of the sector.
Singapore’s position as a leading Reit hub in the region can be reinforced in tandem with policy initiatives to revive the equities market, such as the recently announced S$5 billion Equity Market Development Programme, she added.






