

SPH open to considering all offers that are better than Keppel's: CEO
Claudia Tan HS
WHILE Keppel Corp’s BN4 final offer of S$2.351 per share is currently the best on the table, the door is not closed for Singapore Press Holdings (SPH) T3 9 t o consider superior offers, said chief executive officer Ng Yat Chung in a briefing on Wednesday (Nov 10).
In the event that there is a better offer, Ng said the SPH board would go into the upcoming scheme meeting with the appropriate recommendations and would not be obligated to recommend Keppel's offer.
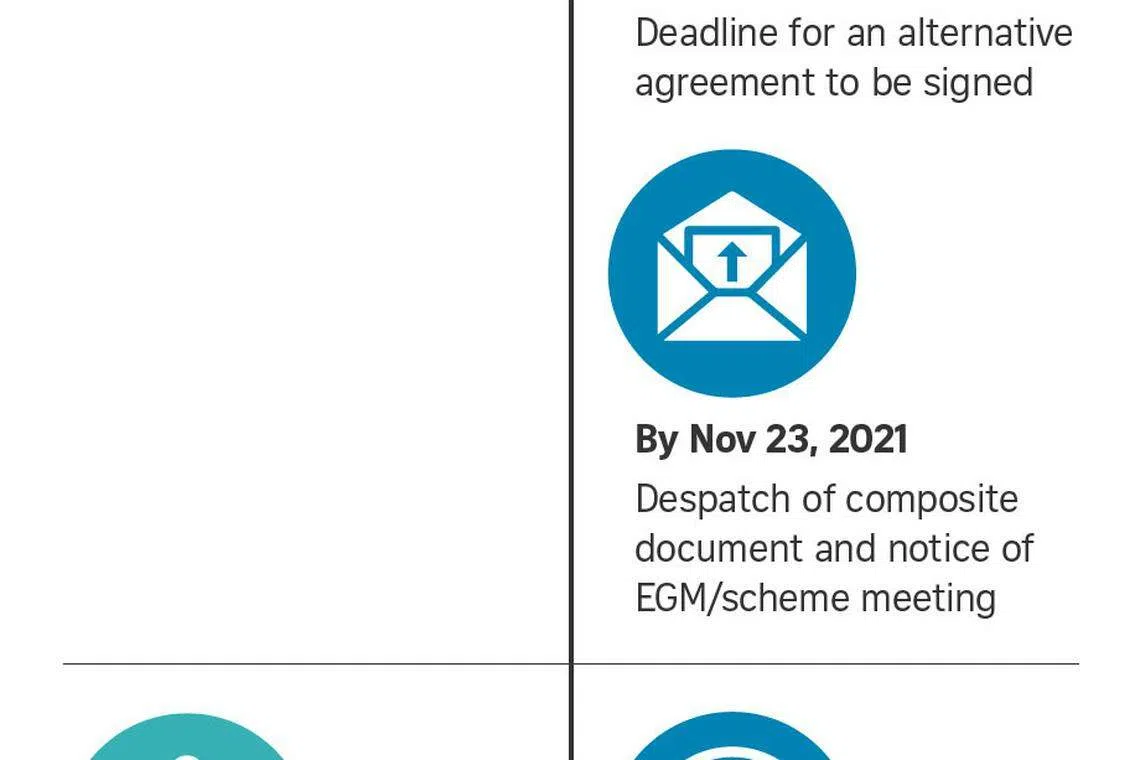
As part of the agreement with Keppel, SPH will hold a scheme meeting by Dec 8 to give shareholders the chance to vote on Keppel's offer. SPH, which publishes The Business Times, is also permitted to enter into another agreement by Nov 16 with any other party that wishes to offer a competing scheme.
Keppel had late on Tuesday (Nov 9) upped the cash component of its initial offer by S$0.20 per share to S$0.868 per share. SPH shareholders will still receive 0.596 Keppel Reit units (valued at S$0.685 as at Nov 9) and 0.782 SPH Reit units (valued S$0.798 as at Nov 9) per SPH share.
An investor holding 1,000 SPH shares for a 3-year period between end-Oct 2018 to end-Oct 2021 would have received S$245 in dividends, Bloomberg data showed.
Meanwhile, holding 596 Keppel Reit units and 782 SPH Reit units over the same period would theoretically have given an investor around S$200 in dividends.
The previous offer of S$2.099 per share valued the Keppel Reit component at S$0.715 and the SPH Reit component at S$0.716.
Units of SPH Reit SK6U dipped 2.7 per cent to S$0.89 on Aug 3 after the Keppel offer for SPH was first announced, but have gained significantly since a rival offer emerged. Units of SPH Reit last traded at S$1.02 on Nov 9.
Units of Keppel Reit K71U , too, fell 5.8 per cent to S$1.13 on Aug 3 following the Keppel offer announcement. They have since risen to S$1.15 as at Nov 9 but are still below where they were before the announcement was made.
SPH received a potential offer of S$2.10 per share by Cuscaden Peak - a consortium backed by Hotel Properties (HPL) H15 , businessman Ong Beng Seng, and 2 Temasek-linked entities, CLA Real Estate Holdings and Mapletree, in late October.
"If Cuscaden or any other party concludes with us an alternative implementation agreement for a scheme that is superior to Keppel's final offer... and if the IFA (independent financial advisor) believes the alternative proposal is the better value, the board would act on the recommendation accordingly," Ng said.
Cuscaden or any interested parties will therefore have the opportunity to conclude an implementation agreement for a scheme that is superior to Keppel's offer by Nov 16 and till Dec 1 if they want to make a general offer.
Ng said that SPH had been in talks with both Cuscaden and Keppel with a view to improve their respective offers.
The company is still actively engaging with Cuscaden to provide them with the due diligence and to work on a draft implementation agreement.
In Keppel and SPH's joint announcement on Tuesday (Nov 9), it was indicated that the scheme meeting for Keppel's proposal shall be held prior to any scheme meeting for any competing offer to be implemented by way of a scheme of arrangement.
Ng said SPH is obliged to hold the scheme meeting whether or not the directors eventually recommend the Keppel proposal. He noted that even if Cuscaden comes out with a superior offer, the practical timeline of getting the regulatory approval would also take several weeks and it would be weeks after the Keppel scheme meeting.
When asked on the premium required for a cash and stock offer to be seen as equal to an all-cash offer, Ng said he would leave that to the IFA to determine.
He added that there are various factors that the board must take into account in deciding the best offer for shareholders, including the offer price, structure of the deal, regulatory requirements as well as the ability to finance the offer.
Cuscaden presented a strong offer as an all-cash offer has a cleaner structure. The consortium has also obtained certain in-principle regulatory approvals and have the ability to finance their offer, Ng noted.
All else being equal, an all-cash offer with a chain offer for the Reit might be agreed to be a much better structure than the current Keppel offer, said Ng.
"But we still have to look at what the price is and what the regulatory requirements are, and as of now, Keppel definitely is ahead on this one, because they basically cleared everything," he added.
If a superior competing offer to Keppel’s proposed privatisation of SPH is successful, a break fee of S$34 million would be payable by SPH to Keppel.
Justin Tang, head of Asian research at United First Partners, said: "Given that the Keppel offer is now final, the onus is on the Cuscaden consortium to match or better the offer."
"It (Keppel's revised offer) is somewhat surprising only because of the common majority shareholder. However from a strictly commercial perspective, it makes sense given the quality of SPH assets," said Tang.
"SPH shareholders will be the happiest of the lot should Cuscaden match," Tang added.
CGS-CIMB analysts said in a note on Wednesday (Nov 10) that they do not discount the possibility of more competing offers for SPH, as the revised offer by Keppel is still at a 10 per cent discount to their equity value of S$2.64 per share for SPH.
The analysts also observed that SPH Reit and Keppel Reit units have appreciated since the possible offer by Cuscaden, but there may be short-term pressure for the Reits.
“We expect the revised offer by Keppel, which used the units of both Reits to part fund the acquisition, to cause price overhang for both Keppel Reit and SPH Reit,” they said, but added that if the proposed privatisation by Keppel materialises, a potential merger of the two Reits and higher free float would serve as re-rating catalysts.
UOB Kay Hian analyst Llelleythan Tan noted that the revised Keppel offer is more appealing, being at a higher consideration than Cuscaden’s all-cash deal.
He added: “Given the high quality assets that SPH has in the UK and how peers in the UK are trading at 1.2 times price-to-book, Cuscaden may come back with a better offer if they reckon these assets suit their portfolio.”
But Brian Freitas, an analyst who publishes on Smartkarma, said in a report that he does not expect Cuscaden to increase their cash offer to match Keppel's offer.
"Even if they do, an increase in stock prices of Keppel Reit and SPH Reit could take the value of the Keppel offer even higher," said Freitas.
READ MORE:
- BT Explains: Keppel's counter offer for SPH
- HPL, Ong Beng Seng, Temasek units CLA and Mapletree in rival offer for SPH
- BT Explains: Why is Ong Beng Seng interested in SPH?
- Keppel makes surprise S$2.2b bid to privatise SPH
- BT Explains: Keppel's bid to take SPH private






