Still a long road to recovery for small O&M firms
Singapore
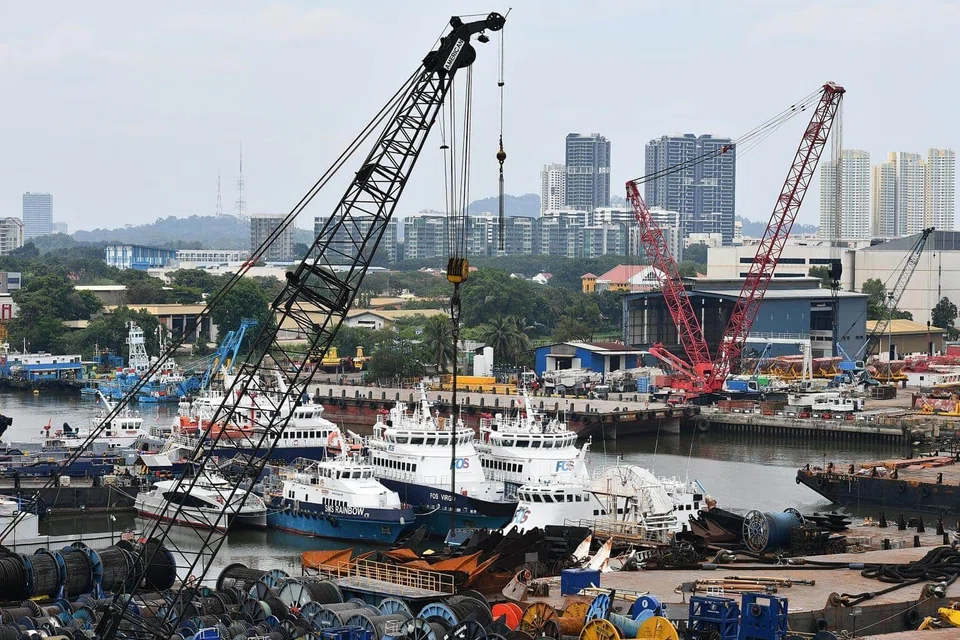
BARGAIN-hunting in the small capitalised offshore and marine (O&M) equity market appear to have returned as healthier oil prices lift the hopes of a recovery in the sector.
Still, it is a rough ride ahead, so investors have to go beyond conventional financial analysis if they truly want to identify the winners from the losers in this downturn, analysts said.
To begin with, KGI's analyst, Joel Ng, noted that price surges among those that have completed debt revamps might well be "short bursts of euphoria".
Take the case of Marco Polo Marine and Ezion. These firms have struggled to retain their early gains after resuming trading on the Singapore Exchange. On the flip side, the jury is still out on Nam Cheong, which is still holding above water five weeks after completing its debt revamp.
Other small-cap stocks also seemed to be bottoming out. The SGX's My Gateway noted in September that selected counters - Vallianz Holdings, PACC Offshore Services Holdings (POSH) and Mermaid Maritime, to name a few - had rebounded from their 52-week lows.
That said, performances of small- to mid-cap stocks are at best a mixed bag. Most are still way off the peak levels reached before a collapse in oil prices triggered a multi-year sectoral downturn.
Also not helping is the fact that financial metrics have gone out of whack for several O&M counters. Nam Cheong has slipped into negative equity after taking a massive impairment and completing its corporate revamp. Its management flagged a one-time gain from debt forgiveness that would surface in its Q3 report. Such non-recurring gains had previously lifted Marco Polo and Ezion's bottom lines.
To be fair, these small-cap players deserve credit for having taken steps to align with new norms emerging in their core markets.
Most are substantially exposed to the offshore support vessel (OSV) segment that is being pulled back by vast overcapacity. A handful, like Mermaid Maritime and Pacific Radiance, are also active in the subsea sub-sector that is reportedly staging a faster recovery. But M3 Marine's managing director Mike Meade noted that in the Middle East and most parts of Asia, where most Singapore-based subsea players are active in, rates are still trending at depressed levels.
Taking in all these factors, equity analysts offered a few indicators that investors should look out for in the financial reports.
First, only those that have gone deep enough with asset impairments stand to ride through the rest of this downturn. UOB Kay Hian analyst Foo Zhiwei considered those that have turned in gross profits as likely to have taken adequate asset writedowns. He did not comment directly on individual firms, but a BT scan of the last reported O&M results indicated at least three - Ezion, Pacific Radiance and Falcon Energy - were still loss-making at gross levels.
Second, firms have to secure forgiveness from their creditors so as to back their asset writedowns. Those not granted debt-to-equity conversion or haircuts for their liabilities will not be able to free cash flows from debt repayments, analysts said.
Mr Foo cited OSV owner-operator and shipbuilder, ASL Marine and yard operator AusGroup as two likely examples. Both firms had to seek consent from their bondholders once again to push out principal maturity for outstanding bonds.
Mr Ng suggested that as a rough guide, debt-to-equity ratios should not exceed 0.5 time after debt revamps. One red flag would be liabilities exceeding equity on the books, he added. Several small-cap O&M counters that made the My Gateway's list - Ezion, Valliance, Falcon Energy and POSH ) fall under this category.
Still, firms with stakeholders' backing can emerge as exceptions to the rule.
Mr Foo noted that even with net gearing of over 100 per cent, Ezion is believed to be "viable and unlikely to fold". POSH "continues to receive the favour of bank lenders because it has a financially well-endowed parent company".
At the end of the day, a deleveraged balance sheet is no guarantee of economic viability. Mr Foo noted that even with a manageable debt pile now, Marco Polo Marine is still loss-making at operating level at the end of its third quarter, before taking in a foreign exchange gain.
Any interested investor has to face up to this harsh reality - while their stock valuations may have passed all-time lows, many small-cap plays still need plenty of time and space to make their way to the light at the end of the tunnel.