

The sun shines again on Europe: BlackRock
Strategist welcomes stock-picking opportunities from domestic political reforms
Singapore
DOMESTIC and emerging market (EM) demand are solid drivers in Europe right now, with political changes offering investment opportunities, not risk, for savvy stock-pickers.
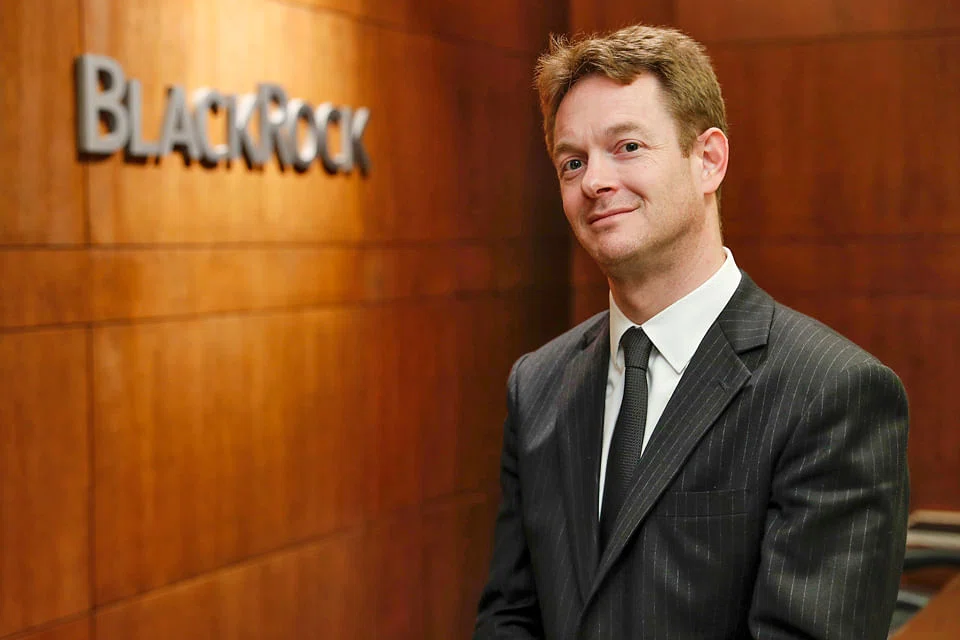
That is BlackRock product strategist Matt Williams' take, at least. "I was in this region the Monday after Brexit, and a lot of our clients were quite nervous," said Mr Williams, who is from the asset management firm's European equities team.
"And I think to be fair, markets were generally nervous. And if you look back, that turned out to be the signal for a very decent buying opportunity. I do think that, when politics happens, you need to go back to fundamentals, look at the companies . . . Is it really impacted or not by what just happened politically? And go from there."
He added: "When politics happens, sometimes those companies could be affected - but a lot of the time, all that happens is that we get to buy a really good company cheaper than we should be able to achieve."
Turning to another example, he brought up the long-running saga of the Greek debt crisis: "The politics around Greece made markets nervous, but a lot of European companies have pretty much minimal exposure to Greece, so their earnings weren't massively impacted directly.
"However, the greater degree of political risk might have caused client capex to fall a little bit, so it could impact them that way. But the major impact was the rising political risk premium, therefore bigger equity risk premium, therefore valuation impact. So it was much more about that."
Asked what danger signs lie ahead, he noted: "You haven't really seen significant wage inflation come through within Europe. It's something we keep a very close eye on."
As for sluggish inflation - a plague on markets worldwide - Mr Williams said: "From a European perspective, we still have quantitative easing, we still have an accommodative stance. We still have effectively negative interest rates, and so the world is very different to anywhere else in that regard."
At the same time, he puts good money on the climate having improved since the Brexit vote to leave the union, declaring: "We are at a very different level of potential political risk than we were at the start of 2017."
One bright spot, to him, is that "it's very clear that political reform in the eurozone is gathering pace", with a shared commitment to work together in arenas such as defence and banking.
Political moves at both the European and country levels - and a dimming of eurosceptic sentiment - have led him to declare: "In a way, Brexit has acted as a catalyst to make Europe work more efficiently, to make it work more effectively. And you've seen some of that in terms of the response from the European Union, in terms of their reforms going forward."
He added that political reforms lead to market reforms, which could yield lower portfolio volatility and stronger performance. He pointed to how centrist French leader Emmanuel Macron has embarked on a slew of changes, from slashing the wealth tax to shaking up pension plans.
"So when you think about the opportunities that exist within France, from the potential for labour market reform on the one hand, and also the potential for the divestment of government stakes in industries - it's actually pretty positive."
He added: "The earnings support looks positive and well diversified in terms of which markets are driving it. And the valuation is attractive on a relative basis. That seems pretty okay, from my point of view."
When it comes to earnings drivers, he is keen on the lift that the continent could get from emerging markets. "The fastest-growing recovering part of the world was emerging markets, and so the European companies that grew earliest would have been companies with EM exposure," he said. "But what you have as well now is solid but not super-normal GDP growth in Europe domestically.
"So, if you like, two-and-a-bit years ago, you'd have been starting out with EM exposure, and then you add in some domestic exposure as those conditions get better. And we keep talking about end markets, but it really is company-specific in terms of who actually has good exposure and does intelligent things well."
He argued that it is "far too simplistic" to say that a stronger euro will dampen European stocks because of the hit to exports. He elaborated: "Clearly, a rising euro does make a European manufactured good less competitive overseas. That's obvious. But that assumes no pricing power, and . . . talking about the likes of Gucci or Louis Vuitton or any of those luxury good type names, clearly there is pricing power that needs to be considered. It also varies differently in terms of the industry, and a good example is to talk about the drinks industry because if you think about the brewers of beer, they have the ability to manufacture locally, where they sell it."
Mr Williams, who previously covered European industrials for Capital Group in London, added that the sector "is a very big sector in the European universe", with some segments getting a lift from global cyclicality and others - such as transport infrastructure players like Italy's Atlantia - banking more heavily on domestic demand. "So you can position your portfolio whichever way you want."






