

Suntec Reit eyes another S$100 million in strata divestments in 2024 as it targets sub-40% gearing
Raphael Lim &
Mia Pei
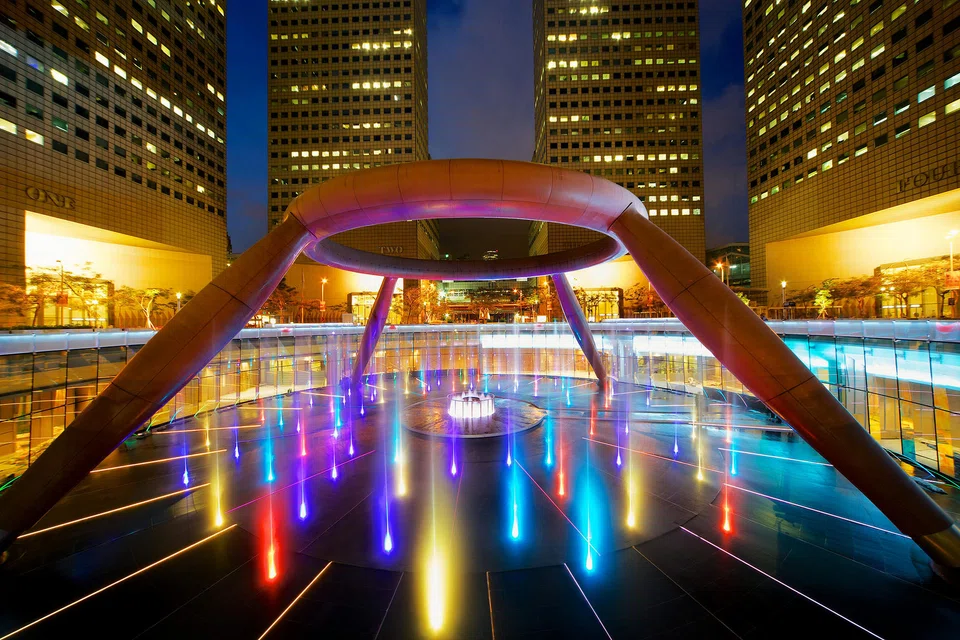
SUNTEC Real Estate Investment Trust (Reit) is eyeing further divestments of Suntec strata office units in FY2024, building on earlier divestments last year, as the manager aims to reduce gearing.
Chong Kee Hiong, chief executive of the manager, said at an earnings briefing on Wednesday (Jan 24) that the manager is guiding for around S$100 million in Suntec strata sales in the current financial year.
“If I can sell more, then I would, but I am not going to reduce the price to move the number of units divested,” he said, noting that S$100 million is not a firm target, but just a guidance which the manager believes is reasonable.
The Reit divested S$94.4 million of strata units in 2023, with the proceeds used to pare down debt. The price of divested units in 2023 was above S$3,300 per square foot (psf), higher than the book value of around S$2,600 psf, Chong noted.
The transactions were also accretive to earnings, as the divested yield was lower than current borrowing costs.
Chong added that in an environment where asset yield is lower than bank borrowing costs in local currency, it makes sense to deleverage. “Our target is to bring it down to 40 per cent or below,” he said. Suntec Reit’s aggregate leverage ratio as at December 2023 stood at 42.3 per cent, down from 42.4 per cent a year earlier.
All-in financing costs rose to 3.84 per cent per annum from 2.94 per cent in FY2022, and the manager expects financing costs to climb further this year. Its adjusted interest coverage ratio for FY2023 was two times, down from 2.4 times the previous year.
Chong noted that higher gearing would make more sense in a low interest rate environment, but said he does not expect this to happen anytime soon, unless there is a global recession. He added that the manager is not considering any fundraising to pare down debt.
The Reit’s distribution per unit (DPU) for the second half of 2023 fell 10.2 per cent to S$0.03659, compared with S$0.04074 the year before.
The manager noted that operational performance of the Singapore office, retail and convention portfolios continued to improve, but the Reit still faced higher financing costs and lower contributions from overseas properties.
Gross revenue was up 6.6 per cent to S$238.4 million for the period, from S$223.7 million.
After deducting property expenses of S$78.6 million, Suntec Reit’s net property income (NPI) fell 1.8 per cent to S$159.8 million in H2 2023, down from S$162.8 million in the prior-year period.
Finance costs, mainly interest expenses, climbed to S$89.8 million, up 3.2 per cent from S$86.9 million in H2 FY2022.
Distributable income for the half-year period dropped 9.4 per cent year on year to S$106.3 million from S$117.4 million.
For the full year, DPU fell 19.7 per cent to S$0.07135, from S$0.08884 in FY2022. Distributable income fell 19.1 per cent to S$206.8 million, compared with S$255.5 million a year earlier.
Suntec Reit’s distribution in both FY2022 and FY2023 included a capital distribution component – amounting to S$23 million each year – relating to the divestment of Park Mall in 2015, which has now been completed.
“Going forward, we have to look at (capital distribution) on a case-to-case basis,” Chong noted. “We are in this environment where interest rates are still uncertain, gearing is still not ideal, so we will take it one step at a time.”
While the Reit has guided to divest S$100 million in assets this year, Chong added that they would be in a better position to distribute if they can divest more.
The manager is also eyeing the divestment of mature assets in Australia, but the market there is currently quiet, making it less meaningful to set a target.
In terms of acquisitions, Chong said that it may be more difficult in the current environment, given that any acquisition would be benchmarked against the cost of funding of both debt and equity.
Gross revenue for the full-year period increased 8.3 per cent to S$462.7 million, while NPI eased 0.8 per cent to S$313.2 million.
The Reit’s Singapore office and retail portfolio posted higher gross revenue amid positive rent reversion.
The manager expects rent reversion for the Singapore office segment in 2024 to be weaker than the double digits recorded in 2023, but to remain above 5 per cent. It noted that geopolitical tensions and economic headwinds continue to weigh on the office market with few discernible key demand drivers in sight.
Meanwhile, Chong said the manager is eyeing rent reversion in the 10 to 15 per cent range for the retail segment, lower than 21.8 per cent last year.
Suntec Reit’s convention business posted a rebound in the second half of 2023, recovering to pre-Covid levels. The manager said higher dividend contributions from Suntec Convention are expected.
“Going forward, though we expect better operating performances from the Singapore portfolio, the elevated interest rates and leasing downtime for the vacancies at 55 Currie Street, Southgate Complex and The Minster Building would continue to impact our distributable income,” Chong said. 55 Currie Street and Southgate Complex are located in Australia, while The Minster Building is in the UK.
Portfolio valuation for the full year remained stable year on year at around S$11.9 billion. Assets in Singapore had stronger valuations, while the UK and Australia portfolio slipped 10.2 per cent and 4.5 per cent, respectively, due to cap rate expansion.
Net asset value per unit slipped to S$2.10 as at Dec 31, 2023, down from S$2.12 a year earlier.
Units of Suntec Reit were up 1.7 per cent or S$0.02 to S$1.22 as at 1.54 pm on Wednesday.






