

Tech, banks in focus for Q1 reporting season, with economic weakness likely to weigh on earnings
TECHNOLOGY companies could report weaker sales for the first quarter of the year, said analysts ahead of the financial reporting season that begins this week.
The banks, too, will be closely watched for signs of a peaking in net interest margins (NIMs), as the pace of interest rate hikes by central banks looks set to slow.
Phillip Securities’ head of research Paul Chew expects a decline in sales within the semiconductors and electronics sectors, as customers lower their forward orders. “The steepness of the decline is less clear,” he said, adding that there might be potential downside surprises for the electronics sector.
Similarly, Lorraine Tan, director of equity research in Asia for Morningstar Investment Adviser Singapore, deduced from the results posted by global companies so far that “continued weakness in the tech space, especially driven by weak smartphone sales”, is expected.
But she added that share price action could be limited following Samsung’s comments that it will cut production of memory chips, fuelling expectations that this will help support pricing and allow excess inventory to be absorbed.
Lim Siew Khee, head of CGS-CIMB’s Singapore research team, and her fellow analyst Lock Mun Yee, expect AEM Holdings , Grand Venture Technology , Venture Corporation , Frencken and Nanofilm Technologies International to be “weaker” on a semiconductor industry slowdown.
But ISDN Holdings and Aztech Global could have a “better” year-on-year showing, benefiting from the recovery of activities in China. Economic activity in China was severely curtailed until recently, due to the country’s policies to manage the spread of Covid-19.
Banks in focus
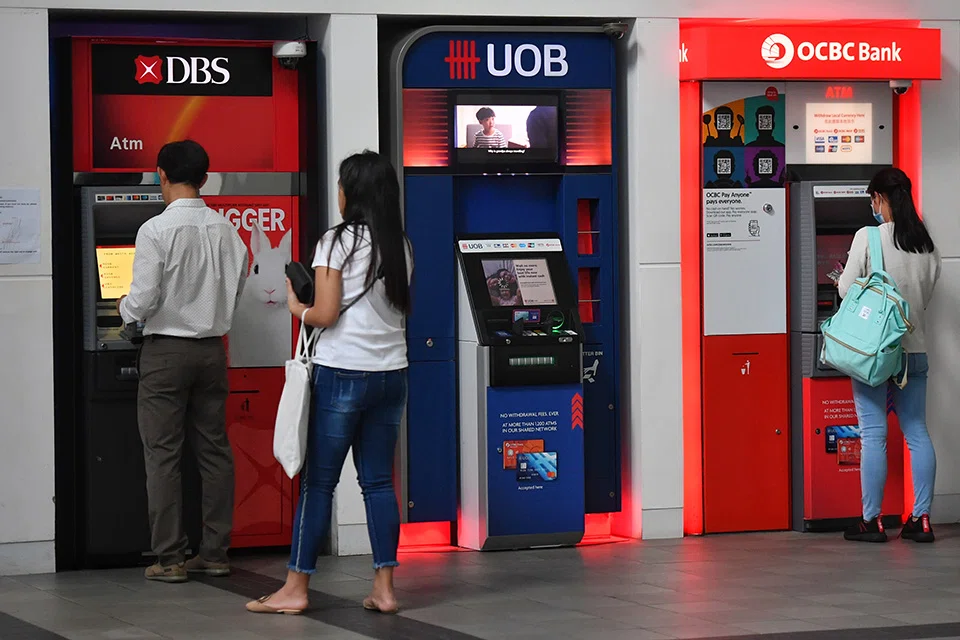
The financial results of the banking trio will be keenly watched in the aftermath of the recent banking turmoil in the West. “Based on the Singapore Exchange (SGX) fund flow data, there have been eight consecutive weeks of net outflows from institutional investors in the financial sector,” said IG market strategist Yeap Jun Rong. This suggests some investors think the sector’s earnings potential is peaking.
Said Yeap: “The Q1 earnings may continue to show resilience, but the outlook from the banks will be in focus as well, in light of an impending rate pause from the Federal Reserve and further downside risks to growth conditions ahead.”
Phillip’s Chew, too, expects the banking trio will “enjoy earnings growth driven by a jump in net interest income and modest recovery in fee income” for the January-March quarter.
“The unknown is guidance for interest margins as more deposits shift out of CASA (current accounts, savings accounts) and competition for deposits rises. Other areas to monitor include the opportunity or fallout for wealth management, post the Credit Suisse takeover by UBS,” said Chew.
Colin Low, assistant manager of the research and portfolio management team at FSMOne.com, forecasts rising credit costs.
“We think loan growth could see a slowdown as economic growth moderates,” Low said, although he expects that NIMs and income should remain supported. “We expect more rate hikes and no rate cuts by the Fed this year.”
The CGS-CIMB analysts, meanwhile, expect the banks’ earnings from wealth management could surprise on the upside, while their asset quality and outlook will be key price drivers.
Post-pandemic adjustments
Several stocks could see significant impact from a removal of policies to deal with Covid-19.
As mainland Chinese are able to resume international travel, they could help boost demand for real estate – whether residential for own use or investments, or office and commercial to have a wider Asean business presence – said Matthias Chan, SAC Capital’s head of research.
Carmen Lee, head of OCBC Investment Research, said property sales, take-up rates and rental rates still look healthy despite higher mortgage rates. This should provide some interest to the property sector, even as high mortgage rates could weigh on sentiment, she added.
Singapore Airlines (SIA ), which has been posting robust operating statistics for its passenger segment, is one of the issuers that will be delivering its full-year financial results this season.
Morningstar’s Tan will be looking out for how yields are holding up with more capacity returning. “The global slowdown coupled with added bellyhold capacity has been sending cargo yields lower. It would be interesting – although negative to SIA – to see if we start to see some plateauing in passenger demand on more cautious spending.”
CGS-CIMB expects inflight caterer and ground handler Sats to return to profitability, while SIA should deliver stable quarterly earnings.
Interest rates and mounting risks of a recession are key macro factors that would have weighed on Q1 earnings. But analysts are mixed on whether corporate earnings would have upside or downside surprises.
Upside surprises might be in store for the services industries, including hospitality, leisure and retail, said Phillip’s Chew.
SAC’s Chan noted that the “overwhelming preoccupation” in the past quarter was inflation and the attendant rising cost of credit. But Singapore corporates have been prudent in their capital management, he said, and financial stress is thus unlikely to be systemic.
“Judging by the full restaurants and impressive take-up rates at recent property launches, Singaporeans in general have healthy balance sheets. As long as employment rates remain strong, listed companies catering to local consumption should remain resilient,” added Chan.
IG’s Yeap noted that existing negative sentiments and beaten-down expectations provide room for positive surprises.
And OCBC’s Lee said earnings have already seen several rounds of downward adjustments since the start of the Russia-Ukraine war and the resultant high inflationary environment. “We believe that corporate earnings have already priced in some of the negatives including slower demand and higher costs, which also mean that margins are likely to remain under pressure,” she said.
As the lagged impact of last year’s synchronised monetary tightening works through, however, FSMOne.com’s Low expects global growth to slow further and hit sales conditions. “While costs for companies have moderated, largely as material costs ease, it is not declining fast enough and remains high.”
The CGS-CIMB analysts noted also that many companies will be offering only business updates instead of a full set of results in the upcoming earnings reporting season, which means there might be little in the way of surprises in either direction.






