StarHub EPL rights could pose short-term cost challenge: Analysts
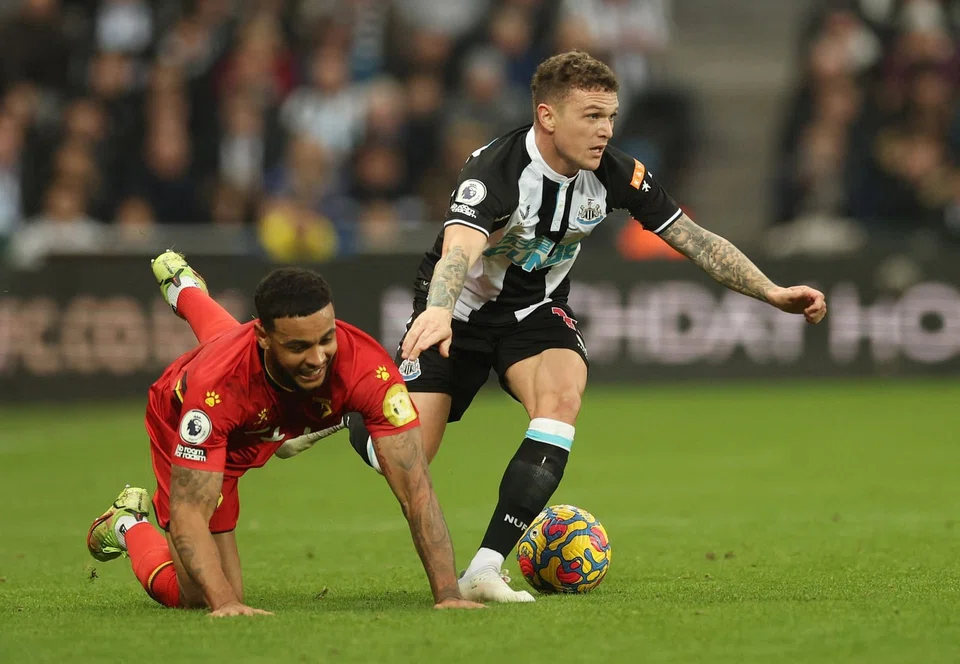
SHORT-TERM cost challenges and potential cross-carriage measure regulation could put a dampener on StarHub's recent exclusive partnership with the English Premier League (EPL) for 6 years of broadcast rights, said analysts.
Citi Research's Arthur Pineda and Luis Hilado noted in a report on Monday (Feb 21) that the cost of the broadcast rights had not been factored into the company's earlier earnings before interest, taxes, depreciation and amortisation (Ebitda) margin guidance.
At its earnings call for FY2021 on Feb 11, StarHub had guided for lower Ebitda margins of at least 20 per cent for FY2022 and 23 per cent for FY2023 to support its Dare+ initiatives, which aim to grow gross profits and cut costs.
Additionally, the analysts noted that if the EPL rights were subject to the Infocomm Media Development Authority's cross-carriage measure, the exclusive content will also have to be offered to telco rival Singtel for broadcast, reducing StarHub's competitive edge.
"Having direct control of the content could come with more package or bundling flexibility and head starts but the revenue accretion beyond normal subscription revenues will likely be more a medium-term development whereas the costs will come sooner," they said, adding that FY2023's margins could see further pressure.
Still, RHB analysts noted that the cross-carriage measure would likely have prevented StarHub from overpaying for the rights. StarHub has not disclosed how much it spent to acquire the broadcast rights.
DBS analyst Sachin Mittal also noted piracy was a big issue that StarHub had to contend with previously as football fans turned to free streaming sites online.
However, piracy-fighting technologies, such as the blocking of code sharing, could push more people to subscribe to StarHub's EPL broadcast.
Mittal, RHB's analysts and Maybank Securities Singapore analyst Kelvin Tan also pointed out that there could be potential for the broadcast rights to play a role in driving adoption of StarHub's "Infinity Play" set of services that it has been growing. These services include Disney+ and Nvidia's GeForce NOW game streaming service.
StarHub will offer additional services on top of the broadcasts, such as on-demand match replays and split screen viewing with performance statistics.
"We need to see if, with a combination of their over-the-top platform and cloud gaming platform, StarHub can acquire more customers," Mittal said.
Tan also believes that StarHub could charge a higher premium for their HomeHub+ and TV bundles, which could potentially impact margins. Making the broadcasts available through its over-the-top platform could further expand the telco's reach beyond its existing customer base as well.
This comes as analysts had earlier downgraded the company's target price as earnings cuts make it less compelling in the near-term as the company invests more into its longer-term strategy.
"With the stock expected to only provide its floor dividend per share of S$0.05 this year, there is no attractive proposition yet at current levels," Citi analysts said.
Mittal said that he prefers Singtel over StarHub as it offers a 9 per cent earnings compound annual growth rate over the next 2 years. This will be driven by recovery in the telco's Australia and Singapore business as well as growth driven by its Indian associate, Bharti Airtel, as it benefits from tariff hikes.
Shares of StarHub traded at S$1.27 on Tuesday, down S$0.04 or 1.6 per cent on Tuesday (Feb 22).
READ MORE: