

Worst could be over for semiconductor players after dismal H1
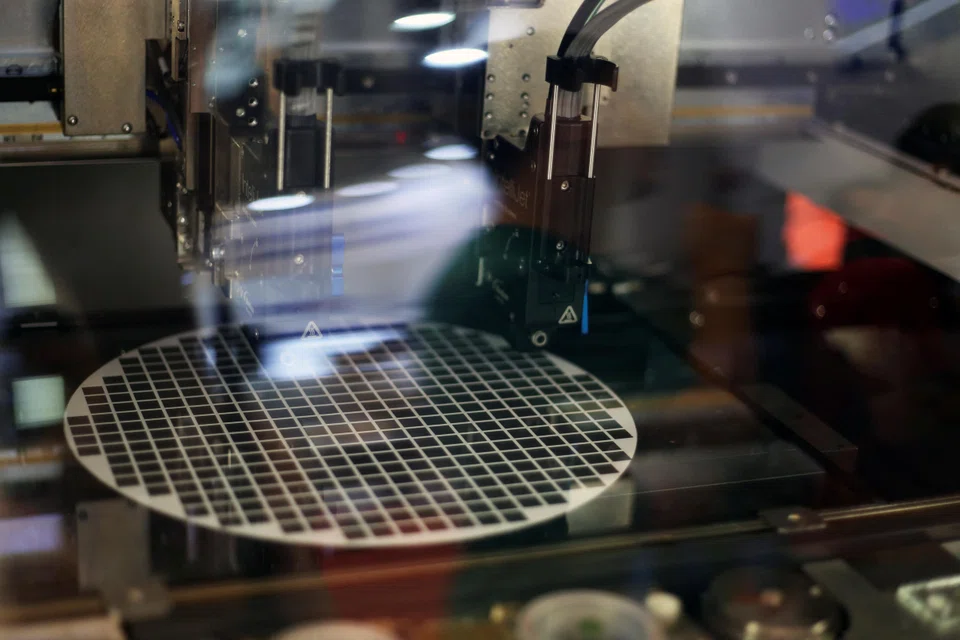
SINGAPORE-LISTED tech companies, comprising mainly semiconductor manufacturers, have seen their net profits decline in the first half of this year.
However, analysts see some light at the end of the tunnel.
In a recent strategy note, CGS-CIMB analyst William Tng noted that the Singapore tech sector saw net profit fall by 39.4 per cent year on year and 36.3 per cent half on half (hoh) for the first half of this year.
He attributed this to the high-base effect as these companies posted record profits in FY2022, a slowdown in the semiconductor industry, and a generally weak economy in the first half.
Tng remains neutral on the tech sector as he waits for companies’ third-quarter business updates to provide more clarity on the profit outlook for FY2024 and FY2025.
Other analysts, such as RHB’s Alfie Yeo, are also neutral on the sector.
Yeo noted that the semiconductor sector had a good run prior to this latest half year. More chips were produced and sold on the back of demand for consumer electronics.
On the downside, however, this has led to an oversupply of chips in 2023.
“In general, results of companies supporting the semiconductor supply chain and production have not been encouraging, due to the oversupply situation and lower semiconductor production,” Yeo said.
DBS analyst Ling Lee Keng noted that players serving companies with exposure to consumer electronics tend to be weaker. This list includes AEM Holdings , whose key customer is known to be chipmaker Intel.
S&P Global Market Intelligence said that based on consensus estimates, the 13 chipmakers that it tracks will continue to see revenue declines on a year-on-year basis until the fourth quarter of 2023.
Increase in revenues
There are, however, signs of stabilisation.
S&P Capital IQ data for these chipmakers showed their revenues increasing by 2 per cent sequentially in the second quarter of 2023. Estimates also suggest revenue could climb 12 per cent sequentially in the third quarter.
Maybank analyst Jarick Seet said most players, apart from Frencken Group , did worse than expected. The company manufactures components and modules for the semiconductor industry, as well as for customers in the business of life sciences, automotive and industrial automation.
Seet said the company’s management has guided for higher h-o-h semiconductor revenues in the second half of this year and said that the worst is likely over.
“We believe its key customer’s inventory level has been dwindling, and (the customer) has started to increase orders – potentially leading to better quarters ahead,” Seet said.
He added that the company is one of a few semiconductor stocks that trades below net asset value at S$0.90 per share. He maintains “buy” on the counter with a target price of S$0.97.
Both Tng and Ling are also bullish on mainboard-listed semiconductor player UMS Holdings .
Ling expects the company to see stronger order momentum in 2024 as the semiconductor industry recovers.
She noted that the group has brought on a new customer, which could make a more meaningful contribution next year.
“With its main production facilities in Malaysia, UMS is a key beneficiary of the trade diversification trend. The group has constructed a new plant in Penang and production is expected to ramp up this year,” she said.
Tng also noted that UMS has guided for a bottoming of demand in the second quarter of 2023.
In addition, the company has raised its dividend per share for the second quarter of 2023 to S$0.012, from S$0.01 for the same period a year earlier. Tng projects that the company could see dividend yields of 5.3 per cent in FY24 and FY25.
He maintains an “add” call on the company with a lower target price of S$1.19, from a previous target of S$1.57.
Nevertheless, he noted that there could be some downside risks to UMS’ profitability, such as failure to secure enough orders for its Penang plant and increased competition from other suppliers in Penang.
The company could also be negatively impacted by its key customer’s loss of sales to China, as well as a slower-than-expected rate of return of orders from customers.
Maybank’s Seet said it is also important to keep an eye on the inventory levels of these companies’ key customers. He expects these inventory levels to normalise around Q4 2023 or Q1 2024.






