Top Glove Q2 net profit dives 97% to RM87.5m, no dividend proposed
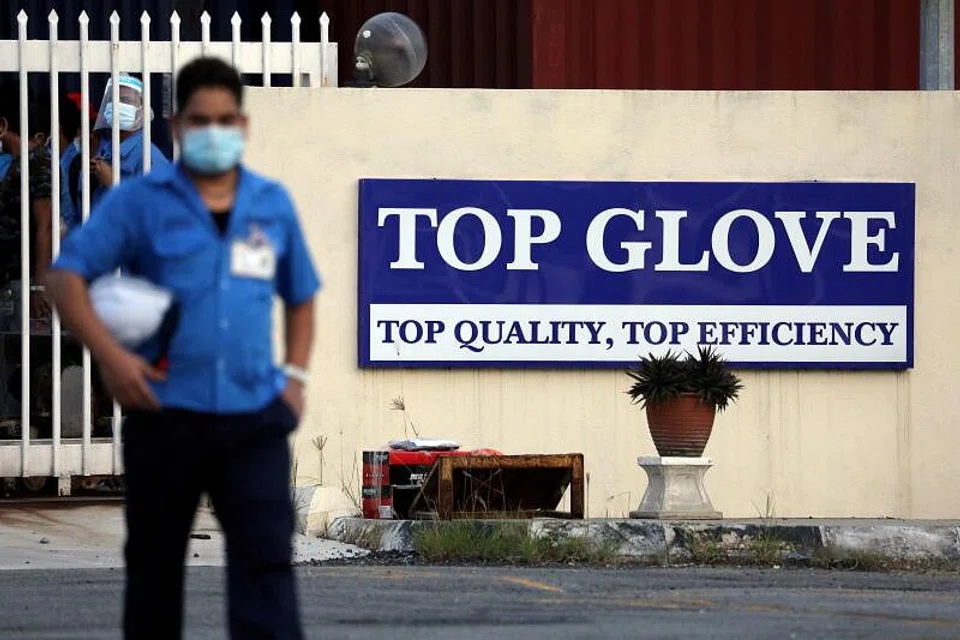
THE best days appear to be over for the glove industry, and Top Glove Corporation BVA is one of the companies that will have to settle for "normalising" financial figures -- from "phenomenal highs to still healthy pre-pandemic levels", company executives said on Wednesday (Mar 9).
In a call with reporters and analysts to discuss the group's financial results, Top Glove's executive director Lim Cheong Guan stressed that the long term outlook for the glove industry remains promising, and companies like Top Glove are well-placed to deal with the correction in profits, as well as demand and average selling prices (ASPs) of gloves.
"Many other industries (are) still struggling to recover and climb their way up from a negative position," he said. "Challenging periods will come and go for any business, but the glove industry most certainly remains a promising one in the long-run."
Top Glove enjoyed supernormal profits during the intial stage of the Covid-19 pandemic, on the back of higher demand for rubber gloves across all its key markets. However, as countries shift to an endemic phase, the company's financials have been hit.
The firm reported a net profit of RM87.5 million (S$28.5 million) for the second fiscal quarter which ended in February, down from earnings of RM2.9 billion in the corresponding year-ago quarter.
No dividend was declared for the quarter under review, versus a single-tier dividend of 25.2 sen per share in Q2 FY2021.
On a per-share basis, earnings for the quarter stood at 1.09 sen, versus 35.77 sen in Q2 FY2021.
Revenue for Q2 came in at RM1.4 billion, down 73 per cent from revenue of RM5.4 billion from Q2 FY2021. The group attributed the softer financial performance to normalising average selling prices (ASPs), which are moving "closer to pre-pandemic levels".
Raw material prices were also generally on a downward trend, decreasing at a slower pace than ASPs, which resulted in margin compression. On a year-on-year basis, average natural latex prices were down 6 per cent to RM5.57 per kg in Q2 FY2022, while nitrile latex prices have fallen 50 per cent to US$1.15 per kg, said Top Glove.
However, company executives said the ASPs currently are "very close to the bottom" and are expected to improve over the next few quarters.
Top Glove also has to grapple with intensifying competition from new entrants into the glovemaking scene, or companies that have ramped up production.
The company also suffered a dent to its reputation on the back of its run-ins with the US Customs and Border Protection (CBP) on the grounds of forced labour allegations. The US CBP has lifted its import ban on the company's products.
Managing director Lee Kim Meow said Top Glove has recovered 80 to 90 per cent of its US business, adding that some customers have not placed orders with the company as they have enough stock on hand. Lee added that no key customers have been lost to competitors.
Top Glove's capacity and research and development (R&D) capabilities means that it is "head and shoulders" above the rest of the players in the glovemaking sector - particularly the small and medium sized companies that do not have "this type of flexibility", he added.
Troubles in Russia and Ukraine are not expected to have much impact on Top Glove's revenue for now, as both countries contribute less than 5 per cent of the group's topline, said Lee.
However, the situation is something that the group is monitoring closely, and necessary mitigation measures have already been put in place to ensure that customers there have minimal disruptions.
As far as logistics go, container availability and vessel space are issues that Top Glove still has to deal with. Some of the ports in Ukraine have closed, and Lee said the company is looking at redirecting some shipments to nearby ports.
Shares of Top Glove ended Wednesday at S$0.555, down 6.7 per cent or S$0.04.