

AirAsia X slips 3% after posting wider-than-expected losses
Airline reports full-year net loss of RM520m; analysts expect continued losses for another year or two
Kuala Lumpur
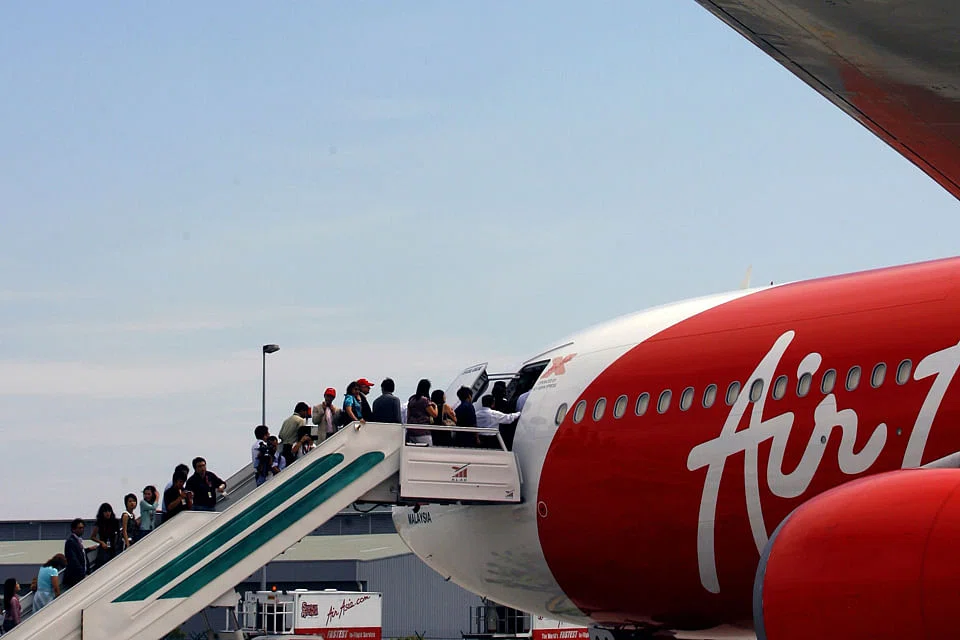
SHARES of AirAsia X slipped 3.2 per cent to 60 sen on Wednesday after the budget long-haul carrier posted wider-than-expected losses for the fiscal year to end December, with analysts projecting continued losses for another year or two.
The airline's full-year net loss of RM520 million (S$195.4 million) - including RM168 million in the fourth quarter - prompted a chorus of sell calls with most analysts projecting tough times ahead notwithstanding lower fuel costs.
AffinHwang Capital attributed the "hard landing" last year to costs running ahead of revenue "resulting in the huge losses".
In the fourth quarter, for instance, yields slumped by 5 per cent year-on-year while operational expenditure swelled by a fourth. "2014 yields took a beating on its aggressive capacity expansion (+33 per cent y-o-y) amidst intensifying competition," RHB Research observed.
Indeed, the AirAsia group recently effected a management change to stem the haemorrhage. Listed in mid-July 2013 after raising nearly RM1 billion in its initial public offering, the airline has seen its shares founder. The stock is valued at 42-52 sen compared to its IPO price of RM1.25. A cash call has been made to raise US$109 million.
Azran Osman-Rani, the previous chief executive, has been replaced by Benyamin Ismail, who was named acting CEO. He will be supported by AirAsia X group chief executive Kamaruddin Meranun, one of the founders.
The airline also suffered some reputational damage after an AirAsia Indonesia aircraft crashed into the Java Sea en-route from Surabaya to Singapore in December.
To turn around the business, management has indicated that it will focus on maximising revenue through higher base fare and ancillary income, cost reductions (headcount cuts and contract renegotiations) and capacity management (redeploying capacity).
Non-performing routes such as Adelaide and Nagoya have already been trimmed and cuts in the working crew are set to come next.
And despite planning to keep AirAsia and AirAsia X operations separate, RHB Investment Bank said, management has indicated that ground operations would be merged as it strives to achieve a 5-7 per cent improvement in unit costs (ex-fuel) in FY15.
RHB analyst Ahmad Maghfur Usman said cost initiatives were crucial in getting to a breakeven load factor. He saw the moderation in the drop in yields as suggesting that it is approaching an upward inflection point in the coming quarter.
AllianceDBS analyst Tan Kee Hoong is less optimistic. AirAsia X's Thai and Indonesian associates will be a drag on net profit, he said, while the restructuring of ailing Malaysia Airlines' longer-haul routes is likely to be effected only after the second quarter. (Fares are seen remaining tight until then).
On cheaper fuel, he expects a significant portion of savings to be passed on to consumers in a bid to attract more passengers. In any event, he pointed out, the strong US dollar would affect the carrier's bottom line as three-quarters of its cost base is in the currency.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Seatrium allocates S$200 million for new share buyback programme

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026
Stocks to watch: Mapletree Logistics Trust, Seatrium, Keppel DC Reit, Food Empire

