

Baltic Exchange Shipping Insights
A roundup of the week's tanker and dry bulk market
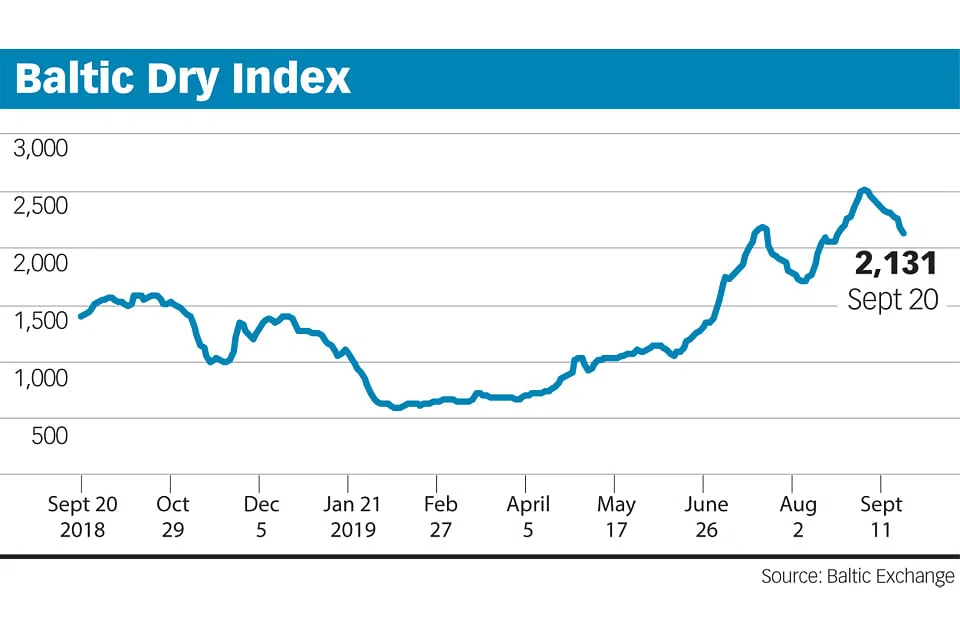
DRY BULK REPORT
Capesize
The market trended down over this past week, breaking it out of its upward trending range.
While the market traded sideways at the beginning of this past week, it was unable to build any upward momentum and broke to the downside midweek.
Brazil to China C3 opened the week at $25.89 to close out Friday at $23.705, while West Australia to China C5 opened at $10.923 to close at $9.145.
Trade activity was moderate throughout the week in the Atlantic, while quieter in the Pacific.
Bunker pricing for traders was a wild ride this week as fuel markets absorbed possible scenarios of war risk footing in the Persian Gulf.
Prices lifted drastically leaving many to back off trades and wait for the situation to calm.
Rates did reduce but are still at elevated levels. The 5TC opened the week at $33,996 to close at $31,470.
While there was some talk of a floor being reached, Friday's drop of -$1301 momentum looks still to the downside.
Panamax
The week began with small increases in the Atlantic indices, but this was soon reversed, and the losses accelerated as the week wore on.
There was healthy fixing volume for both transatlantic and fronthaul trips, but the earlier tonnage was forced to reduce their offers to find cover.
Brokers felt October positions looked more balanced.
The Pacific drifted lower all week, with vessels in the North forced to ballast South.
The South American market was not providing its normal support, with charterers concentrating on taking tonnage delivery Arrival Pilot Station (APS) below last done levels.
There was hope of a possible surge in fixing this week, prior to Golden Week, but this was the only positive from the week.
Very little period trading was reported, although a modern Panamax did fix for a year at $12,500 basis delivery prompt in Japan.
Supramax/Ultramax
A mixed week overall for the Baltic Supramax Index (BSI), which started in negative mode but as the week closed the trend slowed.
Limited period activity was reported, many waiting to see a clearer direction in the market.
An Ultramax was covered from the Continent for a short period at $20,000, redelivery worldwide.
From the Atlantic, demand waned from East Coast South America, whilst stronger levels were noted from the Mediterranean.
A 55,000dwt vessel fixed delivery for a central Mediterranean trip via the Black Sea, redelivery Southeast Asia, at $27,500.
From the US Gulf Ultramaxes were seeing in the upper $20,000s for trans-Atlantic runs.
From the Asian arena it was a slow start, but demand increased as the week went on.
A 61,000dwt ship open Indonesia fixed a trip via Australia, redelivery Japan, at $17,000.
A 53,000-tonner, open Chittagong, was fixed for a trip via East Coast India, redelivery China, at $15,000.
All eyes fixed forward to see the following week's direction.
Handysize
The Baltic Handysize Index (BHSI) stayed still at 691 for the first four days of the week and eventually improved a point by Friday.
Overall the sentiment in the Atlantic remained positive, with East Coast South America slightly improving.
The rates from the Pacific continued to ease as limited volume lent support to the fixing level, especially for second half September dates cargo.
On the period front, a 32,000dwt vessel, open Uddevalla in mid-September, was fixed at $11,500, with redelivery in the Atlantic.
A 33,000-tonner open Lagos was fixed via East Coast South America for a trip to the Persian Gulf at $24,000, intention petcoke.
A 33,000dwt ship open Oran was fixed to run via North France and redeliver in Algeria in the mid $11,000s.
In the East, a 28,000dwt vessel open Ho Chi Minh city was fixed for a trip to CJK at a rate in the high $8,000s.
A 33,000dwt ship open North China and a 38,000dwt ship open South Korea were both fixed for a Pacific trip at $9,000 and $11,500 respectively, possibly with steels.
TANKER MARKET REPORT
VLCC
The attack on Saudi Arabia led to volatile bunker prices and owners capitalised on this with Middle East Gulf rates for 280,000mt to US Gulf basis Cape to Cape now being rated up four points at WS 31 level, whilst 270,000mt to China gained around 15 points to WS 69 region.
Rates for 260,000mt West Africa to China followed suit and last seen here was at WS 71, up almost 14 points.
The market for 270,000mt US Gulf to China now sits at between $8.05 to $8.1 million in contrast to $6.5 million a week ago.
Suezmax
An active market from both the Caribbean and US Gulf thinned the West Africa list.
On the back of this, and an influx of West Africa cargoes, rates for 130,000mt West Africa to UK-Continent gained 30 points plus, with Total and Petrogal fixing at WS 90 and WS 95 respectively.
The 135,000mt Black Sea to Mediterranean trade gained 7.5 points to WS 80.
The 140,000mt Basrah to Mediterranean run initially held at WS 30 before being dragged up by a firmer West Africa market and the market here now is hovering close to WS 34.5.
Aframax
80,000mt Ceyhan to the Mediterranean gained another five points, with UML paying WS 110.
The 80,000mt North Sea to UK-Continent trade firmed over 10 points to WS 110 region, with potential for further increases against a tightening tonnage list.
In the 100,000mt Baltic to UK-Continent market, rates have been steady at around WS 90.
The main beneficiary has been the 70,000mt Caribbean to US Gulf market, which gained 30 points to WS 150.
There is even talk of WS 160 having been done, however, these rates are also appealing to Suezmaxes, which may subsequently cap rates.
70,000mt US Gulf to the Mediterranean rose 25 points to now sit in the very low WS 140s.
Clean
The market for 75,000mt Middle East Gulf to Japan eased 3.5 points to WS 97.5, while the 55,000mt to Japan trade fell from WS 112.5. to the mid WS 90s.
In the 37,000mt clean Continent to US Atlantic Coast market, rates were flat at WS 95, while the 38,000mt US Gulf to UK-Continent backhaul trade was down around four points to very low WS 70s.
This report is produced by the Baltic Exchange.
The Baltic Exchange, a wholly-owned subsidiary of Singapore Exchange, is the world's only independent source of maritime market information for the trading and settlement of physical and derivative contracts.
Its international community of over 650 members encompasses the majority of world shipping interests and commits to a code of business conduct overseen by the Baltic.
For daily freight market reports and assessments, please visit www.balticexchange.com.
TRENDING NOW

Singapore expects all parties to honour commitments, says PM Wong after Indonesia cuts gas exports

Gas Supply may pursue remedies if contract breached following Indonesia’s export cuts: Tan See Leng
SoftBank’s Son plans US$50 billion Malaysia tech outlay: Anwar Ibrahim

Is Manila Asia’s new dining hot spot?

