Choppy waters ahead for shipping, but rates to stabilise above pre-pandemic levels
Mindy Tan
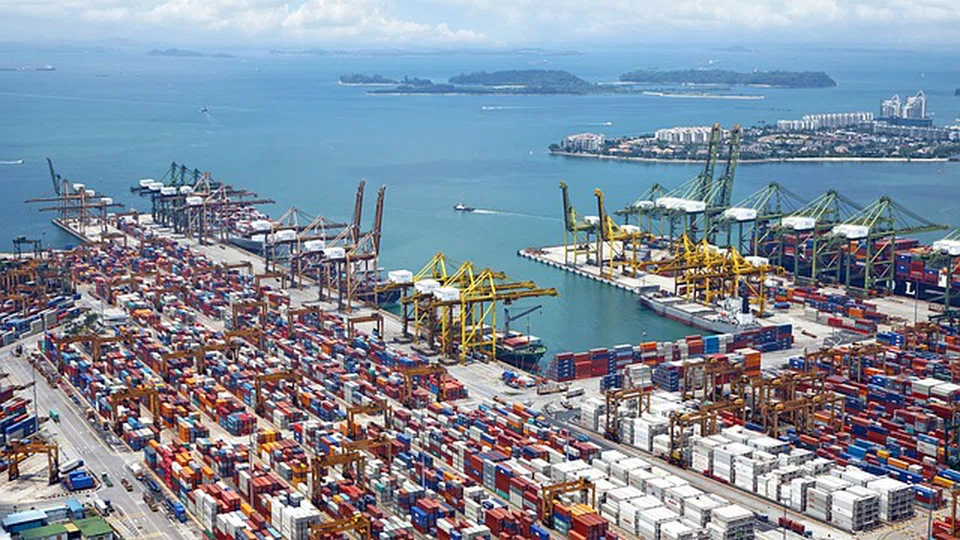
AFTER a tumultuous two years which saw freight rates hit record highs, the good news is that shipping prices appear to have stabilised. The bad news is that the longer-term, 30-year trend of shipping getting cheaper will not resume.
Container freight rates have fallen by between 40 and 80 per cent in the last six months. But this was from record highs, fuelled by an earlier surge in consumer demand and supply chain congestion issues caused by Covid-19.
Now, freight demand has softened due to lower end-consumer demand, fears of a recession and built-up inventories. At both the retail and wholesale levels, inventories are at record highs after a period of panicked stocking-up that lasted until early this year.
Backhaul spot rates – charged when the vessel is returning to its original point of departure – are also seeing “significant drops on key trades”, according to research from freight rate benchmarking platform Xeneta.
“The fronthaul developments have captured most of the press, with spot rates falling away dramatically since summer. However, in some cases, backhaul rates have seen equally large drops – and what’s more, those drops have been more protracted,” said Peter Sand, Xeneta’s chief analyst.
Backhaul rates for the North Europe to Far East container corridor, for instance, are now 6.8 per cent below the pre-pandemic figures of January 2020. The average rate for a standard 40-foot equivalent unit (FEU) has now fallen to US$820 over the last year and a half, a decrease of more than US$1,000 per FEU or 56 per cent.
“This is now one of the first trades back at pre-Covid levels, but we don’t expect it to be the last,” said Sand.
Besides spot rates, contract rates are also starting to taper off. Contracts are being renegotiated, and Xeneta chief executive officer Patrik Berglund expects long-term rates to fall “rapidly” as older expensive contracts expire. “However, long-term rates will not drop below spot rates during the first half of 2023,” he added.
After record peaks in 2020 and 2021, Xeneta posits that 2023 will be “extremely challenging” for the rapidly cooling ocean freight market and that cargo volumes could fall by up to 2.5 per cent. Besides coming down from atypical highs, demand is expected to further cool due to rising interest rates. As a result, rates are expected to drop “significantly” and vessels will see increased idling.
McKinsey & Company partner Steve Saxon similarly sees 2023 as challenging, especially if a recession hits. “During Covid, people built up their savings but most of that is now spent. We could see a year of flat demand especially if inflation rises.”
“Two to three years out, you could see a return to growth, but it’s likely single digits of 2 to 3 per cent. It’s still good, but not the same as the 20 per cent spikes we saw during Covid,” he added.
Even as demand slows, supply is rising: the world’s fleet is growing, with a nominal inflow of 1.65 million TEU (20-foot equivalent unit) of capacity in 2023.
Said Xeneta’s Berglund: “Some demolitions will dent that growth, but we still expect an increase in capacity of 5.9 per cent. Even if demolitions double from our current level of expectations, the industry would still be looking at an almost 5 per cent expansion.”
“We could see spot rates on some key corridors drop below pre-pandemic levels during the first half of 2023,” he added.
All is relative
Yet Onno Boots, president and CEO for Asia-Pacific at logistics company GEODIS, notes that “everyone knew the excessive rates would come down”. The current drop is relative, he stressed. “We’ve gotten so used to very high volumes in the last two years that when they suddenly came off, everyone jumped into panic mode. But that’s not a realistic reference.”
Indeed, while spot rates have come down, they are expected to stabilise above pre-pandemic levels.
Even though “the market will be soft for awhile”, Boots expects rates to normalise at 20 per cent above 2019 levels.
“We’ll be in for some rough riders compared to the last two-and-a-half years but not rougher than 2019,” he said. “Once restocking starts again, which I am convinced will happen somewhere in the summer of 2023, we’ll probably see some uptick in volumes come back in the second half of the year.”
Saxon expects rates to stabilise 50 per cent higher than 2019 figures. “A reasonable base assumption is that it would take about US$3,000 to move a 40-foot container from Asia to the US West Coast, compared to a pre-Covid level of US$2,000.”
No going back
Pre-Covid, it was considered normal for spot rates to trend downwards as ships got bigger and ports more efficient, with the resulting cost benefits being passed on to customers, said McKinsey’s Saxon. Covid upended this due to unprecedented demand and closed ports, causing prices to spike.
But even in a post-Covid world, the downward trend may not resume. Despite sober demand and a greater supply of ships, upward pressures remain. Costs – particularly fuel prices and the costs of building ships – have shot up dramatically in recent years, said McKinsey’s Saxon.
Seafarer wages have also gone up by about 30 per cent, while ports have increased their prices. As a result, the cost base for shipping companies is about 30 per cent higher than in 2019, he noted.
Terry Smagh, senior vice-president and general manager for Asia-Pacific and Japan at enterprise software firm Infor, said that businesses will have to “stop treating supply chains as a never-ending source of cost-reduction opportunities”.
“While costs will come down from the startling rates experienced in late 2020 and throughout 2021, they will stay at rates much elevated than in the past,” he said.
“Ocean carriers have demonstrated greater self-discipline than ever before to manage their capacity and therefore their pricing leverage,” he added. Already, the industry has seen an increase in blank sailings – where the carrier cancels the trip or skips a port – and deliberate slowing down of ships, to artificially reduce the supply of capacity.
The market will thus have to get used to higher rates, he said. “Decarbonisation will certainly increase costs for fleets and for shippers, but the market has proven that higher freight costs can be readily absorbed in strong economies, though not without loud complaint,” he said.