

Purchase price offers OOCL shareholders some comfort
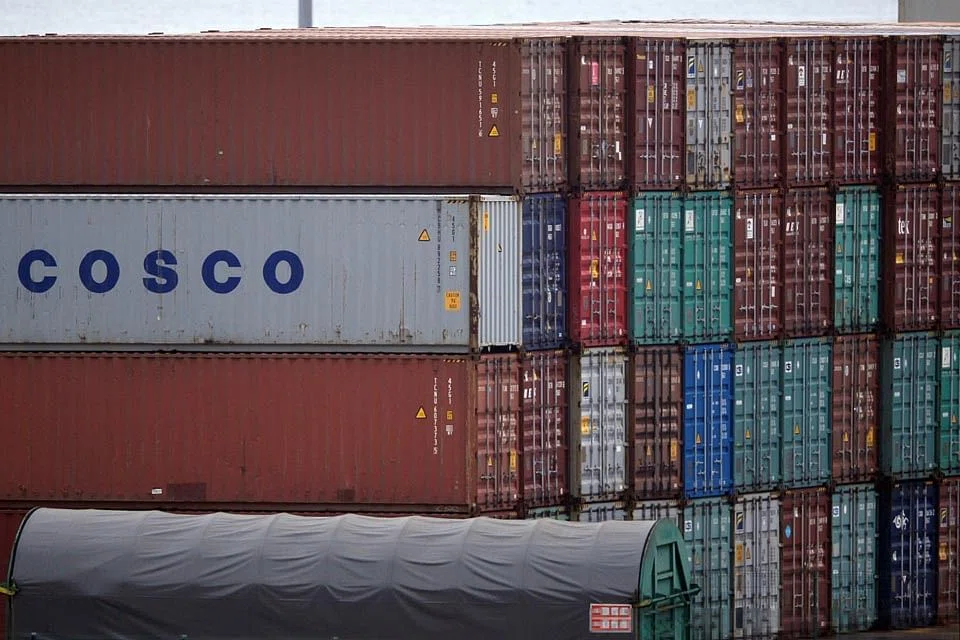
THE family of former Hong Kong chief executive Tung Chee-hwa is giving up its Orient Overseas Container Line (OOCL), but the price the mainland buyer is paying offers some comfort. Cosco Shipping Holdings Co agreed to pay US$6.3 billion for OOCL, the Hong Kong container-shipping group that China reportedly helped bail out from the verge of bankruptcy in the 1980s.
Swallowing Hong Kong's largest box mover catapults the state-owned Chinese company to the world's third-biggest shipping line, and the largest serving the Asia-North America route. Perhaps more importantly, it tightens China's control of the ports and shipping lines that turned Hong Kong into a global trade hub.
The deal itself wasn't a shock. The shipping industry has been reckoning with depressed demand and low rates for years, leading to billions of dollars in bankruptcies and consolidation in a global container fleet now controlled by just three main groups. OOCL, the ninth-biggest line with a market share of less than 3 per cent market, wouldn't have been able to keep sailing solo.
What did surprise investors was the eye-popping price, which represents a 112 per cent premium to the stock's one-year trading average. The transaction is the largest by value in shipping since 2003, when AP Moller Group merged two publicly traded companies to create the Danish conglomerate AP Moller-Maersk.
Cosco's initial bid for OOCL more than six months ago hovered around the US$4 billion mark, according to the Wall Street Journal. That figure hardly budged as recently as June, and for good reason: Most shipping deals in the last two years or so have been done at a price-to-book ratio of about one.
CMA-CGM's acquisition of Neptune Orient Lines was done at a ratio of one, and Maersk's purchase of Hamburg Sud represented a 1.3 multiple, according to Jefferies Group research. Cosco is set to pay around 1.4 times OOCL's book value.
A company in a weakened position has few chips to bargain for a higher offer. And it's not as if there was a white knight for OOCL, whose year-on-year revenue dropped by 11 per cent in 2016 and 8 per cent the year before.
Family history might count more than leverage, though. OOCL has been controlled by the pro-Beijing Tung family since 1947. The founder's son and former chairman Tung Chee-hwa was Hong Kong's first chief executive after the 1997 handover to China.
It's unlikely the third-generation CEO, Andy Tung, would have been prepared to lose control of the family empire without holding out for a handsome reward for shareholders.
(This column does not necessarily reflect the opinion of Bloomberg LP and its owners.) BLOOMBERG
READ MORE: US$6.3b Cosco-OOCL deal will see power shift: analysts
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Hwa Seng Builder, two China companies win S$1.2 billion Tuas Road Viaduct phase two contracts

Deal between tycoon friends sparks scrutiny of Philippine power sector

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

