SIA expected to post lower earnings for Q1 FY2025, say analysts
Still, the rebound in air freight rates is deemed as tailwind for the group and should provide some support to the company’s FY2025 earnings
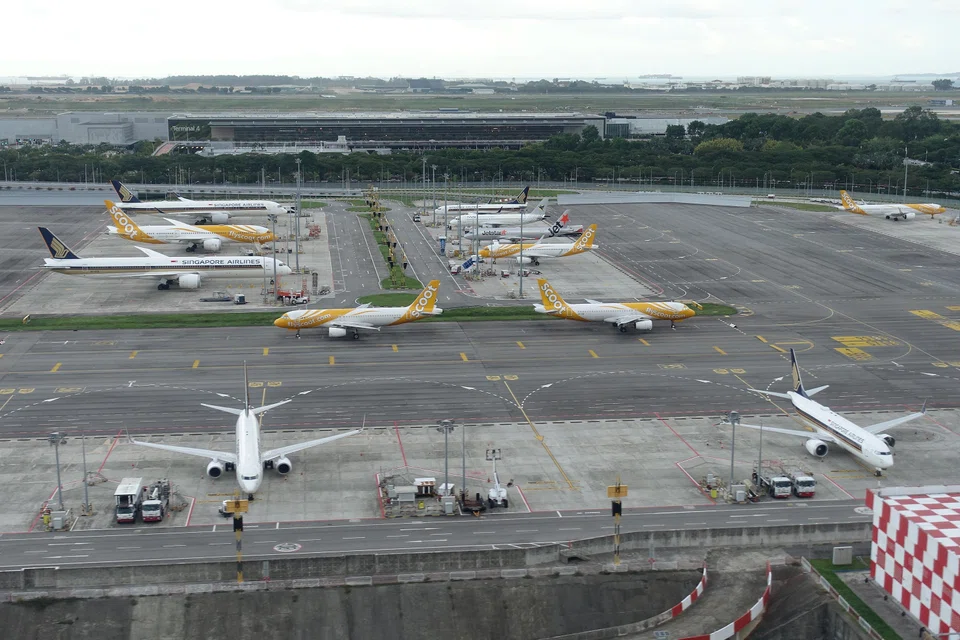
SINGAPORE Airlines (SIA) is expected to deliver much lower earnings for the first quarter of FY2025 to June, based on some analysts’ forecasts.
UOB Kay Hian (UOBKH) expects the flag carrier group to generate a net profit of between S$390 million and S$550 million, a year-on-year decline of 25 per cent to 47 per cent from the record quarterly bottom line of S$734 million reported for Q1 FY2024.
The analyst, Roy Chen, made the forecast based on SIA’s April to June operating data and has factored in the expected passenger yield moderation and recent rebound in air freight rates. “Our estimates have included fuel hedge gains but excluded other possible one-off items such as tax credits.”
Raymond Yap, an analyst at CGS International, has an estimate of about S$490 million for the mainboard-listed airline group’s Q1 FY2025, about 33 per cent lower than the year-ago period.
He explained that the showing would be due to a possible normalisation of the effective tax rate from Q4 FY24’s low levels, when SIA probably utilised some budget carrier Scoot’s carry-forward losses.
“We consider this to be a very good result, underlining sustained strength in passenger unit revenue and rising cargo unit revenue on a quarter-on-quarter basis,” said Yap.
The robust demand during the June holidays likely helped sustain SIA group’s passenger yields, with the year-on-year dip of 1.7 per cent being smaller than that of 3.3 per cent for Q4 FY2024, he pointed out.
But Scoot, impacted by flight disruptions stemming from Pratt & Whitney engine issues for its A320neo fleet, will likely report a lower passenger yield, said Yap.
UOBKH’s Chen said: “We expect SIA’s passenger yields to continue to moderate in the medium term, driven by increasing competition; this will put pressure on SIA’s profitability.”
Still, the rebound in air freight rates is deemed a tailwind for the group and should provide some support to SIA’s FY2025 earnings.
Freight load has sustained a moderate pace of recovery in the past few months, buoyed by higher e-commerce demand and some demand spillover from ocean shipping amid liner service disruptions to avoid attacks on merchant vessels in the Red Sea and worsened congestion at the Singapore port.
The strength in air freight rates may stay throughout the second half of 2024, thereby lending some support to the airline group’s FY2025 net profit, said Chen.
The analyst also raised the earnings estimates for FY2025 by 5.8 per cent, FY2026 by 13.2 per cent and FY2027 by 4.2 per cent to S$3.2 billion, S$1.4 billion, and S$1.3 billion, respectively.
The higher earnings forecasts reflect the stronger air freight rates in FY2025 and potentially slower-than-expected passenger yield moderation. Delays in new aircraft deliveries by planemakers Airbus and Boeing may keep the airline industry’s capacity supply tight for longer.
Both Yap and Chen maintained their “hold” recommendations for SIA shares, but Chen raised the target price to S$6.43 from S$6.35 while Yap’s S$6.78 remained unchanged.
They were the two out of nine analysts making a “hold” call, according to Bloomberg, while there were two “sell” and “buy” recommendations each.
SIA will report Q1 financials on Jul 31 after market close.
Shares in SIA were trading at S$7.11, up S$0.02 or 0.3 per cent at 1.14 pm on Wednesday.