

SIA’s Q3 financials beat street consensus; analysts see early signs of pricing recovery
DBS believes group’s better-than-expected passenger yields are ‘a potential early sign of an inflection point’
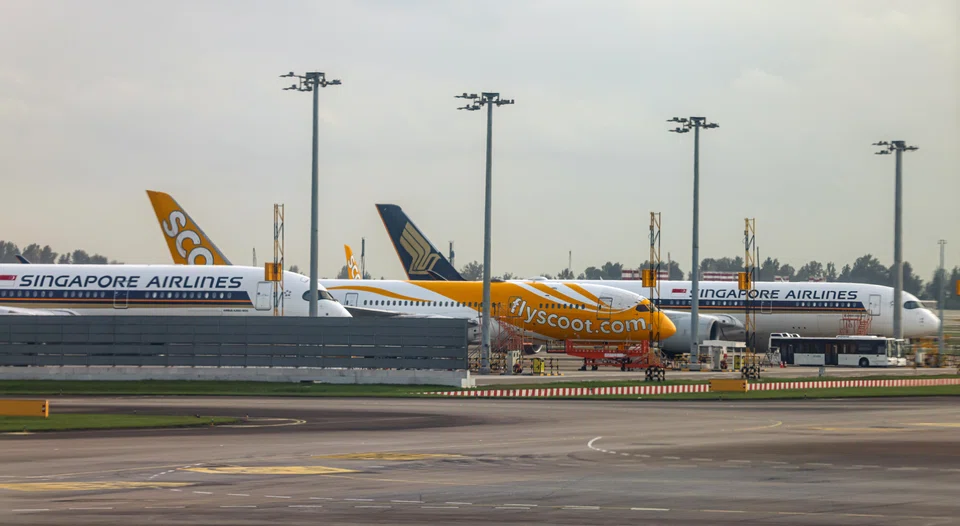
[SINGAPORE] Singapore Airlines’ (SIA) third-quarter financial performance beat street estimates, with analysts seeing early signs of pricing recovery.
The airline on Tuesday (Feb 24) posted a 25.9 per cent year-on-year improvement in operating profit to S$792 million for the quarter to December. This came even as net profit tumbled 68.9 per cent to S$505 million in the absence of a one-time accounting gain.
It also achieved a record quarterly revenue of S$5.5 billion, up 5.5 per cent on the year.
The airline group’s S$1.6 billion operating profit for the nine-month period, which was 11.9 per cent higher year on year, was above DBS and consensus forecasts for the full year of 91 per cent and 95 per cent, respectively, wrote DBS Group Research analyst Tabitha Foo on Wednesday.
She maintained a “hold” recommendation on SIA shares with a target price of S$6.50.
She also noted that SIA’s revenue was outstanding, driven by better-than-expected passenger yields at both the full-service carrier and its budget arm Scoot.
“Passenger yields surprised to the upside, turning positive year on year after an extended period of normalisation. This turnaround is notable given persistent pricing pressure across the Asia-Pacific region amid intensifying competition. While Q3 is typically the strongest seasonal quarter, we view this as a potential early sign of an inflection point.”
Foo expects SIA group’s passenger yield improvement to be more “durable” in the fourth quarter of FY2026, with the full-service airline’s premiumisation efforts to further strengthen its medium-term pricing power by shifting its revenue mix towards higher-yield segments.
After stripping out the impact of the non-cash accounting gain of S$1.1 billion booked in the year-ago period following the merger of Vistara airline with Air India, the comparable core net profit for Q3 would be only 4.4 per cent lower year on year. This decline was driven by increased losses from associates, including Air India.
SIA’s share of losses from associated companies including Air India rocketed by S$163 million to S$178 million during the quarter. This was because the group recognised a full-quarter share of the Indian airline’s losses this year, compared with that for only one month the year before.
Foo believes that the sustained strength in passenger travel should help offset the group’s cargo softness and that SIA’s share price should react positively given the convincing operating performance beat. But she remains watchful on Air India.
Her view on SIA’s share price was shared by Citi analyst Kaseedit Choonnawat, who said in a flash note on Wednesday that the counter could initially react positively post-results as Q3’s revenue and core earnings beat Bloomberg consensus by 8 per cent and 30 per cent, respectively – primarily driven by an improvement in passenger yields.
OCBC equity analyst Ada Lim raised her target price for the airline to S$6.88 from S$6.40 but maintained her “hold” recommendation. She said SIA group could get some support from industry-wide aircraft delivery delays for yields on top of the improvement in its yields.
She also considered that Scoot had swung to a profit during the quarter compared to losses in the first half of FY2026 at the operating level as well as the group’s share of losses from associated companies shrank to S$178 million from S$265 million in the preceding quarter.
SIA shares closed S$0.14 or 2 per cent higher at S$7.17 on Wednesday.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

