

Two OUE Reits join consolidation trend with proposed merger
Deal will yield diversified Reit with commercial property and hospitality assets worth S$6.8 billion; increased liquidity expected to raise unit price
Ng Ren Jye
Singapore
CONSOLIDATION in the Reit sector appears to be gaining momentum - two OUE units announced a merger on Monday to create a S$6.8 billion diversified real estate investment trust (Reit) whose unit price could rise over time with increased liquidity and institutional interest.
Under the proposed scheme, OUE Commercial Real Estate Investment Trust (OUE C-Reit) will pay each holder of OUE Hospitality Trust (OUE H-Trust) stapled security S$0.04075 cash plus 1.3583 new OUE C-Reit units.
This translates to a deal valuation of S$1.49 billion, with S$74.6 million in cash and the remaining balance paid by the issue of about 2.5 billion new OUE C-Reit units to OUE H-Trust holders at an illustrative S$0.57 per OUE C-Reit unit.
The S$0.57 valuation for the new OUE C-Reit units matches the theoretical ex-rights price of the Reit's recent 83-for-100 rights issue to help pay for the office components of OUE Downtown.
Along with an estimated S$8.3 million acquisition fee and a further S$15.7 million for "professional and other fees", OUE C-Reit expects to shell out a total of S$1.5 billion to acquire OUE H-Trust.
OUE C-Reit last traded at S$0.52 for a market capitalisation of S$1.49 billion on Friday, while OUE H-Trust closed at S$0.735 for a market valuation of S$1.34 billion.
This is the second S-Reit merger in the past six months after ESR-Reit and Viva Industrial Trust's S$3 billion merger.
DBS analyst Derek Tan said the latest deal will be positive as a whole for both unitholders. The bigger positive for him though is that by combining to become a bigger entity, the Reit will attract more liquidity and institutional investor interest over time. This virtuous cycle should result in the Reit trading at higher prices, resulting in a lower cost of capital.
"At this point, liquidity and trading volume for the two (OUE C-Reit and OUE H-Trust) on their own hasn't been too ideal."
Parent company OUE Group will continue to retain a 48.3 per cent in the enlarged Reit. OUE shares closed at S$1.77 on Friday.
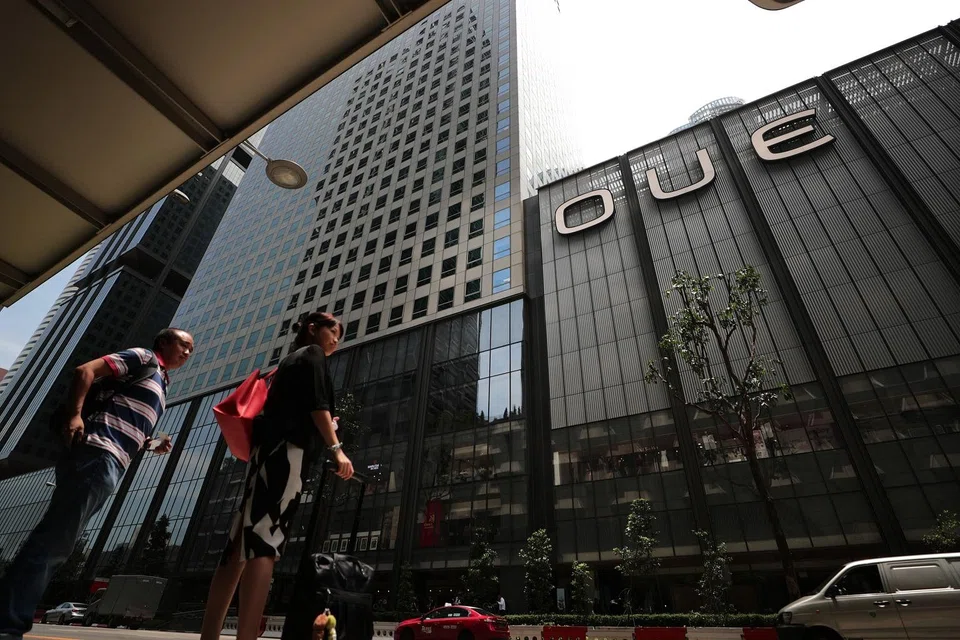
The merged entity will become Singapore's tenth largest Reit by market capitalisation and eighth largest by assets. It will have seven properties under its umbrella: four from OUE C-Reit - OUE Bayfront, One Raffles Place, OUE Downtown Office, Lippo Plaza, and three from OUE H-Trust - Mandarin Orchard Singapore, Mandarin Gallery and Crowne Plaza Changi Airport.
The enlarged Reit will have a funding capacity of about S$1 billion.
If the deal had been completed at the beginning of 2018, OUE C-Reit's distribution per unit would have increased by 2.1 per cent on a pro-forma basis, while OUE H-Trust's distribution per stapled security would have increased by 1.4 per cent.
The managers emphasised diversification and scale at its media briefing on Monday.
While it will have diversification among industries, its largest asset in the enlarged portfolio, One Raffles Place, still makes up 27 per cent of it, or slightly more than a quarter.
Tan Shu Lin, chief executive officer of OUE C-Reit's manager, said that with the merger, the Reit can now approach mixed developments as a whole instead of in parts. She added that they saw potential for growth in the integrated development market.
The deal will increase free float by more than two times, which potentially drives positive re-rating and inclusion in property indexes such as FTSE EPRA Global Real Estate Index, which Frasers Logistics & Industrial Trust joined in March 2019.
Independent property analyst Royston Foo said for OUE C-Reit, it enjoys fewer benefits from an enlarged portfolio but a merger will alleviate concern on the "CPPU timebomb" - with unitholders facing a DPU dilution based on conversion of convertible perpetual preferred units (with conversions due October 2019).
He added that OUE H-Trust unitholders benefit more from an improved asset/sector diversification and a potential cash payout. As for sponsor OUE Ltd, he said an enlarged Reit make asset recycling easier.
The deal is expected to complete in August 2019 but no leadership team has been announced yet.
OUE C-Reit and OUE H-Trust will need to seek approval from their unitholders and stapled securityholders for the merger. The trust scheme also needs to be sanctioned by the Singapore Court.
OUE H-Trust will delist from the Singapore Exchange upon approval of the merger, becoming wholly owned by the OUE C-Reit trustee.
Citigroup, Credit Suisse and OCBC are the financial advisers to OUE C-REIT's manager, while BofA Merrill Lynch is sole adviser to OUE H-Trust's managers for the proposed merger and the trust scheme.
OUE C-Reit, OUE H-Trust and parent company OUE Ltd all called for trading halts on Monday morning before the announcements.
TRENDING NOW

Fed hike throws Singapore banks a margin lifeline; UOB most likely to feel impact

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Real-estate veteran Desmond Sim quits from CEO roles at Realion, ETC

Chagee, Mixue and Luckin won the market. Sustaining their edge is the harder part

