

Wealthy investors head online for private markets products as quality, access improve
Lower entry points that make it easier to diversify, greater control over portfolio are some advantages cited
SELF-SERVE online investment platforms are gaining traction among the well-heeled, who have historically been served by private banks or wealth management providers.
A better fee structure is one reason, but product options have also increased on these platforms and service levels may be better.
Small and mid-sized family offices (FOs), in particular, told The Business Times that platforms offer them access to private market funds at palatable entry sizes.
“Circumstances are helping us,” said Hugh Chung, chief investment advisory officer at investment platform Endowus.
General partners (GPs) – who manage private markets funds – are asking to distribute their funds through Endowus’ platform, he noted, and are willing to make concessions such as accepting smaller allocations for a less institutional client base.
In the past, larger private equity GPs required that an investor commit at least US$10 million to one fund – something possible for only institutional investors and very large FOs.
Through self-serve platforms, however, GPs now accept minimum investments of as little as US$50,000. For an accredited investor in Singapore with financial assets of S$1 million, that would work out to less than 6.5 per cent of the total portfolio.
Many GPs have also launched or are in the process of launching open-ended funds specifically to attract this retail segment, Chung added.
Unlike the typical closed-ended private markets fund, which may not return any cash until the fund reaches the end of its life and is liquidated, open-ended funds offer small liquidity opportunities at fixed intervals.
A GP might choose to invest a portion of the fund in a more liquid instrument, which means giving up some return. But retail audiences have been receptive to open-ended funds because the liquidity option gives them an additional financial buffer.
GPs need to evolve, said Mathieu Chabran, co-founder of Tikehau Capital, which offers such so-called semi-liquid products. “Digital platforms offer a powerful way to stay competitive.”
As at June, private investors accounted for 30 per cent of Tikehau’s 46 billion euros (S$66 billion) in assets under management. “Our strategy is to make institutional-quality products accessible to a broader audience,” Chabran said, adding that this is done both through traditional channels such as private banks as well as its digital platform Opale Capital.
Acumen without opportunity
GPs that welcome retail investors are finding a keen, even sophisticated, audience.
Chung said accredited investors using Endowus might work in the financial industry, but previously lacked the opportunity to access private market products.
“These are people who are deliberate and focused about what they want,” Chung added – but what they want might not be available to them.
“Even if they qualify to be clients of big private banks, they are not the biggest fish; so their experience would be very different (from the experience of the very wealthy).”
Shilpi Chowdhary, group chief executive officer of asset manager Lighthouse Canton, pointed out that at the “mass-affluent level or high-net-worth individual (HNWI) level, the breadth of innovative investment strategies or alternative investment strategies is not there”.
“Agility and the ability to self-serve is another demand,” he said. “The next-generation wealthy are more tech-savvy and sometimes prefer to have greater control over their portfolio, many opting to monitor their own portfolios and trades, and act on investment advice.”
For smaller FOs, meanwhile, lower entry points make it easier to diversify across multiple private market products. They can learn more while they invest, and take their time to get comfortable with managers.
The private markets option is also increasingly desirable thanks to the outperformance of the endowment model – so-called because of its popularity among the endowment funds of elite universities.
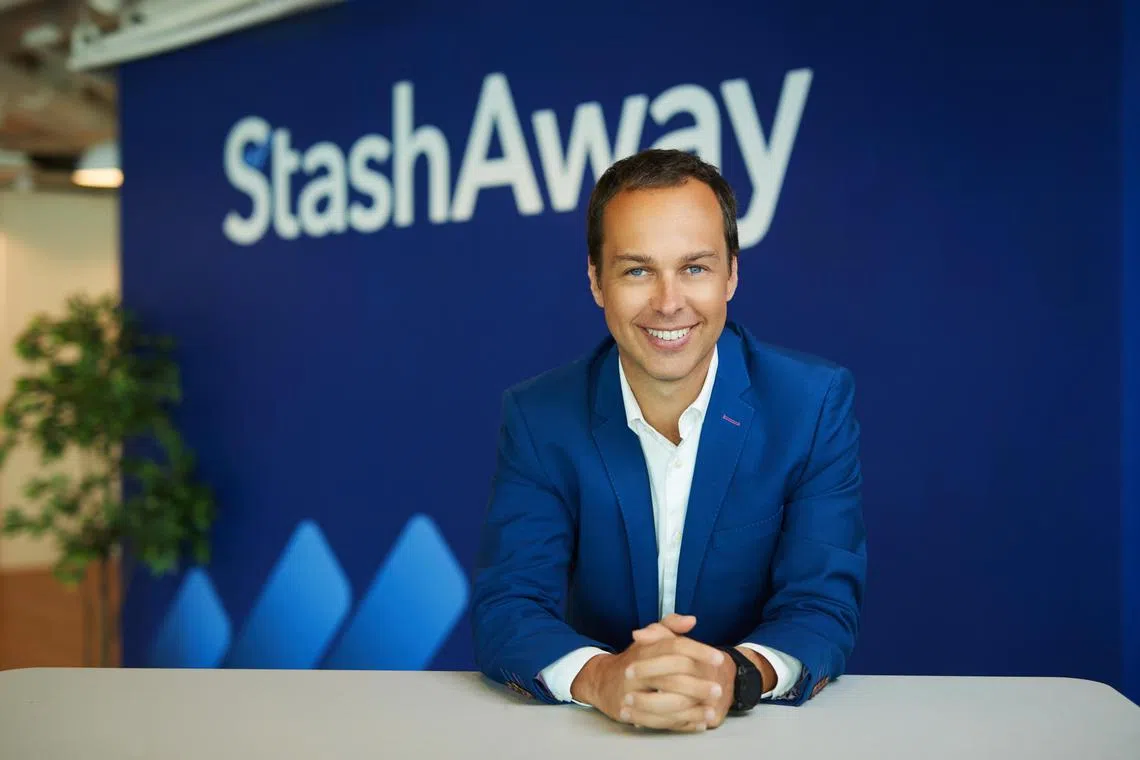
Michele Ferrario, co-founder and CEO of StashAway, said the company’s offerings for accredited investors have been crafted specifically to allow more people to access this model.
“The problem we are trying to solve is how to allow the (mass affluent) to do what Harvard does, what GIC does,” noted Ferrario, referring to Singapore state investor GIC and the Harvard University endowment. With billions at their disposal, such investors are able to diversify across hundreds of investments.
StashAway Reserve helps accredited investors achieve greater diversification in private markets by allocating commitments across multiple funds through the use of fractionalisation.
Arta Finance is targeting a similar audience with an online platform that aims to replicate the services of a private bank or a FO – but for the individual accredited investor.
Its Singapore country manager Amanda Ong said this segment is still “quite underserved” despite the entry of online platforms into the wealth market.
Arta, which launches officially in Singapore on Oct 11, recently announced a strategic investment from the Singapore Economic Development Board’s investment arm.
It aims to differentiate itself by offering not only investment products, but also ancillary services that are usually part of an FO set-up, such as tax planning and the creation of bespoke indices.
The next stage of growth for these platforms is educating audiences who have the ability but not the inclination to invest in private markets.
Ong noted that the investment audience has matured significantly since the first online platforms entered the Singapore market, but that the Republic’s investors are still not as knowledgeable about private markets as investors in the United States.
Even accredited investors in Singapore tend to first reach for real estate or insurance products, she said. “The first step for someone like us is just to educate people on investing.”






