

Wee Hur unloads 10% stake in student housing fund to GIC-linked buyer for gain of over S$90m
Buyer has links to GIC
Janice Lim
WEE Hur Holdings will be selling a 9.9 per cent stake in Wee Hur PBSA Master Trust (WHPMT), an Australian focused purpose-built student accommodation fund, for A$112.7 million (S$113.3 million), said the property developer and builder in a bourse filing on Friday (Apr 22).
Other unit holders of WHPMT holding a 40 per cent stake will also divest all of their interests in the property trust, valuing the total deal at A$567.9 million.
The deal values the fund at A$1.14 billion, which is 2.8 times' its current value on Wee Hur 's books.
Based on the company's latest financials for FY2021 ending in December last year, Wee Hur's 60 per cent stake in WHPMT was valued at S$241.92 million.
Wee Hur's share of the deal consideration is A$54.6 million, which was equivalent to 30 per cent of Wee Hur's market capitalisation just before the deal was announced.
After the completion of the deal, Wee Hur will hold a 50.1 per cent stake in the fund while the buyer, Reco Weather, will own 49.9 per cent.
According to Wee Hur, Reco Weather is a Singapore-based investment holding company backed by a global institutional investor. Documents show the investor is linked to state investment firm GIC.
According to a filing with the Accounting and Corporate Regulatory Authority, Reco Weather shares the same address as GIC and its directors are senior vice presidents of GIC's real estate division.
When contacted by The Business Times, GIC declined to comment.
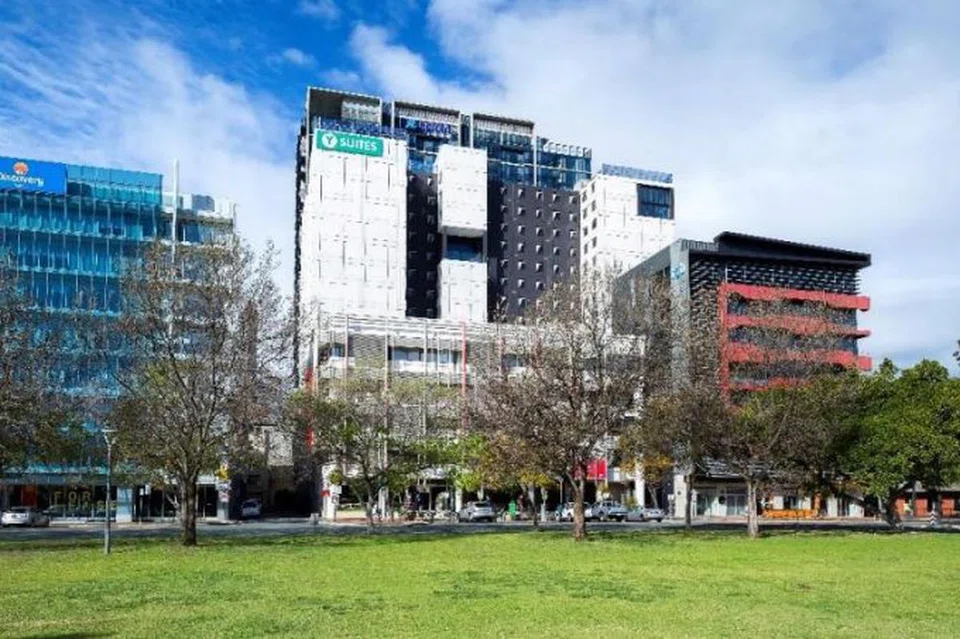
WHPMT's portfolio current comprises 5,662 beds across 7 student accommodation properties located in Sydney, Melbourne, Brisbane, Adelaide and Canberra.
As only 4 of the assets are operational, while the remaining 3 are to be completed before the end of 2023, the transaction is to be completed over 3 stages of settlement depending on when the properties are being completed.
Wee Hur's executive chairmain, Goh Yeow Lian, said: “We are extremely pleased to have done a recapitalisation of our first Australia focused PBSA fund, providing exit certainty for our investors within the fund term and providing a war chest for the group from the partial recycling of capital should further investment opportunities arise."
The deal is slated to be completed before Jan 1, 2024.
After discussions with transaction advisers, market feedback and security requirements imposed by the banks that are currently financing the development of the student accommodation, the 49.9 per cent divestment was deemed the most optimal exit strategy for unitholders, while ensuring Wee Hur was still the majority stakeholder.
Under the terms of the trust deed established in December 2016, the manager of WHPMT had to prepare an exit strategy before its term expiry on Jun 30, 2022.
The sale also reduces Wee Hur's exposure to fund any additional equity injections into the student accommodation fund if it does require the funds for any cash flow and refinancing issues.
Wee Hur also noted that Reco Weather offered the best price and terms, and it met its target reserve price set internally before the Covid-19 pandemic.
Assuming the sale had been completed on Dec 31, 2021, Wee Hur's net tangible assets per share as at end-2021 would have increased to S$0.59 from S$0.49. If the deal had been completed on Jan 1, 2021, earnings per share for FY2021 ended December would have increased to 11.85 Singapore cents from 0.07 cent. On a pro forma basis, the excess proceeds over the carrying value of the fund units would be S$91.4 million.
Goh Wee Ping, chief executive officer of WHPMT's manager Wee Hur Capital, said that it will still take some time to stabilise its existing portfolio to generate a healthy annual cash flow, even as the company is constantly looking out for more opportunities in Australia.
"Australia definitely remains a strong tertiary education destination that will continue to attract tertiary students, international and domestic alike. The difference is that now, more than ever, we need to be very selective in where we want to be, focusing on sites that are in great locations that are still underserved by the market, as the market has definitely seen a marked increase in PBSA (purpose-built student accommodation) supply over the past decade," he added.
"Overall, though, we think that serious investment activity in the sector is just getting started and there’s still a long way to go before hitting maturity levels like in the United Kingdom or the United States".






